All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 4 November 20263 min read

Vistar Amar (VISTARAMAR) Profit Crashes 80% as Revenue Halves in Q2 FY27

The fishmeal processor's quarterly revenue fell 57% sequentially, erasing most of its profit and highlighting the volatile nature of its raw-material-dependent business.

By Abhinav Swaroop, CFA, Chief Business Officer: Hexawealth · Created 4 November 2026

Vistar Amar's Q2 FY27 saw a sharp sequential decline, with revenue dropping 57% and profit falling 80%. While year-on-year comparisons show a recovery from a loss, the quarter underscores the business's exposure to volatile raw material supply and pricing.

For a fishmeal processor, the quarter is written by the sea. Vistar Amar’s September quarter shows what happens when that rhythm falters, as revenue more than halved from the prior three months and profit followed it down.

The numbers tell a story of two speeds. Year-on-year, revenue jumped 140% to ₹27.12 crore, swinging from a loss to a ₹0.83 crore profit. Sequentially, the picture reversed: revenue fell 57% from ₹63.37 crore and profit plunged 80% from ₹4.06 crore. The net profit margin contracted to 3.1% from 6.4% last quarter.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin

MetricCurrentQ2 FY27 (Sep 2026)PreviousQ1 FY27 (Jun 2026)
Revenue (₹ Cr)
27.12
63.37
Profit (₹ Cr)
0.83
4.06
Net Profit Margin
3.1%
6.4%

Why the top line collapsed

The research offers no single event, but points to the inherent volatility of the business. A report from ReportsRadar notes that net material costs rose to about 72% of revenue from 59.5% a year ago, squeezing margins as sales volume fell. The business depends entirely on the seasonal availability of marine fish, where weather and fishing cycles can shrink supply overnight.

The margin squeeze that followed

Even as total expenses fell 55% in line with lower sales, profitability weakened. The margin contraction, according to Univest, stemmed from the steep revenue drop outpacing cost savings. With raw material setting the price, the company’s margin is built on conversion efficiency, which appears to have suffered this quarter.

An outlook built on volatility

Management did not provide explicit new guidance. The Univest analysis states the full-year picture for FY27 will depend entirely on the quarters ahead. The company’s own annual report lists fluctuating raw material supply and prices as a principal risk, a reality this quarter made clear.

Key Points

  • Revenue fell 57% quarter-on-quarter to ₹27.12 crore, erasing the strong growth seen in Q1 FY27.
  • Net profit declined 80% sequentially to ₹0.83 crore, as margins compressed despite lower overall expenses.
  • The business remains highly exposed to the volatile supply and pricing of its core raw material, fish.
  • Year-on-year comparisons show a sharp improvement, but this is against a very weak base of a loss-making quarter in Q2 FY26.

Hexa Perspective

This quarter lays bare the operational reality of Vistar Amar. Its financials are a direct readout of raw material flows, with little insulation from seasonal and climatic swings. The 660-basis-point year-on-year margin improvement is a positive sign of operational recovery, but the 330-basis-point sequential drop shows how fragile that recovery is.

The company trades at a significant discount to the industry average P/E, reflecting the high-risk profile of its business model. For the earnings momentum to sustain, it needs more than a low base—it needs consistent raw material supply and stable conversion margins, two factors largely outside its control.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
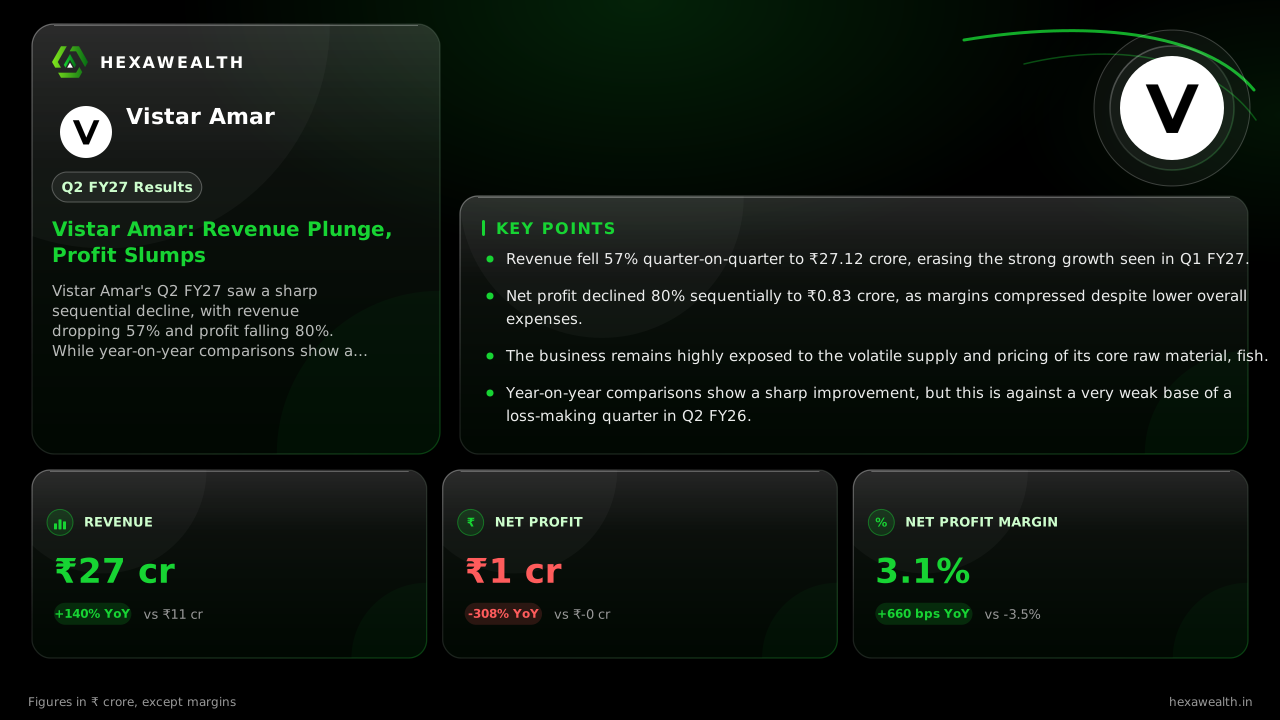
Vistar Amar (VISTARAMAR) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Vistar Amar's Q2 FY27 results?
Vistar Amar reported Q2 FY27 revenue of ₹27.12 crore, up 140% year-on-year. Net profit was ₹0.83 crore, a turnaround from a loss of ₹0.40 crore in Q2 FY26. However, compared to the previous quarter, revenue fell 57% and profit dropped 80%.
Why did Vistar Amar's Q2 FY27 revenue collapse by 57% sequentially?
Vistar Amar's revenue fell sharply in Q2 FY27 primarily due to the volatile nature of its raw material supply. The fishmeal business depends on seasonal fishing activity, and a drop in raw fish availability likely led to lower sales volume and processing activity compared to the previous quarter.
What caused Vistar Amar's profit to fall 80% QoQ in Q2 FY27?
Vistar Amar's profit fell 80% quarter-on-quarter because revenue dropped faster than expenses. While total expenses fell 55%, the company's net profit margin still contracted by 330 basis points to 3.1%, as per the analysis, indicating lower operational efficiency on reduced scale.
Why did Vistar Amar's net profit margin contract despite lower expenses?
Vistar Amar's net profit margin shrank to 3.1% from 6.4% last quarter because the 57% drop in revenue severely impacted operating leverage. ReportsRadar notes material costs rose as a percentage of sales, squeezing margins even as absolute expenses fell.
What was Vistar Amar management's commentary after Q2 FY27 results?
Explicit new guidance was not provided. An analysis by Univest states the FY27 outlook depends entirely on subsequent quarters, acknowledging the volatility. The company's annual report identifies raw material supply fluctuations as a key ongoing risk.
What is the demand and pricing environment for fishmeal?
The global benchmark price for fishmeal was $2,916 per tonne in September 2026, up 65% over 12 months, as per CommodityOrigins. Demand from aquaculture is growing, but supply is capped by biological limits and quotas, leading to price volatility that directly affects processors like Vistar Amar.
What is Vistar Amar's capacity utilization status?
Specific Q2 utilization rates are not disclosed. The company operates three plants in Gujarat. Its annual report states it focuses on improving capacity utilization, but operations are seasonal and aligned with fishing activity, which likely contributed to the quarter's volatility.
Did Vistar Amar's Q2 FY27 results beat analyst estimates?
There is no mention of published analyst estimates being missed or beaten in the available research. Reports generally present the reported figures against prior periods without a consensus comparison, focusing on the stark sequential decline.
What are Vistar Amar's key raw material supply risks?
Vistar Amar faces significant risks from the seasonal availability of marine fish, weather conditions affecting fishing, and volatility in raw material prices. The company's annual report states it must process purchased fish within 48 hours, leaving it exposed to immediate supply shocks.
How did Vistar Amar's stock price react to the Q2 FY27 results?
The research snippets do not provide specific stock price movement data for the period immediately following the November 3, 2026, results announcement. The focus of the coverage is on the financial figures and their implications.
Vistar Amar Q2 profit drop
Vistar Amar's Q2 FY27 net profit was ₹0.83 crore, a drop of 80% from the ₹4.06 crore profit in Q1 FY27. This severe decline was driven by a 57% sequential collapse in revenue to ₹27.12 crore, highlighting the quarter's operational challenges.
Vistar Amar September quarter profit
Vistar Amar's profit for the September 2026 quarter (Q2 FY27) was ₹0.83 crore. This represents a year-on-year recovery from a loss of ₹0.40 crore in the same quarter last year, but a steep 80% fall from the profit of ₹4.06 crore in the June 2026 quarter.