Ramco Industries (RAMCOIND) Q2 FY27 Profit Climbs 24% as Margins Expand, Despite a Sharp Revenue Dip
The building materials firm posted strong profit growth on better margins, but revenue fell sharply from the previous quarter, highlighting seasonal volatility.
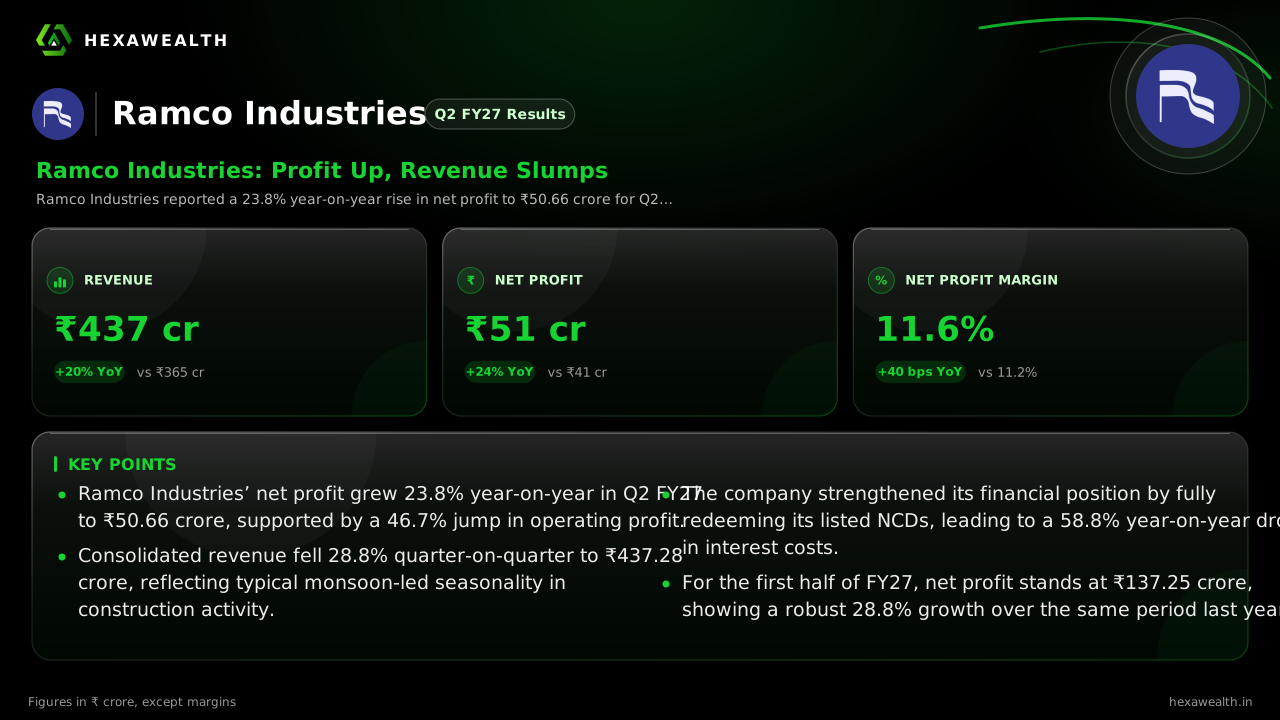
Ramco Industries reported a 23.8% year-on-year rise in net profit to ₹50.66 crore for Q2 FY27, driven by margin expansion. However, revenue fell 28.8% sequentially, reflecting typical seasonality in construction demand.
For a building materials company, the September quarter often brings a seasonal pause as monsoon rains slow construction. Ramco Industries’ Q2 FY27 results fit that pattern, delivering a story of two trends. Profitability improved from a year ago, but the top line took a significant step back from the previous quarter.
The numbers show a clear divergence. Revenue of ₹437.28 crore was up 19.6% from a year earlier but down 28.8% from the June quarter. Net profit of ₹50.66 crore rose 23.8% year-on-year, yet fell 41.5% sequentially. The net profit margin held at 11.6%, a slight 40-basis-point improvement from Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 437.28YoY +20% | 613.81 | 365.48 |
| Profit (₹ Cr) | 50.66YoY +24% | 86.59 | 40.93 |
| Net Profit Margin (%) | 11.6YoY +3.6% | 14.1 | 11.2 |
The Efficiency Story Behind the Profit
Despite the revenue drop, operating efficiency provided a cushion. According to a report by Univest, operating profit surged 46.7% year-on-year to ₹76.88 crore. This points to effective cost management, with total expenses falling in line with the lower sales.
A major contributor was a sharp 58.8% year-on-year decline in interest expense. The company’s filings, noted by Arthneeti, show it fully redeemed its listed Non-Convertible Debentures during the quarter. This debt repayment strengthens the balance sheet and cuts future finance costs.
A Seasonal Slowdown, Not a Structural Shift
The steep sequential revenue decline aligns with industry seasonality. Reports from FlashFinance and AngelOne frame it as a consolidation from a strong preceding quarter. Peer Everest Industries also reported only modest growth, indicating a broader market pause.
Management has not provided formal guidance, as per Arthneeti. The half-year picture is healthier, with net profit up 28.8% year-on-year to ₹137.25 crore. This suggests the Q2 dip is a temporary trough in the annual cycle.
Key Points
- Ramco Industries’ net profit grew 23.8% year-on-year in Q2 FY27 to ₹50.66 crore, supported by a 46.7% jump in operating profit.
- Consolidated revenue fell 28.8% quarter-on-quarter to ₹437.28 crore, reflecting typical monsoon-led seasonality in construction activity.
- The company strengthened its financial position by fully redeeming its listed NCDs, leading to a 58.8% year-on-year drop in interest costs.
- For the first half of FY27, net profit stands at ₹137.25 crore, showing a robust 28.8% growth over the same period last year.
Hexa Perspective
The quarter underscores the seasonal nature of Ramco’s business. The year-on-year profit growth and margin resilience are positive, showing the company can manage costs when volumes dip. The decisive debt reduction is a long-term positive, lowering financial risk.
The key question is the pace of demand recovery post-monsoon. With a near-debt-free balance sheet, the company is well-placed to benefit from any uptick in construction activity. However, its performance remains tightly linked to the broader building materials cycle, which faces both government-led tailwinds and raw material cost headwinds.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.