Panama Petrochem (PANAMAPET) Q2 FY27 Profit Dips 21% as Margins Retreat From Q1 High
The specialty petroleum products maker posted a 359% yearly profit surge but saw sequential pressure as costs rose and margins normalized from an exceptional Q1.
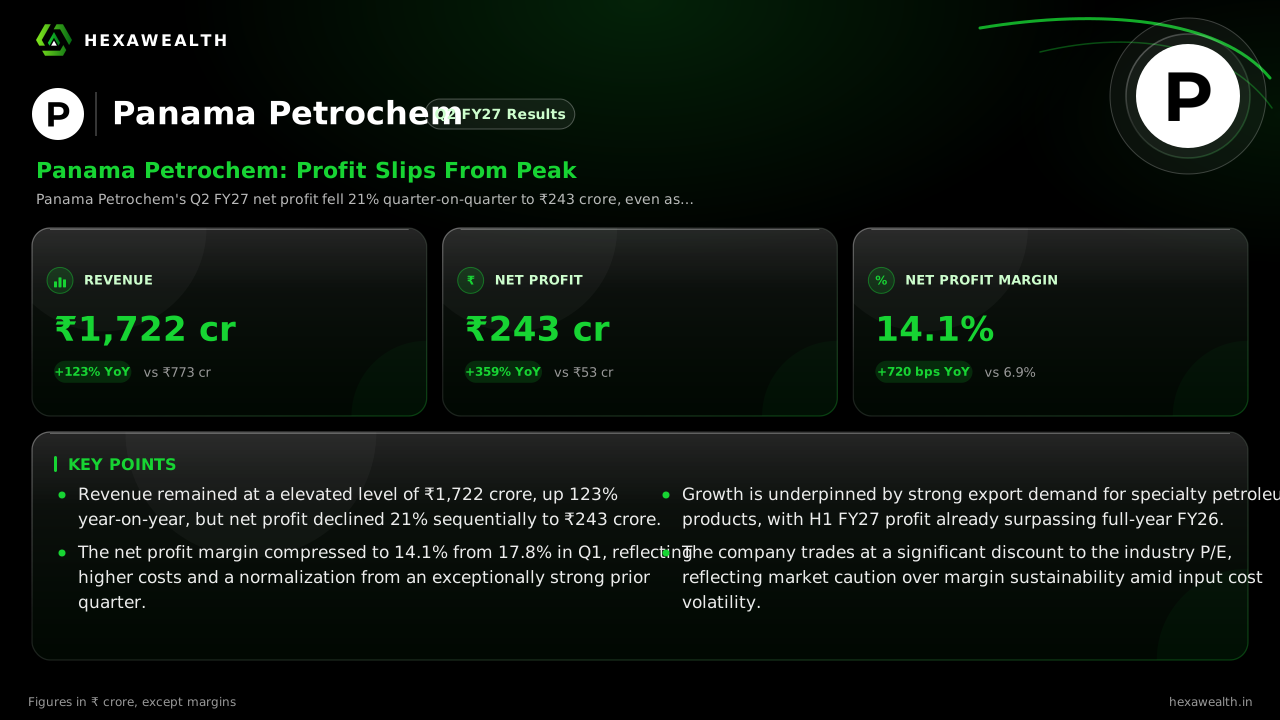
Panama Petrochem's Q2 FY27 net profit fell 21% quarter-on-quarter to ₹243 crore, even as revenue held near record highs. The dip reflects a normalization of margins from an exceptionally strong first quarter, driven by higher costs and a changing product mix.
For Panama Petrochem, the story of FY27 is being written in two distinct chapters. The first was a stunning breakout, where revenue more than doubled and profit margins surged past 17%. The second, revealed in the September quarter, shows what happens when that explosive growth meets the realities of cost and mix.
Revenue held remarkably steady at ₹1,722 crore, nearly matching the record ₹1,735 crore of Q1. This kept the yearly growth at a spectacular 123%. Profit, however, stepped back 21% sequentially to ₹243 crore. The net profit margin compressed to 14.1% from 17.8% in the prior quarter.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 1,722.34 | 1,735.15 |
| Net Profit (₹ Cr) | 243.34 | 308.91 |
| Net Profit Margin | 14.1% | 17.8% |
Why the margin peak was temporary
The drop from Q1’s peak margin was driven by a 5.8% rise in total expenses, as reported by FlashFinance. This points to higher input costs, a shift in product mix, or both. The prior quarter’s exceptional 17.8% margin was flattered by a structural advantage: roughly 30% of consolidated profit came from a tax-exempt UAE subsidiary, as noted by TradeBrains. While that advantage remains, the underlying operating margin faced pressure this quarter.
The export engine keeps running
The core driver remains robust demand for specialty petroleum products in export markets. FlashFinance reports the performance was driven by sustained specialty petroleum demand, particularly in export markets. This structural expansion has transformed the company’s scale, with first-half FY27 profit already exceeding the entirety of last fiscal year’s earnings. The company is backing this growth with capacity, having earmarked around ₹100 crore in capex for new multi-purpose plants over the next few years.
What the market is weighing
With no formal analyst consensus, the market’s measure is the company’s own trend. FlashFinance notes the Q2 profit print was 146% above its own historical trend, a testament to the new earnings plateau. The stock trades at a P/E of 6.6, a steep 46% discount to the industry average, suggesting skepticism about sustaining these elevated margins. The key watchpoint, as highlighted by FlashFinance, is the sustainability of revenue and margin levels amid volatile global crude and base oil pricing.
Key Points
- Revenue remained at a elevated level of ₹1,722 crore, up 123% year-on-year, but net profit declined 21% sequentially to ₹243 crore.
- The net profit margin compressed to 14.1% from 17.8% in Q1, reflecting higher costs and a normalization from an exceptionally strong prior quarter.
- Growth is underpinned by strong export demand for specialty petroleum products, with H1 FY27 profit already surpassing full-year FY26.
- The company trades at a significant discount to the industry P/E, reflecting market caution over margin sustainability amid input cost volatility.
Hexa Perspective
The quarter confirms Panama Petrochem’s successful leap to a higher revenue base, but also that Q1’s margin was a peak, not a plateau. The business is now operating at a scale where incremental gains will be harder won, dictated by the spread between base oil costs and specialty product realizations. The coming quarters will test whether the company can defend double-digit margins in this new normal, or if the Q2 level represents a more sustainable run-rate. The deep valuation discount prices in that uncertainty.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.