Gujarat Alkalies (GUJALKALI) Q2 FY27 Profit Jumps 385% as Margins Recover
The chemical maker's September quarter profit surged nearly fivefold year-on-year, driven by operational recovery and cost control, as it embarks on a major expansion.
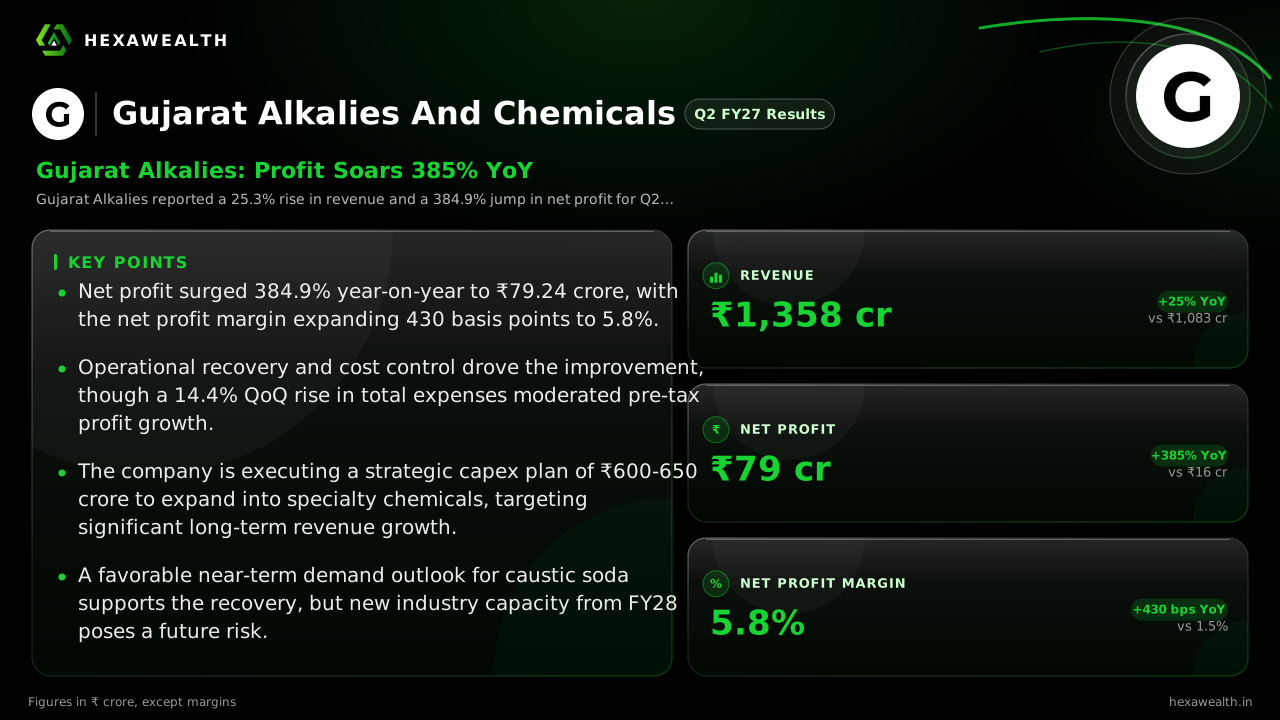
Gujarat Alkalies reported a 25.3% rise in revenue and a 384.9% jump in net profit for Q2 FY27. The recovery, marked by a 430 bps margin expansion, is supported by operational improvements and a strategic push into specialty chemicals.
For Gujarat Alkalies, the September quarter marks a decisive turn from the volatility of the past year. The chemical producer's profit surged nearly fivefold, signaling a recovery driven by operational discipline and a favorable demand environment for its core products.
The numbers show a clear rebound. Revenue rose 25.3% year-on-year to ₹1,357.5 crore, while net profit jumped 384.9% to ₹79.24 crore. Sequentially, both metrics improved, with revenue up 9.0% and profit rising 44.1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,357.5YoY +25% | 1,244.91 | 1,083.19 |
| Profit (₹ Cr) | 79.24YoY +385% | 54.98 | 16.34 |
| Net Profit Margin | 5.8%YoY +287% | 4.4% | 1.5% |
The profit before tax, however, dipped 8.5% quarter-on-quarter to ₹102.1 crore. This was due to a sharp rise in total expenses, which grew 14.4% QoQ, outpacing revenue growth.
The Margin Story Behind the Profit Jump
The real story is in the margins. The net profit margin expanded by 430 basis points year-on-year and 140 basis points sequentially. A report by StockFin.ai notes the company's operating profit margin jumped to 9.5% in the June quarter from 0.5% in the prior quarter, indicating significant operational improvement.
Cost optimization played a key role. Employee costs fell 10.8% year-on-year, and interest expense was down 2.7%. A lower tax outlay of ₹22.86 crore, compared to ₹56.64 crore in Q1, also boosted the bottom line.
A Commodity Tailwind with a Future Caveat
The recovery is underpinned by a robust chlor-alkali market. A report by India Ratings expects domestic caustic soda demand to grow at a low double-digit rate this fiscal year, supported by alumina and textile sectors. Industry capacity utilization is strong at 85-90%.
However, the same report cautions that a wave of new capacity due in FY28-29 could pressure prices and margins. For now, Gujarat Alkalies is riding a cyclical upswing while preparing for the next phase.
Funding an Ambitious Growth Plan
The company is not standing still. It has broken ground on a new food-grade phosphoric acid plant at Dahej, part of a strategic shift into higher-margin specialty chemicals. According to an investor presentation cited by Arthneeti AI, the company has a near-term capex pipeline of ₹600-650 crore approved.
Its ambitious 'Vision 2047' targets revenue of over ₹10,000 crore by FY31. Execution of these projects, funded by a modest debt increase, will be critical to sustaining growth beyond the current commodity cycle.
The market welcomed the results, with the stock rising over 10% on the announcement day, as per NDTV Profit data. Foreign institutional investors have raised their stake, while domestic institutions have trimmed theirs slightly over recent quarters.
Key Points
- Net profit surged 384.9% year-on-year to ₹79.24 crore, with the net profit margin expanding 430 basis points to 5.8%.
- Operational recovery and cost control drove the improvement, though a 14.4% QoQ rise in total expenses moderated pre-tax profit growth.
- The company is executing a strategic capex plan of ₹600-650 crore to expand into specialty chemicals, targeting significant long-term revenue growth.
- A favorable near-term demand outlook for caustic soda supports the recovery, but new industry capacity from FY28 poses a future risk.
Hexa Perspective
The quarter confirms a operational turnaround from a difficult period marked by losses and thin margins. The improvement is tangible, but its durability hinges on two factors.
First, the company must successfully commission its specialty chemical projects to build a more resilient margin profile. Second, it needs to navigate the impending industry capacity expansion that could soften pricing from FY28 onwards. The current recovery provides a crucial window to fund and execute its strategic shift.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.