Metalic Technoforge (METALIC) Q2 FY27's IPO Fuels 39% Revenue Growth, But Cash Flow Turns Negative
The newly listed forging company reported strong top-line growth for H1 FY27, but a sharp working capital build-up drained operating cash.
Metalic Technoforge's first results since its July IPO show revenue surging 39% year-on-year. However, a significant build-up in inventory and receivables turned operating cash flow deeply negative, highlighting execution challenges amid expansion.
For a newly listed company, the first earnings report sets the tone for how IPO proceeds will translate into performance. Metalic Technoforge's debut scorecard shows the capital is fueling rapid growth, but also revealing the strains of scaling up.
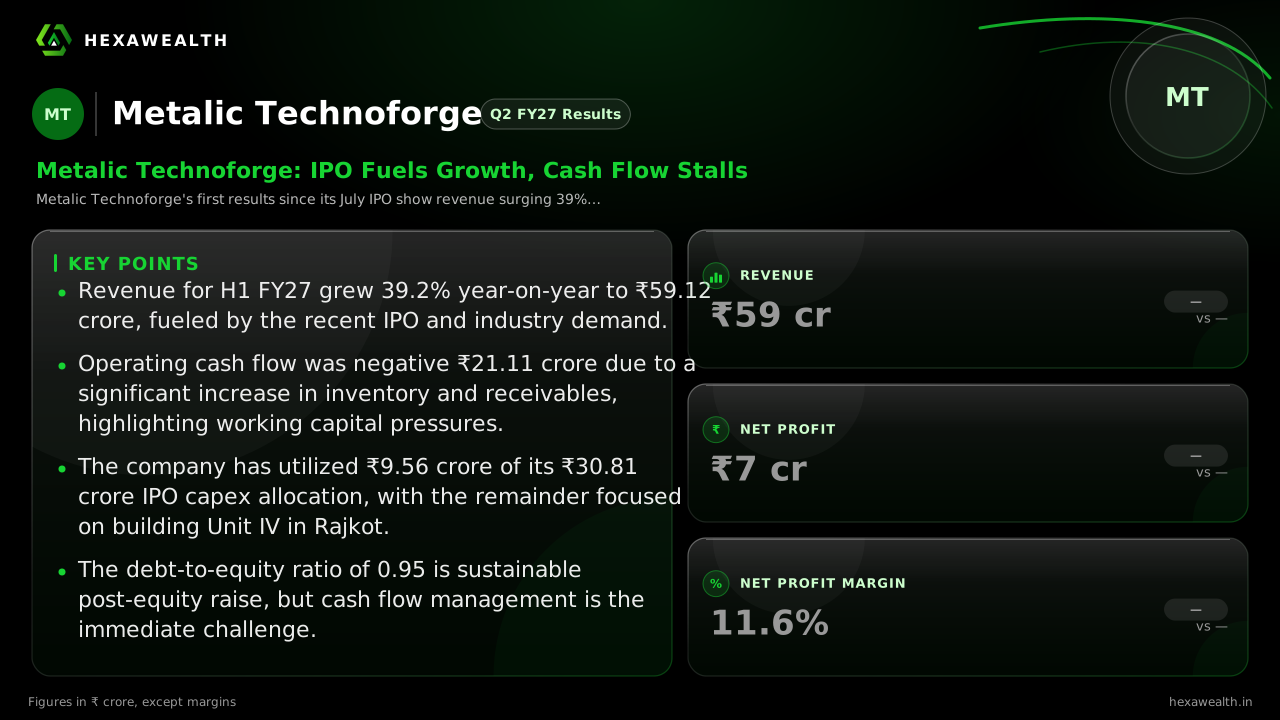
The standalone numbers for the half year ended September 2026 show revenue from operations at ₹59.12 crore, a 39.2% jump from the year-ago period according to Flash Finance. Profit before tax grew 31.6% to ₹9.87 crore. The net profit margin for the quarter stood at 11.6%.
| Period | Revenue (₹ Cr) | Profit (₹ Cr) | Net Profit Margin (%) |
|---|---|---|---|
| Q2 FY27 (Sep 2026) | 59.12 | 6.86 | 11.6 |
The Growth Engine and Its Cost
The revenue surge was broad-based, supported by the company's recent IPO. It raised nearly ₹50 crore in late July, with over ₹30 crore earmarked for capital expenditure. Flash Finance reports ₹9.56 crore of this has already been deployed towards building Unit IV and upgrading existing facilities in Rajkot.
This expansion is timely. Industry reports, like one from Kyro Ventures Research, suggest India's forging base may face a qualified capacity shortage, creating pricing power for those who add capacity first. Metalic is moving to capture this opportunity.
The Cash Flow Conundrum
Growth came at a cost to liquidity. Operating cash flow turned deeply negative at -₹21.11 crore for the half year, as reported by Flash Finance. The cause was a sharp build-up in working capital, specifically inventories and trade receivables.
This is a classic scaling challenge. As order books fill and production ramps up, cash gets tied up in raw materials and finished goods before customer payments arrive. For a capital-intensive business, managing this cycle is critical.
The company's balance sheet shows the IPO's immediate impact. According to Arthneeti, short-term borrowings decreased while equity increased significantly. The debt-to-equity ratio stands at 0.95, a manageable level post-equity infusion.
The Road Ahead
Management has not provided formal guidance, but the capital deployment path is clear. With ₹21.26 crore of IPO capex funds still unutilized, the focus is on executing the Rajkot expansion. The board has also approved leasing a facility in Pune for further manufacturing footprint growth.
The key watchpoint is working capital normalization. Investors will need to see if the negative cash flow was a one-quarter phenomenon tied to a production surge, or a recurring issue. The company's ability to convert its high growth into free cash will define its post-IPO success.
Key Points
- Revenue for H1 FY27 grew 39.2% year-on-year to ₹59.12 crore, fueled by the recent IPO and industry demand.
- Operating cash flow was negative ₹21.11 crore due to a significant increase in inventory and receivables, highlighting working capital pressures.
- The company has utilized ₹9.56 crore of its ₹30.81 crore IPO capex allocation, with the remainder focused on building Unit IV in Rajkot.
- The debt-to-equity ratio of 0.95 is sustainable post-equity raise, but cash flow management is the immediate challenge.
Hexa Perspective
The quarter paints a picture of a company in transition, using public capital to step on the growth accelerator. The top-line momentum is strong and aligns with a favorable sector outlook where capacity addition is rewarded.
The cash flow statement, however, introduces a note of caution. The substantial working capital absorption suggests the operational machinery is straining under rapid expansion. The next few quarters will test whether this is a temporary investment phase for future revenue or a structural inefficiency.
Success hinges on two factors: disciplined execution of the capex plan to bring new capacity online, and tighter management of the cash conversion cycle. If Metalic can navigate this, the growth story remains intact. If not, profitability will remain under pressure despite a rising top line.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.