Adisoft Technologies (ADISOFT) Q2 FY27' Revenue Slumps 39% Sequentially as Project Cycle Hits a Lull
Adisoft's Q2 revenue fell sharply from a strong Q4, but profitability improved as costs fell faster, with a robust order book waiting for new capacity.
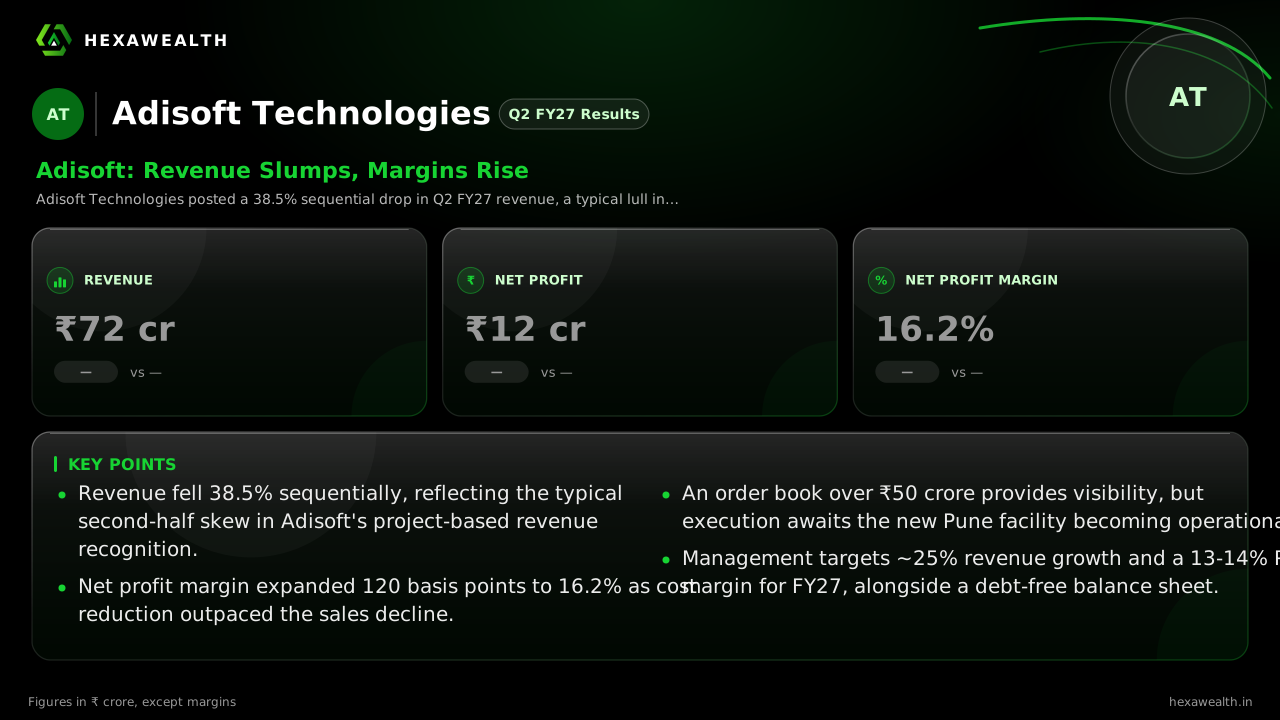
Adisoft Technologies posted a 38.5% sequential drop in Q2 FY27 revenue, a typical lull in its project-heavy cycle. Profit fell less sharply, lifting the net margin by 120 basis points, as cost discipline and a leaner balance sheet provided a cushion.
For Adisoft Technologies, an industrial automation solutions provider, quarterly results are a snapshot of project execution. The September quarter shows the business in a quiet phase between major deliveries, with revenue down sharply from the March quarter's peak.
Revenue fell 38.5% sequentially to ₹72.27 crore, and net profit declined 33.6% to ₹11.68 crore. Yet the net profit margin expanded to 16.2%, a 120-basis-point improvement from Q4 FY26, as total expenses fell even faster than sales.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 |
|---|---|
| Period | Sep 2026 |
| Revenue (₹ Cr) | 72.27 |
| Profit (₹ Cr) | 11.68 |
| Net Profit Margin (%) | 16.2 |
The seasonal lull after a strong finish
The sharp sequential decline is characteristic of the company's project-based model, where revenue recognition is heavily weighted to the second half. Flash Finance notes H2 accounted for 71% of FY26 revenue. The strong Q4 FY26, with revenue of ₹117.46 crore, created a high base, making the subsequent quarter's normalization appear steep.
Costs fell faster than the top line
Despite the revenue drop, profitability held up. Total expenses fell 40.5% quarter-on-quarter, led by lower employee and interest costs. The debt-to-equity ratio improved to 0.30x, and management, according to a First India report, aims for a debt-free status by FY27 end. This leaner operation helped protect margins when sales softened.
A full pipeline awaits new capacity
The near-term outlook hinges on order execution. The company reported an unexecuted order book exceeding ₹50 crore and an active pipeline of around ₹40 crore as of H1 FY27, per Flash Finance. The constraint is capacity. Its existing 12,000 sq ft facility is at peak utilisation.
A new 70,000 sq ft integrated plant in Bhosari, Pune, is key. First India reports it is expected to be partly operational from December 2026 and fully functional by April 2027. Management has told investors the expansion is designed to support 4-5 times the current revenue base.
Key Points
- Revenue fell 38.5% sequentially, reflecting the typical second-half skew in Adisoft's project-based revenue recognition.
- Net profit margin expanded 120 basis points to 16.2% as cost reduction outpaced the sales decline.
- An order book over ₹50 crore provides visibility, but execution awaits the new Pune facility becoming operational.
- Management targets ~25% revenue growth and a 13-14% PAT margin for FY27, alongside a debt-free balance sheet.
Hexa Perspective
This quarter underscores the execution-led volatility inherent in Adisoft's business. The margin resilience is a positive sign of operational discipline and a strengthening balance sheet. The story for the next few quarters is straightforward: converting the ₹50+ crore order book into revenue as new capacity comes online. The risk is any delay in the Bhosari facility's commissioning, which would push out the growth inflection. Investors are effectively paying for the capacity-led growth story to materialise on schedule.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.