Credo Brands (MUFTI) Q2 FY27 (Mufti) Profit Jumps 45% on Record Q2 Revenue
Credo Brands Marketing posted its highest-ever quarterly revenue of ₹189 crore, with net profit surging 45% year-on-year as its brand transformation gains traction.
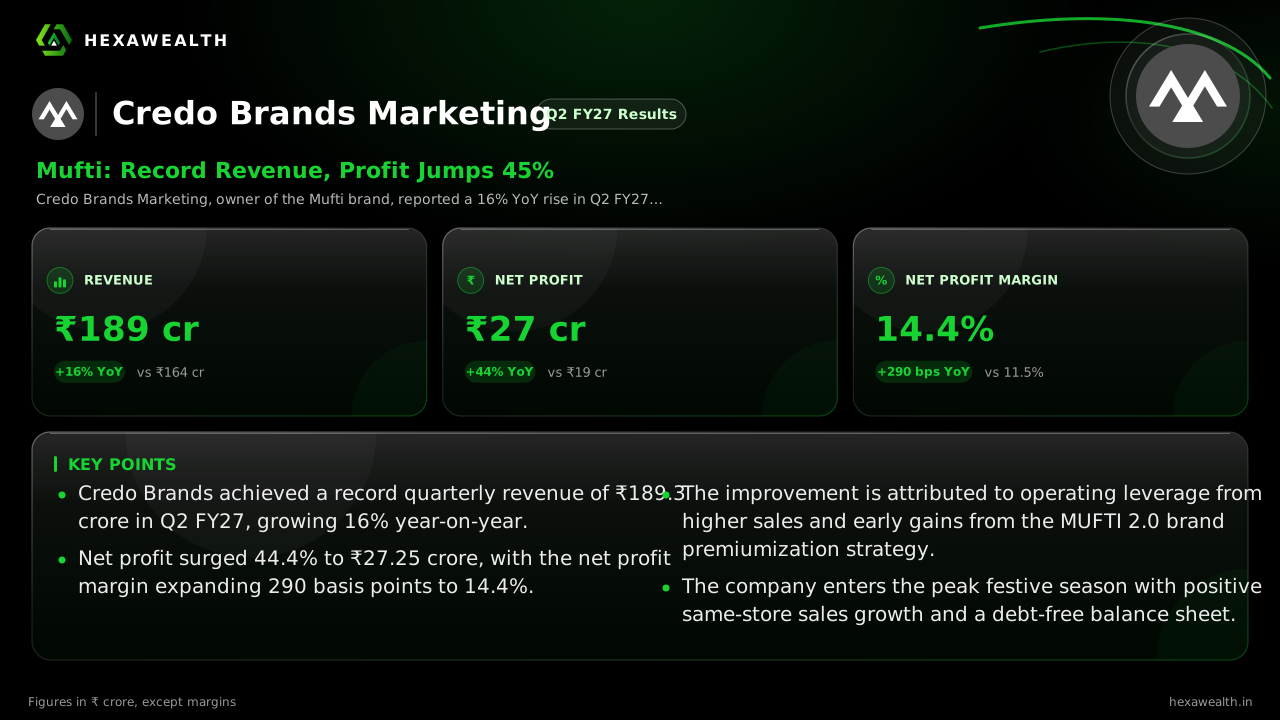
Credo Brands Marketing, owner of the Mufti brand, reported a 16% YoY rise in Q2 FY27 revenue to a record ₹189.3 crore. Net profit jumped 45% to ₹27.25 crore, signaling a strong recovery from a muted first quarter.
For Credo Brands, the owner of the popular Mufti menswear label, the September quarter was a decisive turnaround. After a muted Q1 where profits were squeezed by heavy brand investment, the company posted its highest-ever quarterly sales, with profit growth far outpacing the top line.
The numbers show a business hitting its stride. Revenue rose 16% year-on-year to ₹189.3 crore, while net profit jumped 44.4% to ₹27.25 crore. The net profit margin expanded to 14.4%, a sharp 290 basis point improvement from the same quarter last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 189.3 | 125.27 |
| Profit (₹ Cr) | 27.25 | 2.29 |
| Net Profit Margin | 14.4% | 1.8% |
Why margins expanded sharply
The profit surge was driven by operating leverage as sales scaled. According to a report from FlashFinance, EBITDA margin expanded 200 basis points to 31.4%. This came from a better product mix and the early benefits of the ‘MUFTI 2.0’ premiumization strategy, which focuses on upgraded store experiences.
Management had absorbed heavy marketing costs in Q1, which compressed margins. As revenue rebounded strongly in Q2, those fixed brand investments delivered more sales per rupee spent.
The demand shift and what comes next
Industry reports suggest a portion of festive demand shifted into Q3 this year due to the calendar. This means the strong Q2 print was not solely a seasonal pull-forward. The company also reported three consecutive quarters of positive same-store sales growth, a key indicator of underlying brand health.
Looking ahead, the sector faces margin pressures from rising input costs, as noted by Crisil Ratings. However, the company’s debt-free balance sheet and focus on premium retail give it room to navigate. The key will be sustaining the sales momentum into the festive-heavy Q3 to keep the operating leverage story intact.
Key Points
- Credo Brands achieved a record quarterly revenue of ₹189.3 crore in Q2 FY27, growing 16% year-on-year.
- Net profit surged 44.4% to ₹27.25 crore, with the net profit margin expanding 290 basis points to 14.4%.
- The improvement is attributed to operating leverage from higher sales and early gains from the MUFTI 2.0 brand premiumization strategy.
- The company enters the peak festive season with positive same-store sales growth and a debt-free balance sheet.
Hexa Perspective
This quarter marks a clear inflection from the investment-heavy, low-margin phase of Q1. The record revenue demonstrates the Mufti brand’s resonance, while the profit leap shows the model can deliver when sales scale. The sustainability of this margin expansion now hinges on maintaining this sales velocity, especially as the industry grapples with cost inflation. Investors are weighing a strong operational rebound against a stock that has declined nearly 24% over the past year, trading at a significant discount to the industry PE.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.