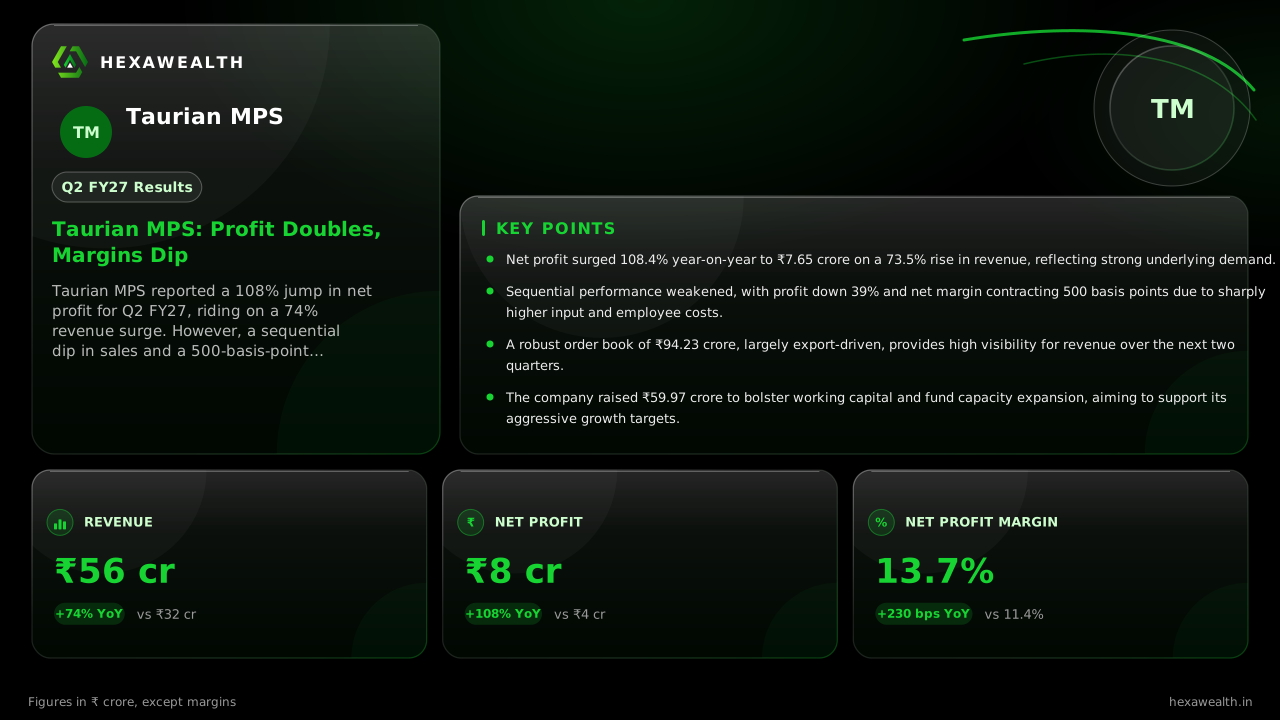
Taurian MPS reported a 108% jump in net profit for Q2 FY27, riding on a 74% revenue surge. However, a sequential dip in sales and a 500-basis-point margin contraction point to near-term pressures.
For Taurian MPS, a maker of crushing and screening plants, the September quarter was a story of two speeds. While the year-on-year growth is explosive, a sequential slowdown reveals the growing pains of a company scaling up.
The numbers show a business that has dramatically outgrown its past. Revenue for the quarter ended September 2026 stood at ₹56.01 crore, a 73.5% leap from the same period last year. Net profit more than doubled to ₹7.65 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
Metric
CurrentQ2 FY27 (Sep 2026)
PreviousQ4 FY26 (Mar 2026)
Revenue (₹ Cr)
56.01
67.06
Profit (₹ Cr)
7.65
12.54
Net Profit Margin (%)
13.7
18.7
Yet, compared to the March 2026 quarter, revenue fell 16.5% and profit dropped 39%. The net profit margin contracted by 500 basis points sequentially, even as it improved year-on-year.
The cost of scaling up
The sequential margin squeeze is tied directly to the costs of expansion. According to a report by Multibagg.ai, raw material costs in the first half nearly tripled year-on-year. Employee costs rose 93% and finance costs jumped 69%, as the company hired and borrowed to fuel growth.
These rising expenses outpaced revenue gains this quarter, compressing profitability. It’s a classic sign of a capital-intensive business investing ahead of future revenue.
A loaded order book sets the stage
The near-term outlook, however, is underpinned by strong demand. The company’s investor presentation, cited by Arthneeti, reveals an order book of ₹94.23 crore, with 76% from exports. This backlog is executable over the next four to five months, providing clear revenue visibility.
Management is targeting topline growth at a 45–50% CAGR over the coming years. A recent ₹59.97 crore fundraise, noted in The Wire, is earmarked to ease working capital constraints and add capacity at its Roorkee plant.
Key Points
Net profit surged 108.4% year-on-year to ₹7.65 crore on a 73.5% rise in revenue, reflecting strong underlying demand.
Sequential performance weakened, with profit down 39% and net margin contracting 500 basis points due to sharply higher input and employee costs.
A robust order book of ₹94.23 crore, largely export-driven, provides high visibility for revenue over the next two quarters.
The company raised ₹59.97 crore to bolster working capital and fund capacity expansion, aiming to support its aggressive growth targets.
“
Hexa Perspective
Taurian MPS is in a high-investment phase, where current margins are being sacrificed for future scale. The sequential dip is less alarming than the year-ago comparison suggests, as it reflects the cost of fulfilling a large order book and building capacity.
The next two quarters will be the real test. Execution of the ₹94 crore backlog must translate into revenue that outpaces the current cost inflation. If successful, the operating leverage from its expanded capacity could start to repair margins, making the current squeeze a temporary feature of its growth story.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were Taurian MPS's Q2 FY27 results?
For the quarter ended September 2026, Taurian MPS reported revenue of ₹56.01 crore, a 73.5% increase year-on-year. Net profit more than doubled to ₹7.65 crore, up 108.4% from the same quarter last year. However, both revenue and profit declined sequentially from the March 2026 quarter.
Why did Taurian MPS's net profit margin contract in Q2 FY27?
Taurian MPS's net profit margin contracted by 500 basis points sequentially in Q2 FY27 due to a faster rise in costs relative to revenue. As reported by Multibagg.ai, raw material, employee, and finance costs surged significantly as the company scaled operations, compressing profitability in the near term.
What is Taurian MPS's current order book status?
As of its Q2 FY27 results, Taurian MPS holds an order book of ₹94.23 crore, according to its investor presentation cited by Arthneeti. This backlog, which is 76% export orders, is expected to be executed over the next four to five months, providing strong revenue visibility.
What guidance did Taurian MPS management provide for future growth?
Taurian MPS management has set an ambitious target, aiming for topline growth at a compound annual rate of 45–50% over the coming years. The company also aims to increase its export contribution to 35% of revenue, as noted in its investor presentation.
How is Taurian MPS funding its expansion plans?
Taurian MPS recently raised ₹59.97 crore through a preferential allotment of shares and warrants, as reported by The Wire. The funds are allocated primarily for working capital (₹42 crore) and capital expenditure (₹10.22 crore) to accelerate order execution and expand manufacturing capacity.
What caused the sequential decline in Taurian MPS's revenue?
Taurian MPS's revenue declined 16.5% sequentially from Q4 FY26 to Q2 FY27. While the specific cause isn't detailed in available reports, the dip aligns with typical execution cycles in project-based heavy engineering, where revenue recognition can be uneven quarter-to-quarter.
Did Taurian MPS's Q2 results beat analyst estimates?
Available research snippets do not provide specific analyst consensus estimates for Taurian MPS's Q2 FY27 results. Therefore, a clear beat or miss versus market expectations cannot be determined from the current information.
What are the key risks to Taurian MPS's outlook?
Key risks include the company's ability to manage rising input and employee costs to protect margins, timely execution of its large order book, and potential macroeconomic or sectoral slowdowns that could affect demand for heavy engineering equipment.
How have institutional holdings in Taurian MPS changed recently?
According to SectorAlpha, domestic institutional investors (DIIs) have significantly reduced their stake in Taurian MPS over the last four quarters, cutting it from 6.3% to 0.5% by September 2026. This suggests a cautious institutional sentiment despite the company's strong growth numbers.
Taurian MPS Q2 Results 2026 (FY27): Order Book ₹94.23 Cr
In its Q2 FY27 results announced in November 2026, Taurian MPS reported a half-year profit of ₹7.65 crore, more than double the year-ago period. A key highlight was its order book of ₹94.23 crore, which provides strong visibility for revenue in the coming quarters.
Taurian MPS doubles half-year profit as revenue rises 73 percent to Rs 56 crore
Taurian MPS reported that its net profit for the first half of FY27 doubled to ₹7.65 crore, compared to ₹3.67 crore a year ago. Revenue from operations rose 73.5% to ₹56.01 crore for the half-year period, as covered by The Wire.