Manika Plastech (MANIKA) Q2 FY27 Profit Slips 25% From a Strong First Quarter
Revenue grew 42% year-on-year, but profit fell sharply from the June quarter as costs rose and operational cash flow lagged.
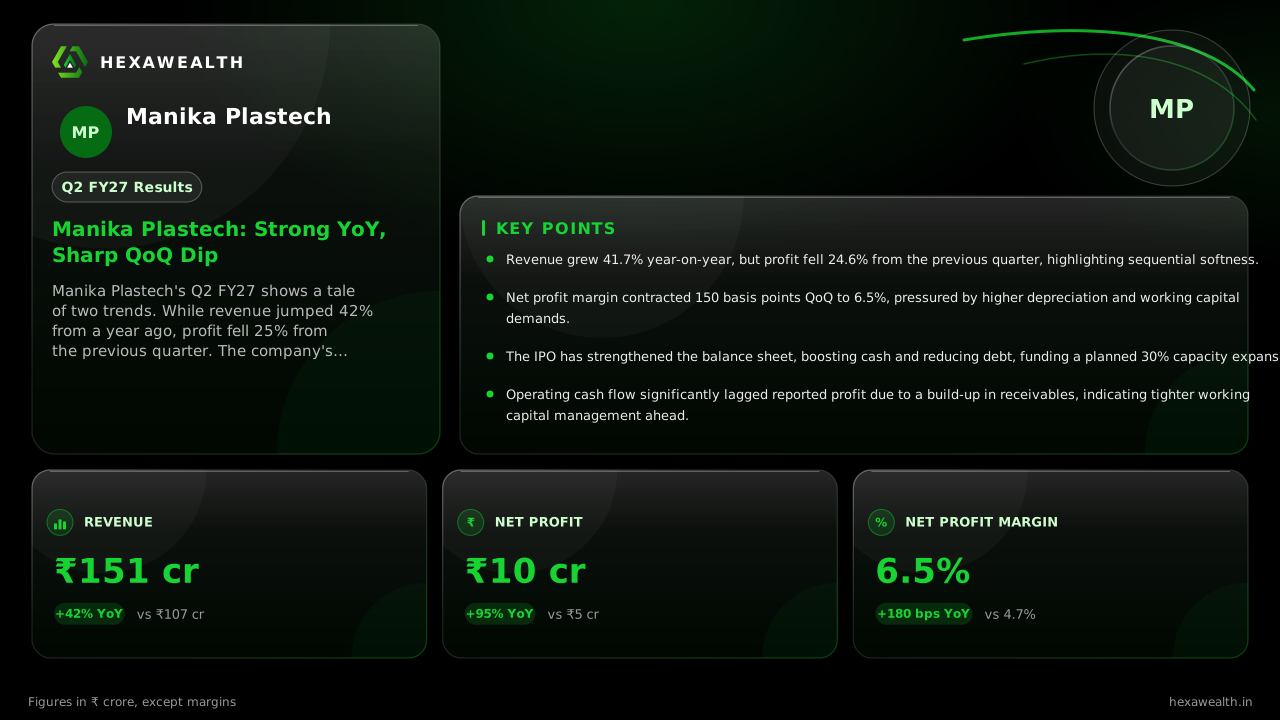
Manika Plastech's Q2 FY27 shows a tale of two trends. While revenue jumped 42% from a year ago, profit fell 25% from the previous quarter. The company's margin contracted as depreciation costs rose and cash generation slowed relative to reported earnings.
For a packaging company fresh from an IPO, the second quarter is about proving the growth story can hold. Manika Plastech delivered a strong year-on-year jump but stumbled sequentially, showing the fine line between scaling up and managing costs.
The numbers tell the split story. Revenue for the September quarter stood at ₹151.42 crore, a solid 41.7% increase from a year ago. Profit, however, fell to ₹9.86 crore, down 24.6% from the ₹13.07 crore earned in June.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 151.42 | 162.45 |
| Profit (₹ Cr) | 9.86 | 13.07 |
| Net Profit Margin | 6.5% | 8.0% |
Year-on-year, profitability improved sharply, with net margin expanding 180 basis points. The quarter-on-quarter drop of 150 basis points points to rising costs. According to the company's filings, depreciation expense rose 4.7% sequentially, reflecting new asset additions.
The costs that will not fall soon
The margin pressure came from two sides. First, higher depreciation is a structural shift as the company deploys IPO proceeds for capacity expansion. Second, operating cash flow for the half-year was just ₹4.59 crore, a fraction of the reported net profit, as noted by Scanx.trade.
This gap stems from a significant increase in working capital, including a ₹24.99 crore rise in trade receivables. Faster revenue growth is stretching collection cycles, tying up cash that would otherwise support operations or further debt reduction.
A balance sheet in transition
The recent ₹92.5 crore IPO has transformed the company's financial position. Cash reserves swelled to over ₹45 crore by September end from just ₹0.25 crore in March, as per the results filing. Borrowings also fell, supporting a healthier debt-to-equity ratio of 0.6.
This war chest is earmarked for growth. Manika Plastech plans a 30% capacity increase to 38,000 metric tonnes, as reported by Multibagg.ai. The capital will fund new machinery to enter the bottle packaging segment for FMCG and pharmaceutical clients.
Key Points
- Revenue grew 41.7% year-on-year, but profit fell 24.6% from the previous quarter, highlighting sequential softness.
- Net profit margin contracted 150 basis points QoQ to 6.5%, pressured by higher depreciation and working capital demands.
- The IPO has strengthened the balance sheet, boosting cash and reducing debt, funding a planned 30% capacity expansion.
- Operating cash flow significantly lagged reported profit due to a build-up in receivables, indicating tighter working capital management ahead.
Hexa Perspective
The quarter underscores the transition from a leveraged, private company to a publicly-funded growth story. The year-on-year comparisons are flattered by a low base, but the sequential dip reveals the real-time cost of expansion.
The path ahead hinges on two factors: successfully commissioning new capacity to drive revenue without further margin sacrifice, and converting accounting profit into consistent cash flow. The company's guidance, or lack of a detailed outlook in filings, leaves the near-term trajectory to execution against these operational challenges.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.