Zim Laboratories (ZIMLAB) Q2 FY27 Sales Jump 19% But Net Loss Deepens
Zim Laboratories posted a 19% revenue rise in Q2 FY27, yet higher costs for EU scale-up and new plants pushed the net loss to ₹2.05 crore.
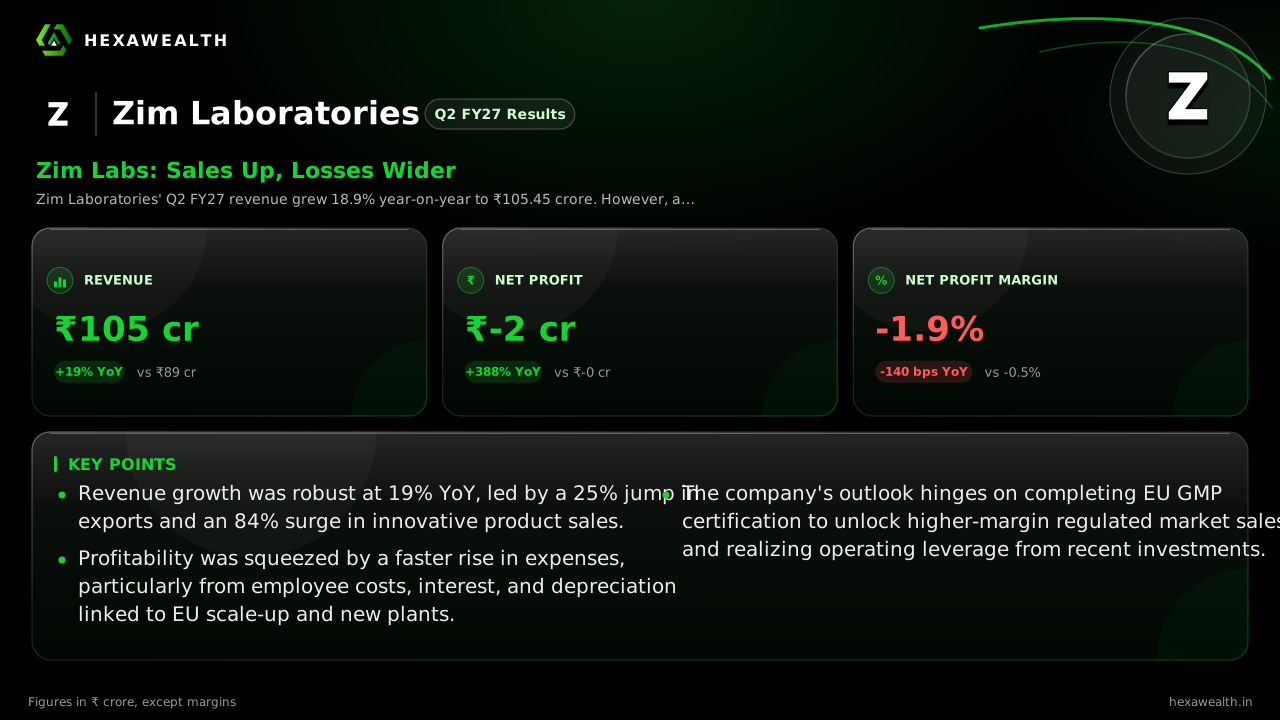
Zim Laboratories' Q2 FY27 revenue grew 18.9% year-on-year to ₹105.45 crore. However, a sharp rise in expenses, driven by EU business scale-up costs and higher depreciation, led to a net loss of ₹2.05 crore, wider than the year-ago period.
For Zim Laboratories, a specialist in novel drug delivery, the September quarter was about building for a regulated-market future. The company delivered strong top-line growth, but the cost of that ambition arrived before the payoff, leaving a deeper net loss.
Revenue rose 18.9% year-on-year to ₹105.45 crore, also up 12% from the June quarter. Yet total expenses grew faster at 21.3%, pushing the net loss to ₹2.05 crore from a loss of ₹0.42 crore a year ago. The net profit margin was -1.9%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 105.45YoY +19% | 94.18 | 88.71 |
| Net Profit (₹ Cr) | -2.05YoY -388% | -4.02 | -0.42 |
| Net Profit Margin (%) | -1.9YoY -280% | -4.3 | -0.5 |
Why the top line didn't reach the bottom
Exports, which drove 86% of revenue, grew nearly 25% year-on-year according to the company's investor presentation. The innovative products segment, including novel drug delivery systems, surged 84%.
However, the cost of scaling for Europe was significant. The company's presentation noted EBITDA margins fell 150 basis points to 7.3%, citing costs for EU business scale-up. Employee costs rose 20% and finance costs climbed 24.6% as borrowings increased to fund expansion.
The investment burden
Depreciation jumped 31% year-on-year, reflecting new asset commissioning. The company has commissioned a new cephalosporin plant and is completing EU GMP remediation, a process that cost about ₹18 crore over 15 months, according to the presentation.
Management expects a leaner cost base and wider market access to deliver improved operating leverage in future periods. Final EU GMP certification is anticipated in the December quarter.
Key Points
- Revenue growth was robust at 19% YoY, led by a 25% jump in exports and an 84% surge in innovative product sales.
- Profitability was squeezed by a faster rise in expenses, particularly from employee costs, interest, and depreciation linked to EU scale-up and new plants.
- The company's outlook hinges on completing EU GMP certification to unlock higher-margin regulated market sales and realizing operating leverage from recent investments.
Hexa Perspective
The quarter shows Zim Labs in a transitional phase. Revenue momentum is clear, especially in its high-growth innovative segment. Yet the path to sustained profitability is gated by the successful completion of its EU remediation and the subsequent ramp-up of supplies. Investors are paying a premium for this future, with the stock trading at a P/E of 54.9 against an industry average of 38.1. The next few quarters will test whether the operational improvements management anticipates can materialize quickly enough to justify that valuation and stem the losses.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.