Mafatlal Industries (MAFATIND) Q2 FY27 Profit Halves as Portfolio Reshuffle Bites
The company's profit fell 49% YoY despite strong growth in its core textiles and digital infrastructure segments, highlighting a strategic pivot away from low-margin lines.
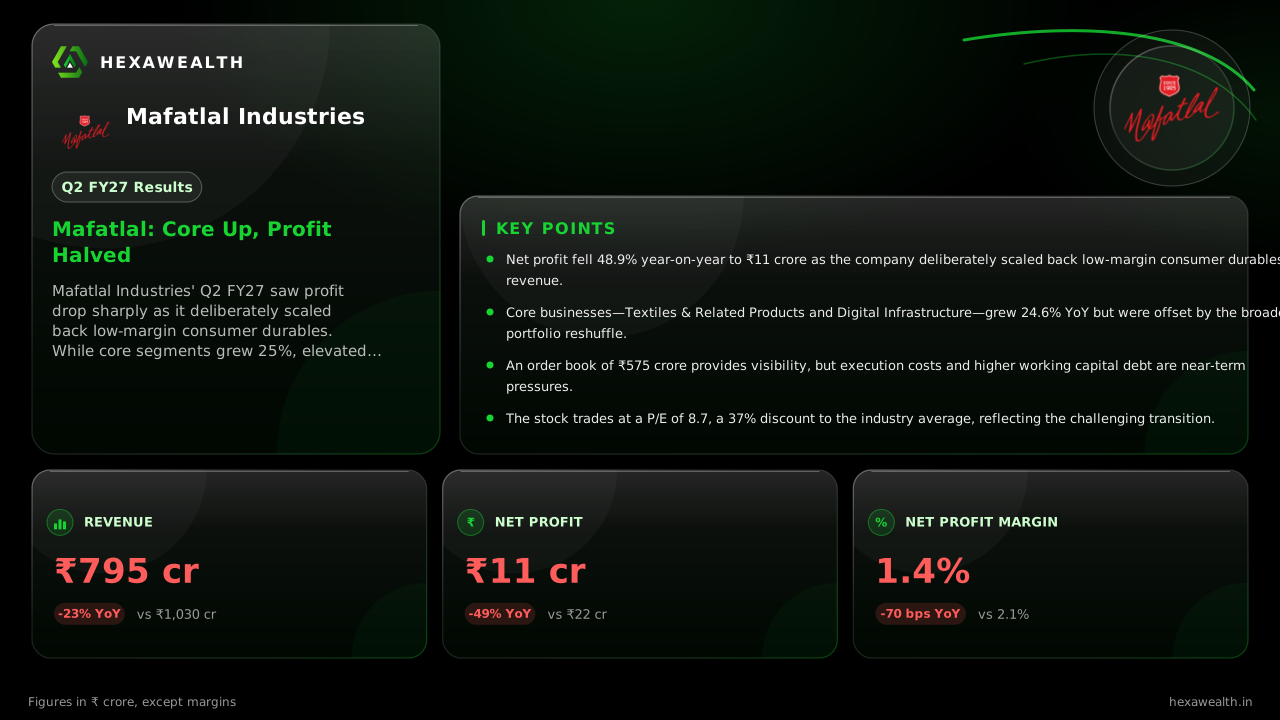
Mafatlal Industries' Q2 FY27 saw profit drop sharply as it deliberately scaled back low-margin consumer durables. While core segments grew 25%, elevated costs and a changing business mix compressed margins.
For Mafatlal Industries, this quarter was about choosing profitability over top-line bulk. The 119-year-old textile house is deliberately shrinking its low-margin consumer durables business to sharpen focus on institutional contracts and digital infrastructure. The result is a consolidated picture of pain now for promised gain later.
Revenue fell 23% year-on-year to ₹795 crore, while net profit nearly halved, dropping 49% to ₹11 crore. The net profit margin contracted by 70 basis points to 1.4%. Sequentially, both revenue and profit also declined from the June quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 795.0YoY -23% | 942.7 | 1,029.7 |
| Profit (₹ Cr) | 11.0YoY -49% | 14.7 | 21.5 |
| Net Profit Margin | 1.4%YoY -33% | 1.6% | 2.1% |
A Strategic Shrink
The headline decline masks a sharp divergence in performance. According to the company's release on Adgully, the core Textiles & Related Products and Digital Infrastructure segments together grew 24.6% year-on-year to ₹540 crore. The digital unit alone surged 344%.
This growth was more than offset by a calibrated reduction in lower-margin Consumer Durables opportunities. Management is prioritising business mix over pure revenue scale, a shift that explains the steep top-line fall against a strong year-ago quarter buoyed by large institutional orders.
The Cost of Execution
Even within growing segments, profitability was pressured. The company cited elevated costs for power, fuel, sub-contracting and logistics tied to executing institutional orders. While total expenses fell in line with sales, these input cost pressures prevented margins from improving.
The strategy is loading working capital, with gross debt rising to ₹83.2 crore from ₹60.8 crore at the end of last fiscal. This funds the inventory and receivables needed to fulfill large institutional contracts.
The Roadmap in the Order Book
The near-term visibility comes from a healthy order book. As of September 30, it stood at approximately ₹575 crore, with ₹462 crore in textiles. This provides a runway for the core business, even as the consumer durables segment remains in retreat.
Management, led by CEO Priyavrata Mafatlal, stated its focus remains on execution and strengthening capabilities for a more resilient business. The board also approved an interim dividend of ₹1 per share and a move to increase its stake in a digital infrastructure subsidiary.
Key Points
- Net profit fell 48.9% year-on-year to ₹11 crore as the company deliberately scaled back low-margin consumer durables revenue.
- Core businesses—Textiles & Related Products and Digital Infrastructure—grew 24.6% YoY but were offset by the broader portfolio reshuffle.
- An order book of ₹575 crore provides visibility, but execution costs and higher working capital debt are near-term pressures.
- The stock trades at a P/E of 8.7, a 37% discount to the industry average, reflecting the challenging transition.
Hexa Perspective
The quarter underscores a transition that is intentional but costly. Investors are paying for the cleanup as Mafatlal sheds low-quality revenue to build a more sustainable core around institutional textiles and digital projects.
The ₹575 crore order book suggests the strategy has demand, but the margin trajectory is the key watchpoint. Success hinges on whether the company can manage input cost inflation and convert this higher-quality order pipeline into better profitability over the next few quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.