Mold-Tek Technologies (MOLDTECH) Q2 FY27 Profit Nearly Triples on U.S. Expansion and Efficiency Gains
Mold-Tek's Q2 FY27 profit surged 198% YoY as U.S. subsidiary contributions and operational efficiency drove margins to a multi-quarter high.
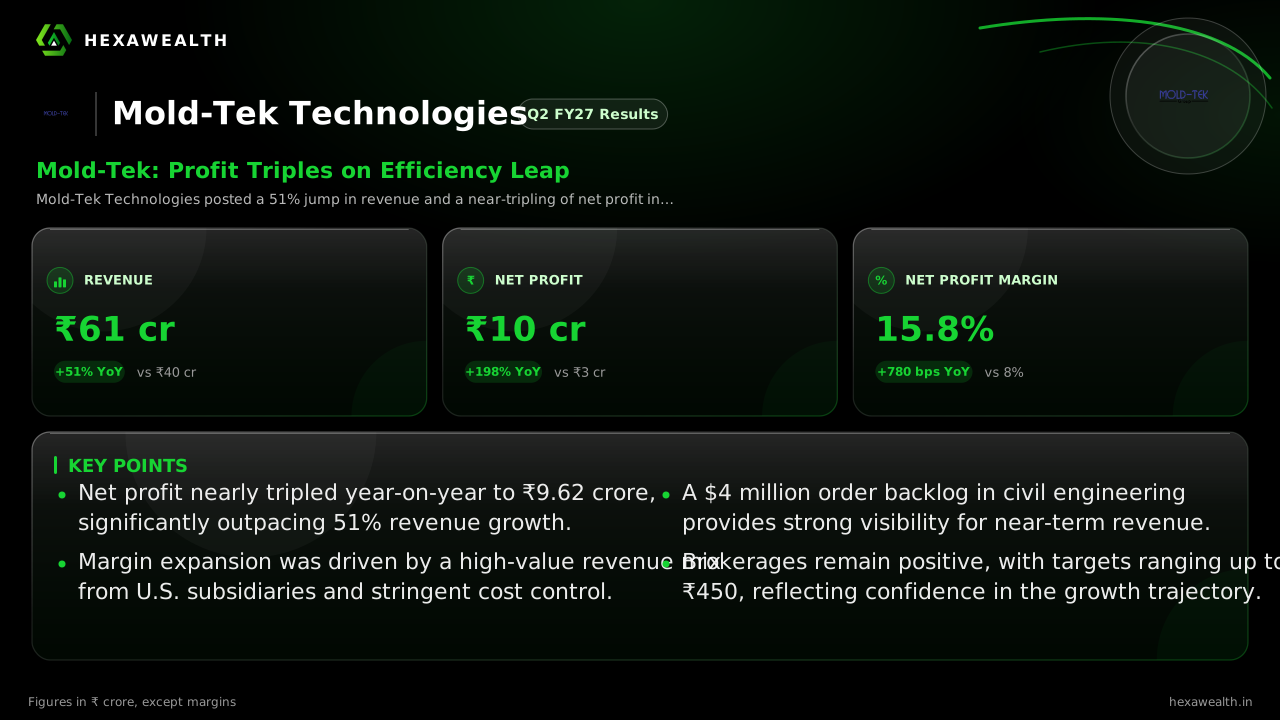
Mold-Tek Technologies posted a 51% jump in revenue and a near-tripling of net profit in Q2 FY27. The engineering services firm saw its net profit margin expand sharply to 15.8%, driven by its U.S. business and cost control.
For Mold-Tek Technologies, the September quarter was about turning a strategic U.S. expansion into a powerful profit engine. The engineering services provider delivered a near-tripling of net profit, showing that its push into higher-value civil and structural work abroad is paying off handsomely.
The numbers tell a story of broad-based acceleration. Revenue grew 51% year-on-year to ₹60.81 crore. More impressively, net profit soared 198% to ₹9.62 crore. This pushed the net profit margin to 15.8%, a sharp 780 basis point improvement from the same quarter last year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 60.81YoY +51% | 59.54 | 40.23 |
| Profit (₹ Cr) | 9.62YoY +198% | 9.00 | 3.23 |
| Net Profit Margin (%) | 15.8YoY +98% | 15.1 | 8.0 |
The U.S. Engine Driving Growth
A key driver was the disproportionate contribution from U.S.-based subsidiaries, particularly Beryl Engineering Inc. According to a report by ScanX, consolidated revenue growth of 64% for the half-year far outpaced standalone growth of 39%, pointing to the U.S. unit's outsized role. This shift towards offshore, higher-margin engineering services was a primary factor behind the EBITDA margin more than doubling to 24% for H1 FY27.
Management, cited by Arthneeti, highlighted a civil engineering work-on-hand backlog of approximately $4 million. This provides clear visibility for the coming quarters, supported by new project wins in data centres and convention centres.
Efficiency Gains Cement the Margin Story
While top-line growth was strong, the real story was operating leverage. Total expenses grew at nearly half the pace of revenue on a yearly basis. This discipline, combined with a richer service mix, led operating EBITDA to surge to ₹13.7 crore from ₹4.4 crore a year ago, as noted by SAHI.com.
Chairman J. Lakshmana Rao attributed the performance to business diversification and operational excellence. The company is entering new domains within civil engineering and has added significant clients, which supports both growth and pricing power.
A Pipeline Built for Sustained Momentum
The outlook remains constructive. The RBI's latest survey, reported by ET BFSI, indicates a positive demand outlook for India's services sector in Q3 FY27. For Mold-Tek, this aligns with a healthy order pipeline in the U.S. construction market and diversification into mechanical engineering services like transmission and distribution.
Brokerage sentiment reflects this confidence. Post-results, Prabhudas Lilladher maintained an 'Accumulate' rating with a target of ₹345, citing a healthy near-term outlook and an improving product mix. Axis Securities has a more bullish target of ₹450.
Key Points
- Net profit nearly tripled year-on-year to ₹9.62 crore, significantly outpacing 51% revenue growth.
- Margin expansion was driven by a high-value revenue mix from U.S. subsidiaries and stringent cost control.
- A $4 million order backlog in civil engineering provides strong visibility for near-term revenue.
- Brokerages remain positive, with targets ranging up to ₹450, reflecting confidence in the growth trajectory.
Hexa Perspective
The quarter demonstrates Mold-Tek's successful pivot from a domestic-focused player to a globally competitive engineering services provider. The margin leap is not a one-off but is structurally supported by the higher realizations of U.S. projects and operational consolidation.
The sustainability of this performance hinges on the continued conversion of its $4 million backlog and the ramp-up of newer service lines like mechanical engineering. While the stock trades at a discount to the industry PE, the market will watch for consistent execution on this higher-margin path before closing that gap entirely.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.