Orient Ceratech (ORIENTCER) Q2 FY27 Profit Falls 10% as Costs Outpace 12% Revenue Growth
The specialty ceramics maker saw a sharp sequential drop in profitability as expenses surged, highlighting margin pressures despite strong top-line growth.
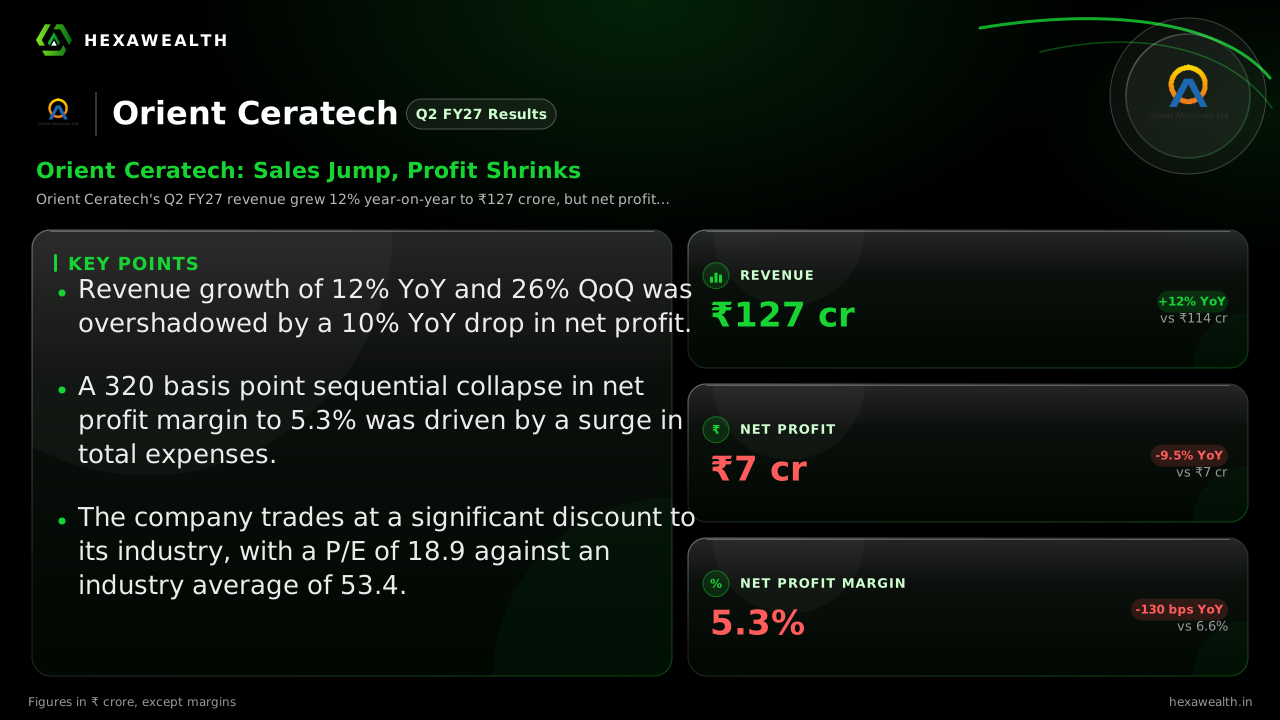
Orient Ceratech's Q2 FY27 revenue grew 12% year-on-year to ₹127 crore, but net profit fell 10% to ₹6.8 crore. A 35% sequential surge in total expenses squeezed margins, revealing cost pressures in the refractories sector.
For a specialty ceramics maker, a quarter of strong sales growth should translate to better profits. Orient Ceratech's September quarter saw the opposite, with revenue rising but profitability falling as costs surged faster than the top line.
The numbers tell a story of divergence. Consolidated revenue for Q2 FY27 was ₹126.88 crore, up 11.7% from a year ago and a sharp 26.1% from the previous quarter. Net profit, however, fell 9.5% year-on-year to ₹6.78 crore and dropped 20.9% sequentially.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 126.88 | 100.65 |
| Profit (₹ Cr) | 6.78 | 8.57 |
| Net Profit Margin | 5.3% | 8.5% |
Where the profit went
Profit before tax fell 15% year-on-year and 38% quarter-on-quarter. The squeeze came from a 35% sequential jump in total expenses, outpacing the revenue surge. Interest costs rose 45% year-on-year, while employee expenses climbed 14%.
This cost inflation aligns with broader sector pressures. An IndexBox report notes raw material and energy costs for refractories have risen 8-12% since 2022, compressing margins for producers.
The market's muted read
No verified analyst estimates were publicly available for the quarter, according to a Univest preview. The stock showed little reaction, closing at ₹38.95 on November 4, near its price a year earlier. Institutional holdings have remained steady, with FII ownership around 13.4%.
Management did not provide formal guidance in the results statement, reports Arthneeti. The focus now is on whether recent capacity investments can offset these cost pressures as demand holds.
Key Points
- Revenue growth of 12% YoY and 26% QoQ was overshadowed by a 10% YoY drop in net profit.
- A 320 basis point sequential collapse in net profit margin to 5.3% was driven by a surge in total expenses.
- The company trades at a significant discount to its industry, with a P/E of 18.9 against an industry average of 53.4.
Hexa Perspective
The quarter reveals a business winning on volume but losing on pricing power. With net profit margin now below its trailing twelve-month average of 6.1%, the cost surge is more than a blip.
The pressure from energy and raw material costs, highlighted by sector reports, is a structural headwind. For profitability to recover, Orient Ceratech must either pass these costs through or find operational efficiencies from its recent ₹50 crore capacity expansion.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.