Andhra Petrochemicals (ANDHRAPET) Q2 FY27 Swings to Profit After a Quarter of Shutdown
The company posted a ₹2.42 crore profit in Q2 FY27, a sharp recovery from a loss, as its plant restarted after a five-month shutdown.
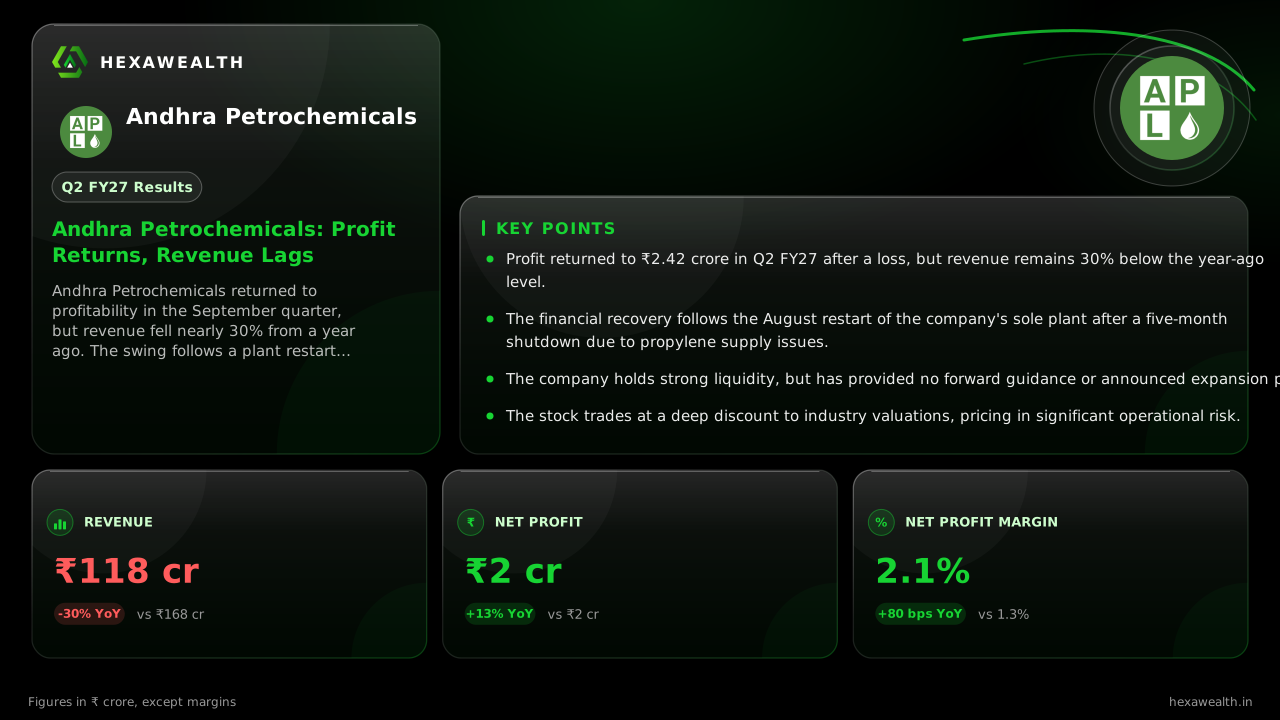
Andhra Petrochemicals returned to profitability in the September quarter, but revenue fell nearly 30% from a year ago. The swing follows a plant restart after a severe supply disruption.
For Andhra Petrochemicals, the September quarter was about restarting its single oxo-alcohols plant after a five-month shutdown. The result is a financial snapshot of recovery, not yet of health. Profit returned, but revenue remained well below last year's level, highlighting the fragility of its supply chain.
The numbers show a business emerging from a standstill. Revenue of ₹117.6 crore is a massive 735% jump from the disastrous June quarter, but it is still 30% lower than the same period last year. Net profit landed at ₹2.42 crore, swinging from a ₹3.25 crore loss last quarter and up 13% year-on-year.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 117.61 | 14.09 |
| Profit (₹ Cr) | 2.42 | -3.25 |
| PAT Margin (%) | 2.1 | -23.1 |
The profit recovery is more about cost control than sales momentum. According to a report from StockWatch, the plant was shut from mid-March to early August after its sole supplier, HPCL, suspended propylene supply. With the plant idle, the cost of materials consumed fell sharply, helping margins recover from deeply negative territory.
The Shutdown That Defined Two Quarters
The story of this quarter is inextricably linked to the last. The Q1 loss of ₹3.25 crore came from revenue of just ₹14 crore, generated entirely by liquidating finished-goods inventory. The company, as noted by StockWatch, rejected HPCL's offer for partial supply in May as uneconomical, extending the shutdown. Operations only restarted on August 5, leaving just under two months of production in Q2.
This explains the stark divergence between quarterly and half-year performance. While Q2 showed a profit, the first half of FY27 still recorded a net loss of ₹8.32 lakh. The business remains vulnerable to a single raw material supplier and volatile petrochemical pricing.
A Cautious Path Forward
Management has not provided formal guidance, but the outlook hinges on propylene supply stability and oxo-alcohol pricing. Research from ScanX notes the company maintains a strong liquidity position, with bank balances over ₹261 crore, providing a buffer. However, with no announced capacity expansion or strategic initiatives, growth appears dependent on market conditions.
The stock, down 23% over the past year, trades at a significant discount to the industry average. Its price-to-earnings ratio of 11.4 is 68% below the industry PE of 35.8, reflecting the market's skepticism about sustainable earnings.
Key Points
- Profit returned to ₹2.42 crore in Q2 FY27 after a loss, but revenue remains 30% below the year-ago level.
- The financial recovery follows the August restart of the company's sole plant after a five-month shutdown due to propylene supply issues.
- The company holds strong liquidity, but has provided no forward guidance or announced expansion plans.
- The stock trades at a deep discount to industry valuations, pricing in significant operational risk.
Hexa Perspective
The quarter confirms Andhra Petrochemicals is operationally viable when its plant runs, but not that it is resilient. Profitability is a function of a low base and controlled costs during restart, not underlying demand strength. The real test is whether it can secure reliable, economical propylene supply and improve upon the still-soft revenue run-rate. Until it demonstrates that, or diversifies its feedstock, the earnings path will remain as volatile as the petrochemical cycle itself.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.