CESC Profit Dips as Higher Costs Squeeze Margins in Q2 FY27
CESC's September quarter revenue grew 6.5% year-on-year, but net profit slipped 1.6% as rising fuel and employee costs pressured operating margins.
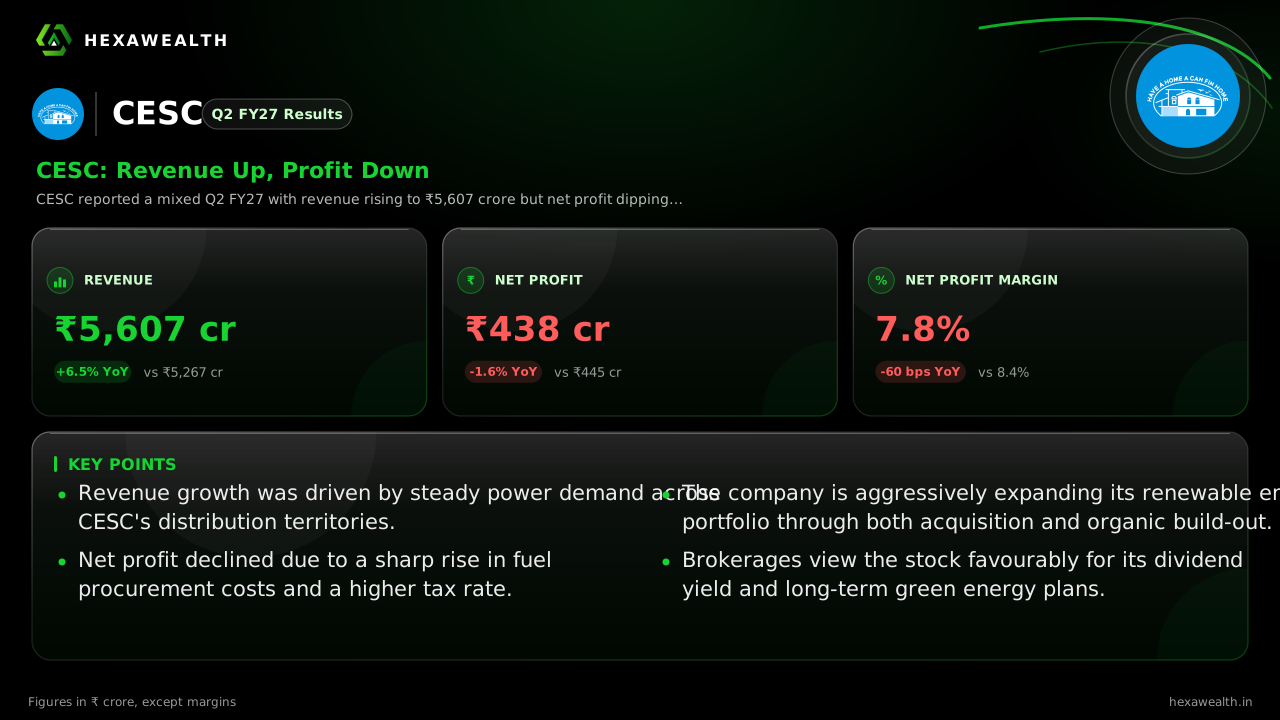
CESC reported a mixed Q2 FY27 with revenue rising to ₹5,607 crore but net profit dipping to ₹438 crore. The decline was driven by a sharp increase in energy purchase costs, which compressed margins despite steady demand.
For a utility like CESC, the quarter is a test of its ability to pass on rising input costs. The September quarter showed it is still a work in progress. Revenue grew on steady power demand, but profit slipped as costs rose faster.
Consolidated revenue reached ₹5,607 crore, up 6.5% from a year ago. Net profit, however, edged down 1.6% to ₹438 crore. The net profit margin contracted by 60 basis points to 7.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 5,607YoY +6.5% | 5,485 | 5,267 |
| Profit (₹ Cr) | 438YoY -1.6% | 419 | 445 |
| Net Profit Margin (%) | 7.8YoY -7.1% | 7.6 | 8.4 |
Why the bottom line shrank
Higher operational costs were the primary culprit. According to a report by scanx.trade, the cost of energy purchased surged 14% year-on-year to ₹2,566 crore. Employee expenses also rose, compressing operating profitability.
This pressure was evident in the EBITDA margin, which sahi.com noted contracted 161 basis points to 18.53%. A higher effective tax rate of 25.3%, up from 21.3% a year ago, further weighed on the bottom line.
The buffer and the long game
A surge in other income, which more than doubled year-on-year to ₹178 crore, provided a partial offset. This helped pre-tax profit grow 3.7%. The company's strategic focus, however, is firmly on its renewable energy pivot.
CESC is building a massive green portfolio. Its subsidiary Purvah Green is acquiring 1,411 MW of operational solar assets from ReNew, as noted by multibagg.ai. The company aims for 3.2 GW of renewable capacity by FY29 and 10 GW by 2032.
Market reads the mix
Analyst sentiment reflects this transition story. PL Capital maintained a 'Buy' rating with a target of ₹204 in late October, citing stable earnings from distribution and the growth runway in renewables. The stock trades at a significant discount to the industry PE.
Key Points
- Revenue growth was driven by steady power demand across CESC's distribution territories.
- Net profit declined due to a sharp rise in fuel procurement costs and a higher tax rate.
- The company is aggressively expanding its renewable energy portfolio through both acquisition and organic build-out.
- Brokerages view the stock favourably for its dividend yield and long-term green energy plans.
Hexa Perspective
The quarter underscores the classic utility squeeze: demand is firm, but input cost volatility directly hits margins before tariffs can adjust. The path to sustained earnings growth now runs through two channels.
First, the success of its renewable build-out, where long-term PPAs can lock in more stable margins. Second, operational improvements in newer distribution franchises to reduce losses. Until those engines fire, quarterly profits will remain sensitive to coal prices and regulatory timing.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.