Navneet Education (NAVNETEDUL) Q2 FY27's Profit Slips Despite Strong Revenue Growth
Navneet Education's Q2 FY27 revenue jumped 31% year-on-year, but the company slipped into a small consolidated loss as subsidiary performance weighed.
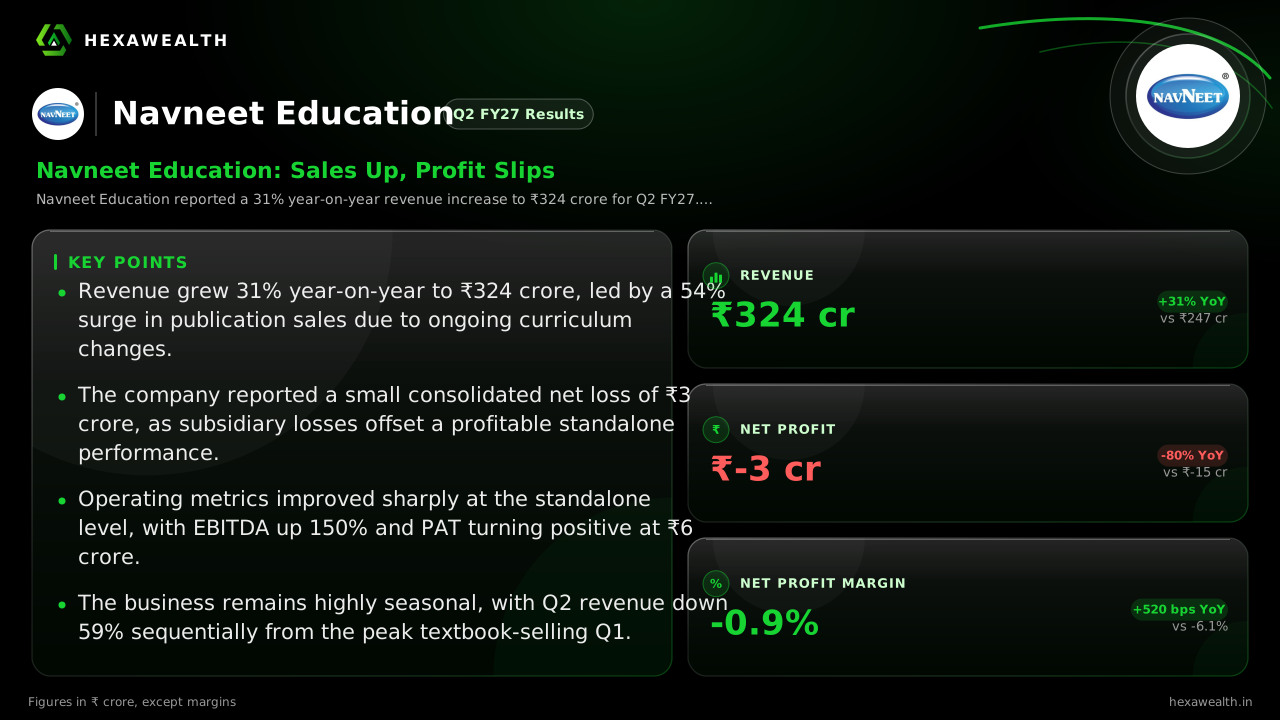
Navneet Education reported a 31% year-on-year revenue increase to ₹324 crore for Q2 FY27. However, the company posted a consolidated net loss of ₹3 crore, highlighting a divergence between standalone operational improvement and group-level profitability.
For Navneet Education, the September quarter is the quiet season after the textbook rush of June. This year, the off-cycle showed a clear operational recovery from a weak base, but the consolidated picture was pulled down by its subsidiaries. Revenue grew 31% year-on-year, yet the company posted a small loss.
The numbers tell a story of two halves. Revenue rose to ₹324 crore from ₹247 crore a year ago. But profit slipped to a loss of ₹3 crore, an 80% improvement from last year's larger loss of ₹15 crore. Sequentially, the drop from a ₹141 crore profit in Q1 is stark, reflecting the business's extreme seasonality.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 324 | 788 |
| Profit (₹ Cr) | -3 | 141 |
| Net Profit Margin (%) | -0.9 | 17.9 |
The Standalone Recovery Story
The core business performed well. According to the company's investor presentation, standalone revenue grew 32% to ₹324 crore. The publication segment surged 54% to ₹140 crore, driven by a curriculum change cycle in key states like Maharashtra and Gujarat. Domestic stationery also grew a robust 34%.
This translated to a sharp improvement in operating metrics. Standalone EBITDA jumped 150% year-on-year to ₹20 crore, as reported by Arthneeti. The parent company's standalone profit after tax turned positive at ₹6 crore, a reversal from a ₹6 crore loss last year.
Why the Group Still Lost Money
The consolidated loss of ₹3 crore points to a persistent drag from subsidiaries. Reports from ScanX.trade and others note that losses in entities like Navneet Futuretech Limited offset the parent's operational recovery. This divergence between standalone and consolidated results remains a key overhang.
Management's outlook, per the investor presentation, is cautiously optimistic. The curriculum change cycle is expected to support publication growth for the next two financial years. Domestic stationery growth should continue, while exports await a U-shaped recovery dependent on global demand.
Key Points
- Revenue grew 31% year-on-year to ₹324 crore, led by a 54% surge in publication sales due to ongoing curriculum changes.
- The company reported a small consolidated net loss of ₹3 crore, as subsidiary losses offset a profitable standalone performance.
- Operating metrics improved sharply at the standalone level, with EBITDA up 150% and PAT turning positive at ₹6 crore.
- The business remains highly seasonal, with Q2 revenue down 59% sequentially from the peak textbook-selling Q1.
Hexa Perspective
The quarter confirms Navneet's operational turnaround at the core is underway, evidenced by strong standalone margins. However, the consolidated loss underscores that the cleanup of subsidiary performance is incomplete and critical for overall profitability.
Investors are weighing a robust domestic education cycle against export headwinds and internal drags. The stock's valuation, at a significant discount to the industry average, reflects this mixed bag of a recovering core and unresolved group-level challenges.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.