Stove Kraft (STOVEKRAFT) Q2 FY27 Profit Jumps 70% as Festive Demand Fuels a Margin Leap
The kitchen appliance maker posted its second-highest quarterly profit ever, with margins expanding sharply on the back of a strong festive season.
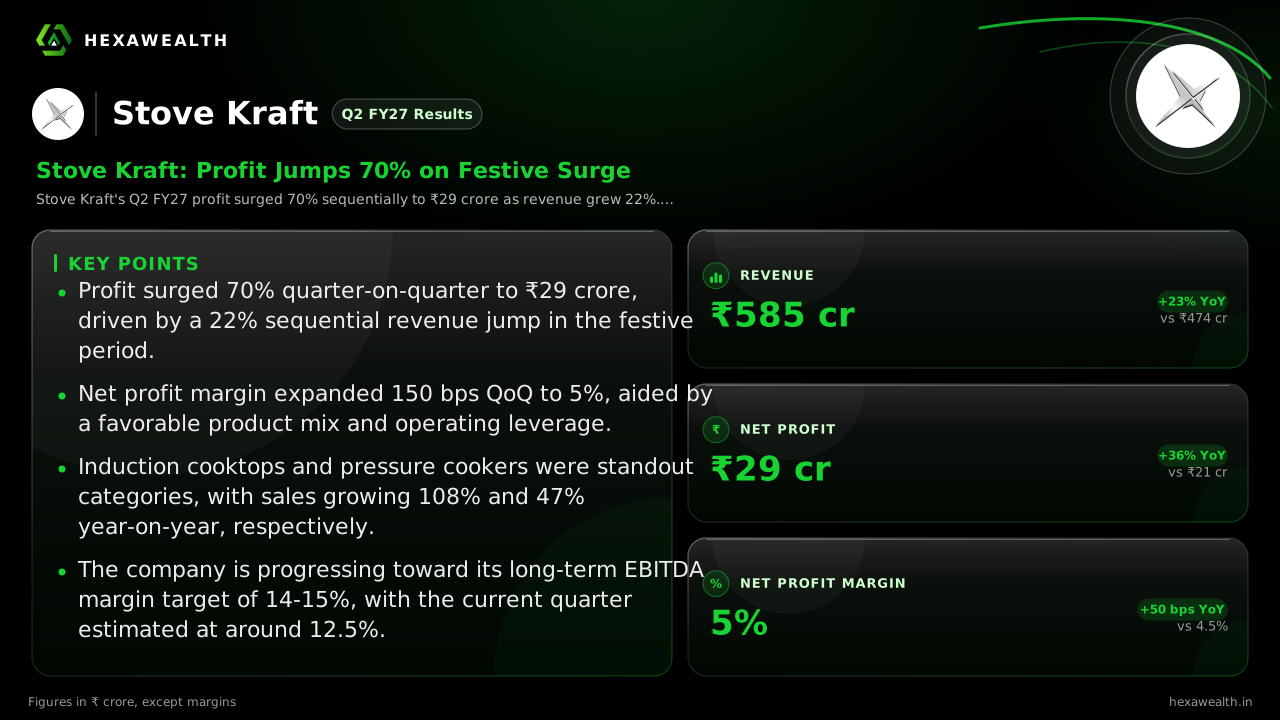
Stove Kraft's Q2 FY27 profit surged 70% sequentially to ₹29 crore as revenue grew 22%. The festive quarter delivered robust operating leverage, pushing net margins to 5%, a 150 bps improvement from the previous quarter.
For a kitchen appliance maker, the festive quarter is the ultimate test of demand and execution. Stove Kraft passed with its second-highest quarterly profit in six quarters, as revenue jumped 23% year-on-year to ₹585 crore. The real story, however, is that profit grew even faster, signaling a meaningful improvement in profitability.
The numbers show a clear seasonal acceleration. Profit after tax soared 70% from the June quarter to ₹29 crore, while revenue climbed 22%. This pushed the net profit margin to 5%, a sharp 150 basis point improvement sequentially and 50 bps higher than a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 584.67 | 480.58 |
| Profit (₹ Cr) | 28.98 | 17.06 |
| Net Margin (%) | 5.0 | 3.5 |
The Festive Engine Behind the Growth
Growth was broad-based but led by specific high-margin categories. According to the company's investor presentation, induction cooktop sales more than doubled year-on-year, while pressure cookers grew 47%. Retail and general trade channels expanded by 57% and 49%, respectively, as reported by FilingReader.
This product mix and channel strength translated into operating leverage. Gross margin widened to about 39.6%, meeting management's target of at least a 1% year-on-year improvement. The gain, noted by Stockwatch, helped absorb a 26% quarterly rise in interest costs while still delivering a higher bottom line.
A Margin Target Within Sight
Management's medium-term goal is an EBITDA margin of 14-15%, up from an 11% baseline. This quarter's estimated EBITDA margin of around 12.5%, as per Stockwatch, marks another step toward that target. The path relies on continued premiumization and the ramp-up of in-house manufacturing.
A key initiative is a new joint venture in China to manufacture triply cookware components, aimed at securing supply and controlling costs. Commercial production is expected by December 2026, according to an earlier earnings call summary.
The Working Capital Trade-Off
The strong sales came with a buildup in inventory and receivables ahead of the festive season. One analysis by Stockwatch flagged that working capital has unwound significantly since March, which will test cash conversion in the second half as this stock sells through.
Nevertheless, operational efficiencies have improved net working capital days to 32 from 51 a year ago, as per FilingReader. This suggests the company is managing the seasonal surge more effectively than in the past.
Key Points
- Profit surged 70% quarter-on-quarter to ₹29 crore, driven by a 22% sequential revenue jump in the festive period.
- Net profit margin expanded 150 bps QoQ to 5%, aided by a favorable product mix and operating leverage.
- Induction cooktops and pressure cookers were standout categories, with sales growing 108% and 47% year-on-year, respectively.
- The company is progressing toward its long-term EBITDA margin target of 14-15%, with the current quarter estimated at around 12.5%.
Hexa Perspective
The quarter demonstrates Stove Kraft's ability to capitalize on peak seasonal demand and convert it into superior profitability. The margin expansion is encouraging and aligns with management's stated trajectory.
The sustainability of this performance hinges on two factors: maintaining the sales momentum beyond the festive quarter and successfully managing the working capital buildup into the second half. Investors are also weighing the execution of the China JV, which aims to provide a structural cost advantage but carries integration risk. The stock's 28% one-year return reflects optimism, but the coming quarters will show if this festive spark can light a longer-lasting fire.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.