Shanti Educational Initiatives (SEIL) Q2 FY27 Profit Drops 62% as Core Business Weakens
The education provider's Q2 FY27 profit fell sharply as a steep revenue decline from its core operations overwhelmed a surge in other income.
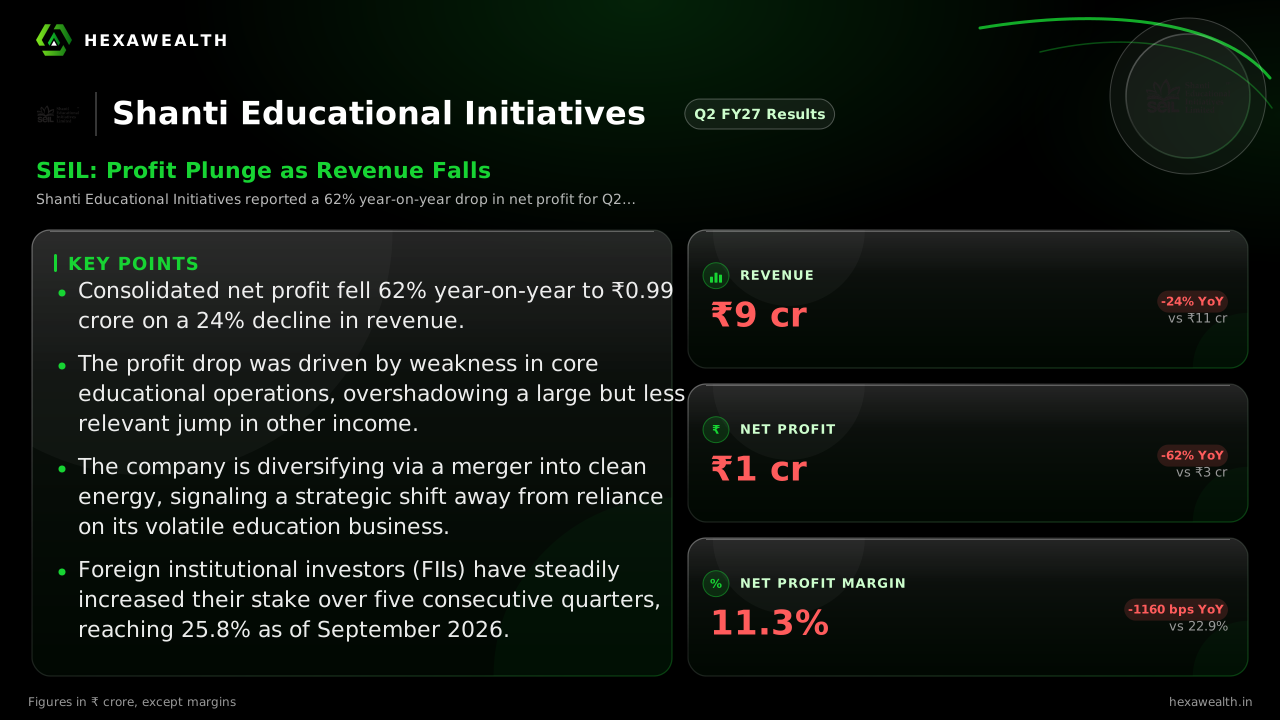
Shanti Educational Initiatives reported a 62% year-on-year drop in net profit for Q2 FY27. The decline was driven by a 24% fall in revenue from its core education business, highlighting operational weakness.
For Shanti Educational Initiatives, a quarter of sharp revenue decline has exposed the volatility in its core education business. The company's consolidated net profit fell 62% year-on-year to ₹0.99 crore, a drop far steeper than the 24% slide in revenue, as profitability collapsed.
The numbers show a business under pressure from both yearly and quarterly perspectives. Revenue of ₹8.73 crore was down 46% from the previous quarter, while profit fell 65% sequentially. The net profit margin compressed by 600 basis points from Q1 FY27 to 11.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 8.73YoY -24% | 16.30 | 11.42 |
| Profit (₹ Cr) | 0.99YoY -62% | 2.82 | 2.62 |
| Net Profit Margin (%) | 11.3YoY -51% | 17.3 | 22.9 |
Why the core business stumbled
Research from scanx.trade points to a sharp contraction in standalone operational revenue as the primary driver. This suggests weakness in its main educational services, which include early-learning, K-12 support, and preschool franchising. The slump overshadowed a massive, but largely immaterial, quarter-on-quarter surge in other income.
That other income jumped over 9,000% sequentially to ₹2.64 crore, according to the payload. However, scanx.trade notes that on a standalone basis, other income remained nearly flat year-on-year. This indicates the core business weakness, not a drop in ancillary earnings, was the real story behind the profit plunge.
A strategic pivot amid stagnation
Management is not waiting for a pure education-led recovery. The company is pursuing a strategic merger with GREW Energy Private Limited, as noted in a StockFin.ai report. This move aims to diversify into clean energy, positioning it as a growth avenue beyond what appears to be a stagnant core segment.
The market's read on this transition is mixed. While the stock has delivered strong long-term returns, its valuation sits at a significant premium. With a P/E of 419 against an industry average of 106.5, much future success is already priced in.
Key Points
- Consolidated net profit fell 62% year-on-year to ₹0.99 crore on a 24% decline in revenue.
- The profit drop was driven by weakness in core educational operations, overshadowing a large but less relevant jump in other income.
- The company is diversifying via a merger into clean energy, signaling a strategic shift away from reliance on its volatile education business.
- Foreign institutional investors (FIIs) have steadily increased their stake over five consecutive quarters, reaching 25.8% as of September 2026.
Hexa Perspective
The quarter reveals a business whose educational services lack revenue durability, leading to severe quarterly swings. The planned energy sector pivot is a clear admission that management sees limited near-term growth in its core market.
Investors are thus weighing two narratives: the current reality of a struggling, volatile education company, and the future promise of a diversified entity. The steep valuation premium suggests the market is betting heavily on the latter story unfolding successfully, leaving little room for error.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.