(RUSTOMJEE) Q2 FY27 Rustomjee Profit Jumps 10-Fold on JV Gains, Margins Expand
Keystone Realtors reported a 10-fold surge in Q2 FY27 net profit to ₹101 crore, driven by profit share from joint ventures and improved operational efficiency.
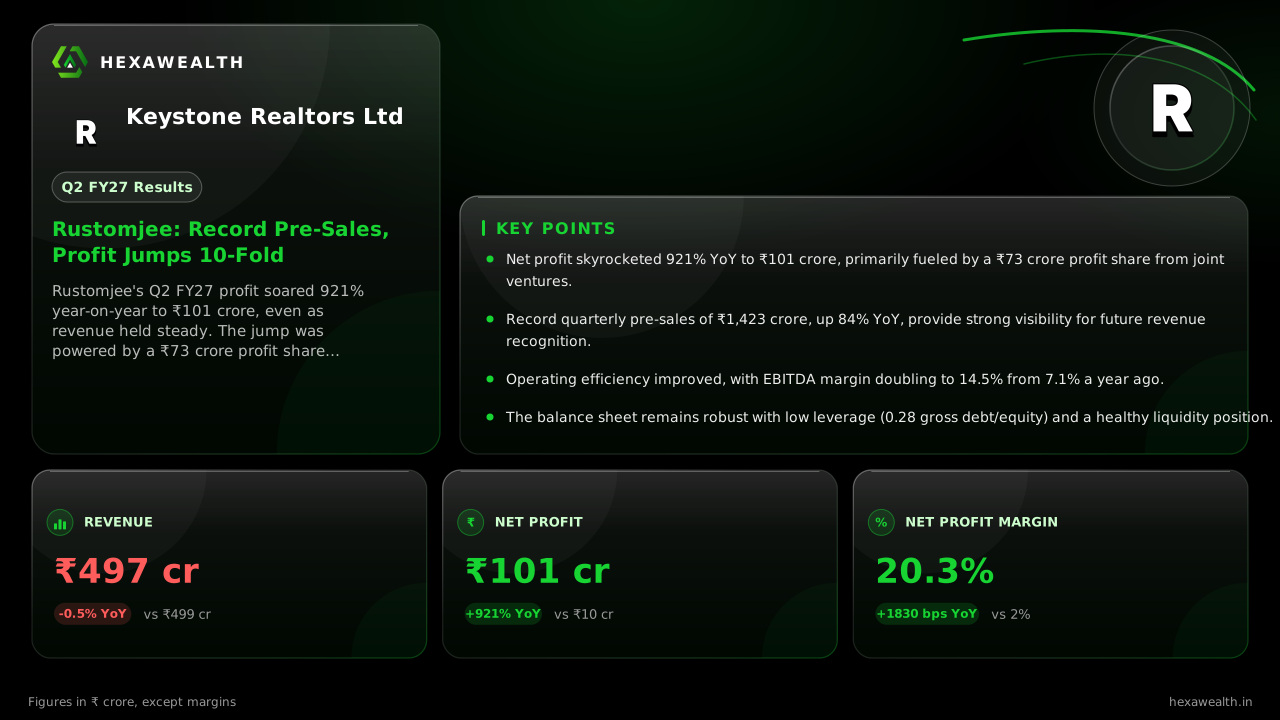
Rustomjee's Q2 FY27 profit soared 921% year-on-year to ₹101 crore, even as revenue held steady. The jump was powered by a ₹73 crore profit share from joint ventures and a sharp expansion in operating margins.
For Keystone Realtors, known as Rustomjee, this quarter was a story of two different financial statements. The headline revenue of ₹497 crore was flat compared to last year, but the bottom line told a different tale entirely.
The net profit surged tenfold to ₹101 crore, marking a 921% year-on-year explosion. This pushed the net profit margin to 20.3%, a massive 1,830 basis point leap from the 2.0% seen a year ago. Sequentially, profit nearly doubled from the June quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 497.0 | 470.3 |
| Profit (₹ Cr) | 101.0 | 52.4 |
| Net Profit Margin (%) | 20.3 | 11.1 |
The Engine Behind the Profit Surge
The staggering profit growth had two clear drivers. First, a high share of profit from associates and joint ventures contributed ₹73.24 crore, as reported by The Economic Times. This accounted for nearly two-thirds of the pre-tax profit.
Second, operational efficiency improved sharply. EBITDA, a measure of operating profit, doubled year-on-year to ₹74 crore. The EBITDA margin expanded to 14.5% from 7.1% a year ago, according to the company's earnings call.
A Record Pipeline Meets Strong Demand
The company’s future revenue engine is firing. It achieved its highest-ever quarterly pre-sales of ₹1,423 crore, an 84% jump from last year. Management, on the AlphaStreet earnings call, reiterated its full-year pre-sales guidance of ₹5,000 crore, with 41% already achieved in the first half.
This demand is concentrated in luxury and super-premium segments, aligning with a broader market trend. A Knight Frank India report noted that Mumbai’s ultra-luxury home sales surged 35-40% in the first nine months of 2026.
The Balance Sheet and the Road Ahead
Financing this growth is not a strain. The company maintains a conservative balance sheet with a gross debt-to-equity ratio of 0.28:1 and a net debt-to-equity ratio of just 0.04:1. It holds a dual AA- credit rating with a stable outlook.
Management expects collections and operating cash flow to improve significantly in the second half. They guided for full-year operating cash flow between ₹700-800 crore, up from ₹193 crore in the first half.
Key Points
- Net profit skyrocketed 921% YoY to ₹101 crore, primarily fueled by a ₹73 crore profit share from joint ventures.
- Record quarterly pre-sales of ₹1,423 crore, up 84% YoY, provide strong visibility for future revenue recognition.
- Operating efficiency improved, with EBITDA margin doubling to 14.5% from 7.1% a year ago.
- The balance sheet remains robust with low leverage (0.28 gross debt/equity) and a healthy liquidity position.
Hexa Perspective
The quarter reveals a company in transition. The headline profit is impressive but heavily reliant on equity-accounted income from joint ventures, a model that adds scale but can obscure standalone performance. The core business is showing clear strength, with record pre-sales and expanding margins.
The critical test is execution. Converting the massive ₹1,423 crore pre-sales into recognised revenue and cash flow in the coming quarters will determine if this profitability is sustainable. With a strong project pipeline and a disciplined balance sheet, Rustomjee is well-positioned, but the market will watch for the translation of sales into cash.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.