SMS Pharmaceuticals (SMSPHARMA) Q2 FY27 Profit Doubles as New API Volumes Drive Record Quarter
The API maker's profit nearly doubled sequentially as strong demand for anti-inflammatory and ARV products powered a 53% revenue jump.
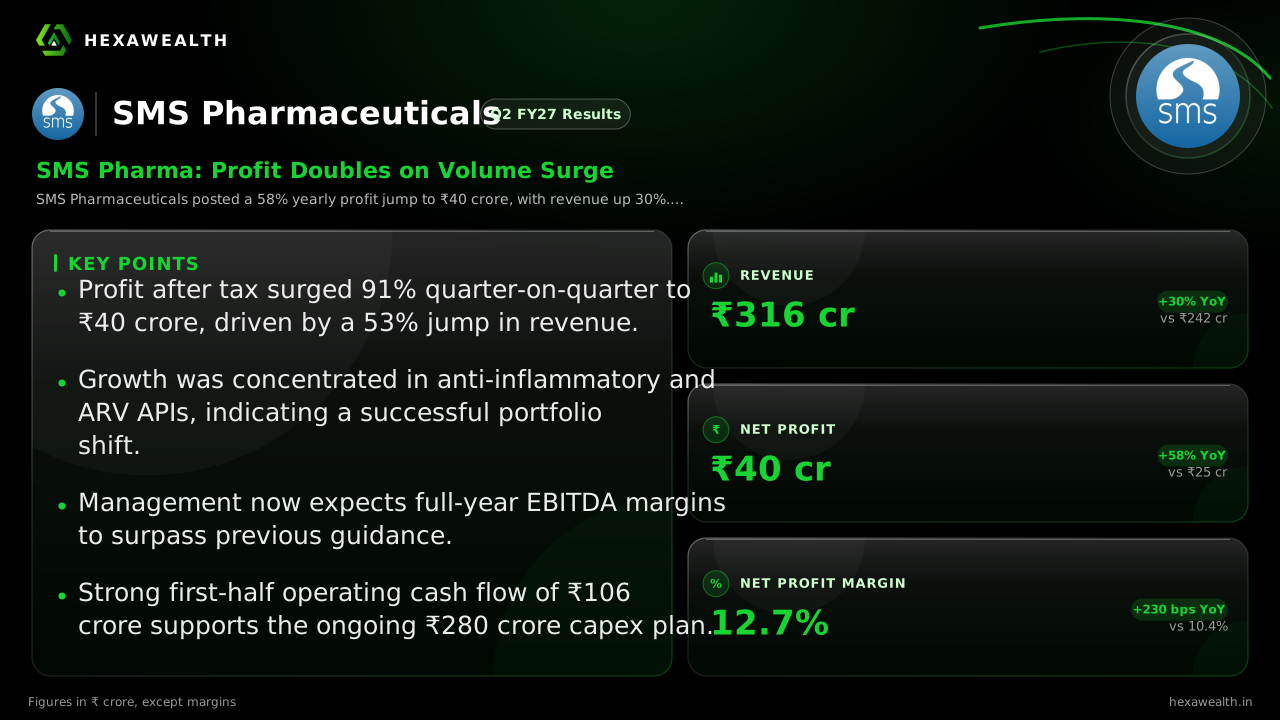
SMS Pharmaceuticals posted a 58% yearly profit jump to ₹40 crore, with revenue up 30%. The surge was driven by higher volumes and better pricing in key therapeutic segments, leading to margin expansion.
For SMS Pharmaceuticals, the September quarter was about translating a strategic product shift into a sharp earnings rebound. After a soft Q1, the API specialist delivered its highest-ever quarterly revenue and profit, driven by a surge in high-value molecules.
The numbers show a powerful sequential recovery. Revenue jumped 53% to ₹316 crore, while net profit nearly doubled, rising 91% to ₹40 crore. This pushed the net profit margin to 12.7%, a 260 basis-point improvement from the previous quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 316.0 | 207.0 |
| Profit (₹ Cr) | 40.0 | 20.9 |
| Net Profit Margin (%) | 12.7 | 10.1 |
A Portfolio Tilt Pays Off
The growth was led by anti-inflammatory and anti-retroviral (ARV) APIs, according to the company's investor presentation. This shift away from a declining anti-diabetic segment created a more favorable product mix. Higher volumes and better price realization in these key therapeutic areas were the primary drivers.
Margins expanded even as total expenses rose 46% sequentially, a sign of strong operating leverage. The company's investor presentation, cited by Multibagg.ai, noted that FY27 EBITDA margins are now expected to exceed earlier guidance.
Funding Growth While Spending
The strong operational cash flow of ₹106 crore for the first half, as reported by FlashFinance News, comfortably funds the ongoing ₹280 crore capital expenditure plan. This investment is largely brownfield, aimed at expanding capacity for existing APIs and building a new pipeline.
With net debt stable and a healthy interest cover of 6.0, the balance sheet supports this growth phase. The stock has already rallied 84% over the past year, reflecting high expectations.
Key Points
- Profit after tax surged 91% quarter-on-quarter to ₹40 crore, driven by a 53% jump in revenue.
- Growth was concentrated in anti-inflammatory and ARV APIs, indicating a successful portfolio shift.
- Management now expects full-year EBITDA margins to surpass previous guidance.
- Strong first-half operating cash flow of ₹106 crore supports the ongoing ₹280 crore capex plan.
Hexa Perspective
The quarter demonstrates SMS Pharma's ability to capitalize on specific API demand pockets, moving beyond broad sector trends. The margin expansion, while aided by a favorable mix, must now be defended as new capacity comes online.
The key test is whether the current volume surge in anti-inflammatory and ARV products is sustainable or a cyclical peak. With the stock trading at a slight discount to the industry PE, the market is pricing in execution but remains wary of API pricing volatility. The next few quarters will show if this rebound is the start of a new growth cycle or a high point in the current one.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.