Ellenbarrie (ELLEN) Q2 FY27 Profit Stalls as Costs Swallow Revenue Growth
Ellenbarrie Industrial Gases posted strong 28% revenue growth in Q2 FY27, but a sharp rise in expenses and a high year-ago base left profit slightly lower.
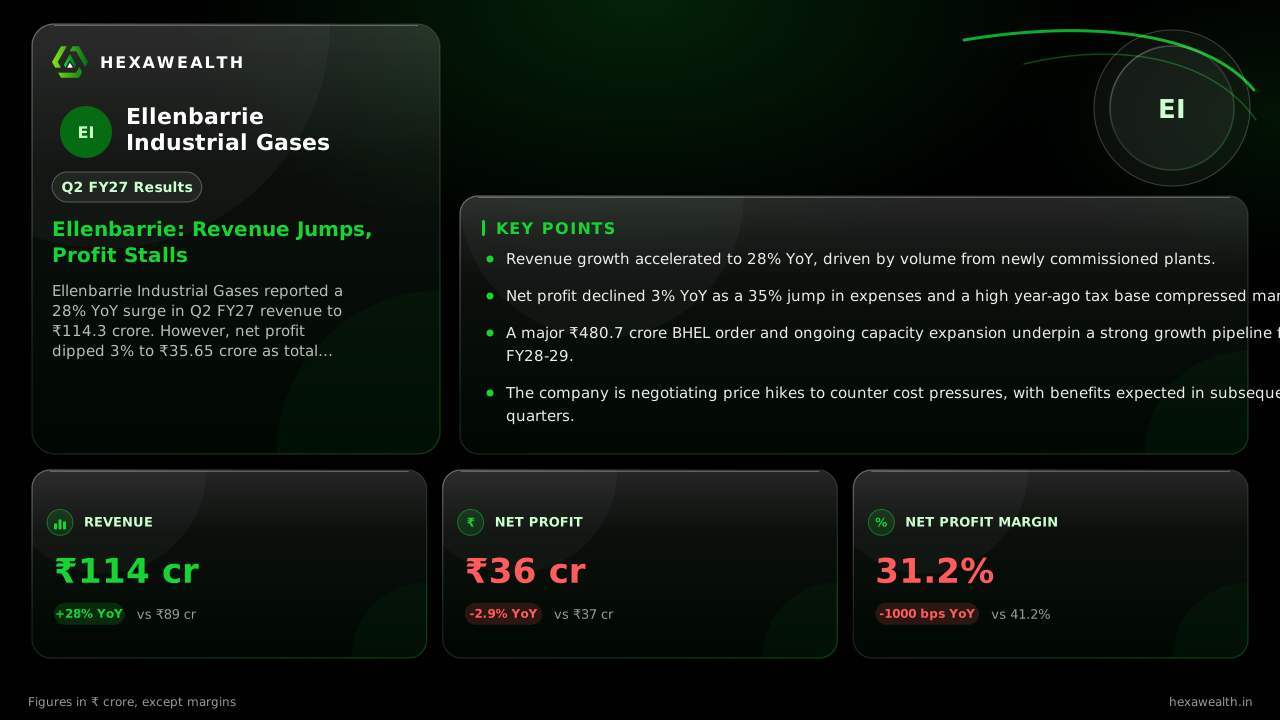
Ellenbarrie Industrial Gases reported a 28% YoY surge in Q2 FY27 revenue to ₹114.3 crore. However, net profit dipped 3% to ₹35.65 crore as total expenses jumped 35%, compressing the net profit margin by 1000 basis points from the year-ago quarter.
For Ellenbarrie Industrial Gases, the September quarter was about new capacity meeting old costs. The company's expanding merchant and onsite plants delivered strong volume growth, but a surge in expenses and a high year-ago profit base meant the bottom line barely moved.
The numbers show the tension. Revenue climbed 28% year-on-year to ₹114.3 crore, and rose 16% from the previous quarter. Yet net profit slipped 3% from a year ago to ₹35.65 crore, even as it inched up 2% sequentially. The net profit margin fell to 31.2%, down 1000 basis points from Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 114.32YoY +28% | 98.72 | 89.17 |
| Profit (₹ Cr) | 35.65YoY -2.9% | 34.96 | 36.72 |
| Net Profit Margin | 31.2%YoY -24% | 35.4% | 41.2% |
Why the profit didn't follow sales
Two powerful forces squeezed profitability. First, total expenses surged 35% year-on-year, driven by higher transport costs and salary hike arrears, according to the company's investor presentation. Interest expense more than doubled, reflecting the cost of funding its aggressive expansion.
Second, the year-ago quarter was flattered by a one-off deferred tax credit of ₹4.5 crore, as noted by Scanx.trade. Without that benefit, the tax expense this quarter rose sharply, contributing to the profit decline. The core gases segment margin improved to 39%, but this was offset by a loss in the smaller project engineering division.
The growth pipeline is filling up
The pressure on margins comes as the company is building for the future. It commissioned a new 320 TPD onsite plant in East India during the quarter, which is expected to contribute fully from Q3. Ramp-up at the Kurnool and Uluberia-II merchant plants continues.
A major highlight was winning a ₹480.7 crore turnkey order from BHEL for a 1,200 TPD air separation unit. The project, part of India's Coal Gasification Mission, will be executed over FY28 and FY29, adding to the project engineering order book.
The market's read on the trade-off
The stock closed at ₹347.55 on November 4, gaining nearly 7% on the results day. This suggests the market focused on the strong top-line momentum and the significant BHEL order win. Analysts had recently raised their revenue forecast for FY27 to ₹512 crore, according to a Simply Wall St report.
Management, in its presentation, expects core gas performance to strengthen in the second half of FY27 as new plants ramp up. The company is also negotiating price increases to offset higher transport costs, which should help margins in the coming quarters.
Key Points
- Revenue growth accelerated to 28% YoY, driven by volume from newly commissioned plants.
- Net profit declined 3% YoY as a 35% jump in expenses and a high year-ago tax base compressed margins.
- A major ₹480.7 crore BHEL order and ongoing capacity expansion underpin a strong growth pipeline for FY28-29.
- The company is negotiating price hikes to counter cost pressures, with benefits expected in subsequent quarters.
Hexa Perspective
Ellenbarrie is in a classic expansion phase where sales growth precedes profit leverage. The margin squeeze is a near-term cost of scaling, evident in rising interest and operating expenses. The sustainability of its 31% net margin now hinges on successful price pass-through and the full ramp-up of its new, efficient plants.
The BHEL order de-risks the project engineering segment and provides long-term revenue visibility. For investors, the quarter presents a trade-off: robust volume-led growth today against the promise of better profitability tomorrow, provided the company navigates the current cost inflation.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.