Sanathan Textiles (SANATHAN) Q2 FY27 Profit Triples as Punjab Plant Drives 120% Revenue Surge
The yarn manufacturer's consolidated profit soared 204% year-on-year to ₹61 crore, powered by the full-scale ramp-up of its new integrated facility in Punjab.
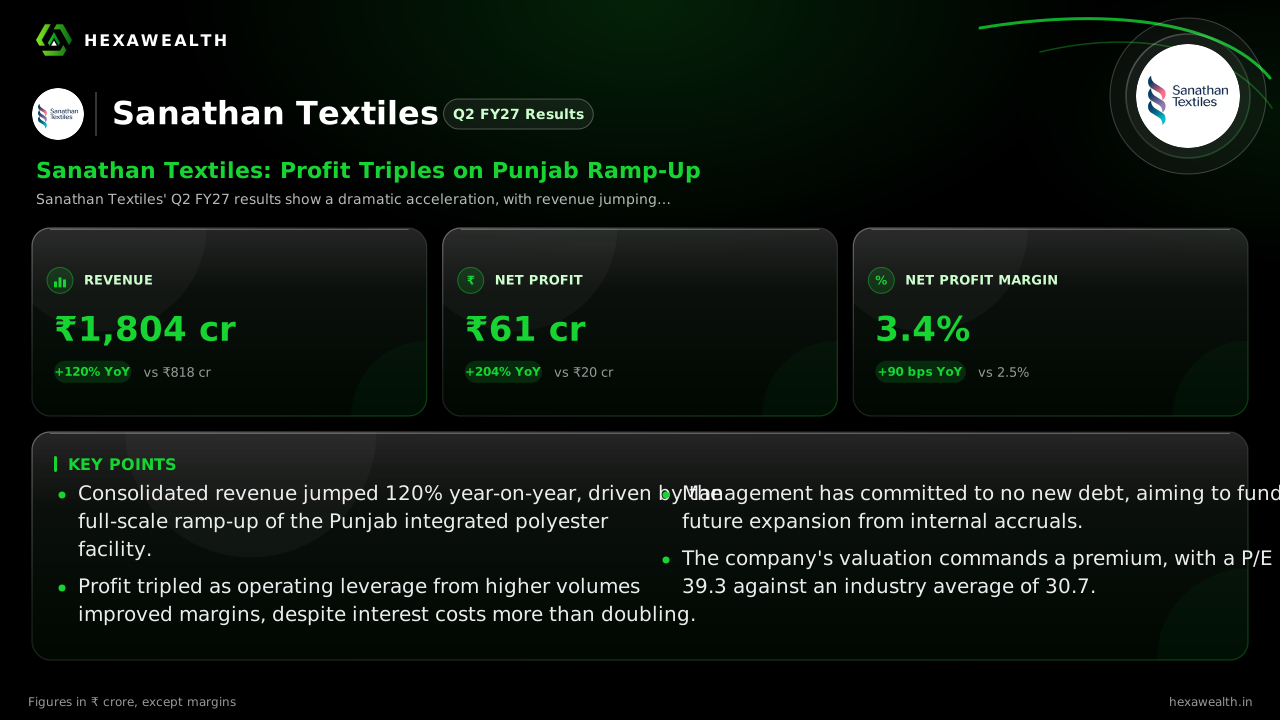
Sanathan Textiles' Q2 FY27 results show a dramatic acceleration, with revenue jumping 120% and profit tripling. The surge is driven by the Punjab facility's volume ramp-up, though high debt costs remain a key watchpoint.
For Sanathan Textiles, the September quarter was the payoff from a big bet. After navigating raw material volatility, the company's new Punjab facility hit its stride, transforming the group's scale and delivering a profit surge that more than tripled from a year ago.
The numbers tell a story of dramatic acceleration. Consolidated revenue reached ₹1,804 crore, up 120% from last year and 35% from the prior quarter. Profit after tax soared 204% year-on-year to ₹61.2 crore, with the net profit margin improving to 3.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,803.97YoY +121% | 1,334.74 | 817.99 |
| Profit (₹ Cr) | 61.23YoY +204% | 23.82 | 20.12 |
| Net Profit Margin | 3.4%YoY +36% | 1.8% | 2.5% |
The Engine Behind the Surge
The leap was powered by the Punjab facility, which Chairman Paresh Dattani said is now contributing meaningfully to volumes. According to the company's investor presentation, consolidated production more than doubled year-on-year. Higher utilisation improved fixed-cost absorption, lifting consolidated EBITDA margin by 90 basis points to 8.6%, as reported by Multibagg.ai.
This growth overshadowed a softer standalone performance. While the parent company's revenue grew 29%, its EBITDA margin contracted. The real story is the group's expansion, now heavily driven by its subsidiary entities.
The Cost That Won't Budge
Operating leverage, however, ran into a steep finance cost. Interest expense more than doubled year-on-year to ₹42 crore, reflecting the debt taken to build the Punjab plant. The company's debt-to-equity stood at 0.8, a level flagged as high by Univest.in.
Management has drawn a line. Director Sammir Dattani told CNBC TV18 the company does not expect to take on more debt, with net debt of ₹1,300 crore seen as the peak. Recent filings show a sharp cut in short-term borrowings, a step toward that pledge.
How Long Can It Last?
The outlook hinges on two factors: sustaining Punjab's utilisation and navigating input costs. Management is targeting 95% utilisation this quarter. They also expect ₹530-550 crore in EBITDA for the full year, according to SectorAlpha.
Raw material volatility remains a risk. While a September spike in cotton and polyester costs has unwound, reports like Bennycotts.com note the retreat may be temporary. The company's presence across polyester, cotton, and technical textiles provides a hedge.
The newly doubled technical textiles capacity at Silvassa, which started production in August, offers a higher-margin growth path for the coming year.
Key Points
- Consolidated revenue jumped 120% year-on-year, driven by the full-scale ramp-up of the Punjab integrated polyester facility.
- Profit tripled as operating leverage from higher volumes improved margins, despite interest costs more than doubling.
- Management has committed to no new debt, aiming to fund future expansion from internal accruals.
- The company's valuation commands a premium, with a P/E of 39.3 against an industry average of 30.7.
Hexa Perspective
This quarter confirms the Punjab facility as a transformative asset, finally delivering the operating leverage it was built for. The profit surge is real, but it comes atop a high-interest burden that will linger.
The path forward is about execution: maintaining near-full utilisation in Punjab, successfully scaling the higher-margin technical textiles business, and converting operating cash flow to steadily reduce leverage. If those align, the current growth trajectory has room to run.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.