(MAPMYINDIA) Q2 FY27 MapmyIndia Profit Soars 89% YoY Even as Revenue Dips Sequentially
The digital mapping leader posted a sharp 89% yearly profit jump, but sequential revenue dipped 5.5% as government segment sales fell from a high base.
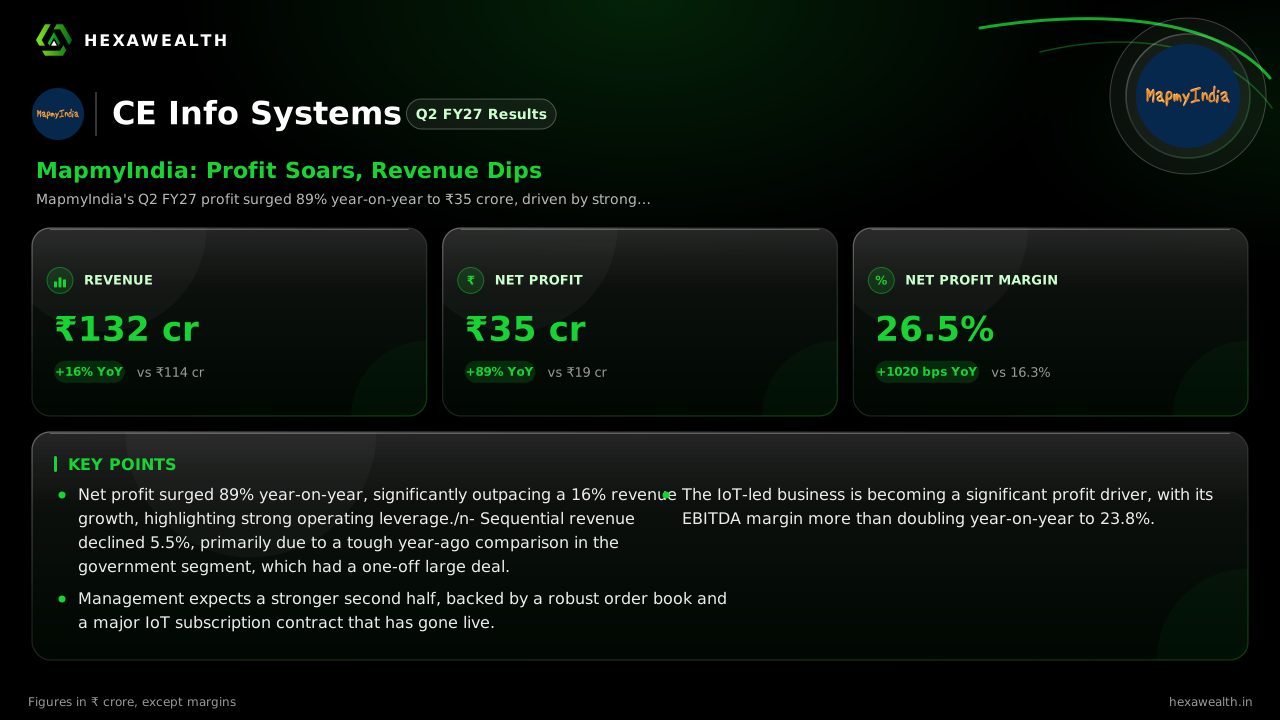
MapmyIndia's Q2 FY27 profit surged 89% year-on-year to ₹35 crore, driven by strong automotive and enterprise growth. However, revenue declined 5.5% sequentially, reflecting a tough comparison in the government business.
For MapmyIndia, the story this quarter is one of powerful profitability emerging from a shifting revenue mix. The digital maps and location-tech leader delivered a sharp 89% yearly jump in net profit, even as its top line took a sequential step back.
The numbers show a business in transition. Revenue of ₹132 crore grew 16% from a year ago but fell 5.5% from the previous quarter. Profit, at ₹35 crore, nearly doubled year-on-year but dropped 30% sequentially. The net profit margin tells the tale: up sharply year-on-year but down from the prior quarter's peak.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 132.0YoY +16% | 139.7 | 113.8 |
| Profit (₹ Cr) | 35.0YoY +89% | 49.7 | 18.5 |
| Net Profit Margin | 26.5%YoY +63% | 35.6% | 16.3% |
Why the quarter swung
The sequential revenue dip was led by the government segment, which fell 37.5% year-on-year. Management, cited in an Investing.com presentation, attributed this to a one-off revenue win in the year-ago quarter. The automotive and enterprise verticals, however, grew robustly at 52% and 44% respectively, according to the same source.
The sharp quarterly profit drop stemmed from this revenue mix shift and a lower contribution from other income, which fell 19% sequentially to ₹16 crore. The year-on-year profit explosion, meanwhile, was fueled by operating leverage and a dramatic improvement in the IoT-led business's margins.
The margin engine is shifting
A key development is the rising contribution and improving profitability of the IoT-led business. The Investing.com presentation noted its EBITDA margin jumped to 23.8% in Q2 from 10.6% a year ago, driven by better product mix and SaaS revenue from the installed hardware base. This is helping balance the company's traditionally map-led, high-margin core.
Management is confident the second half will be stronger than the first. They cited a substantial open order book and a newly live, large oil & gas IoT subscription contract as key drivers, per the earnings call transcript. The half-year EBITDA margin of 37.2% already exceeds their full-year target of 35%+.
The stock rose 4.8% on the results day, according to Investing.com data, as the market focused on the strong yearly profit growth and optimistic outlook. The company's valuation, however, carries a significant premium, with a P/E of 32.7 against an industry average of 19.2.
Key Points
- Net profit surged 89% year-on-year, significantly outpacing a 16% revenue growth, highlighting strong operating leverage./n- Sequential revenue declined 5.5%, primarily due to a tough year-ago comparison in the government segment, which had a one-off large deal.
- Management expects a stronger second half, backed by a robust order book and a major IoT subscription contract that has gone live.
- The IoT-led business is becoming a significant profit driver, with its EBITDA margin more than doubling year-on-year to 23.8%.
Hexa Perspective
MapmyIndia's quarter reveals a company successfully navigating a product transition. The core, high-margin map-led business provides stability, while the faster-growing IoT segment is now contributing meaningfully to profits. The near-term trajectory hinges on converting the stated strong order book, particularly in the recovering government vertical, to offset the lumpy quarterly comparisons. The valuation premium suggests the market is pricing in this growth transition and the company's unique moat in digital mapping. Execution on order conversion and sustaining the improved IoT margins will be critical to justify that premium in the coming quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.