GMM Pfaudler (GMMPFAUDLR) Q2 FY27 Profit Dips 11% Despite 18% Revenue Jump on European Losses
A record order book and strong revenue growth were overshadowed by a shrinking margin, as losses in Europe and higher costs weighed on the bottom line.
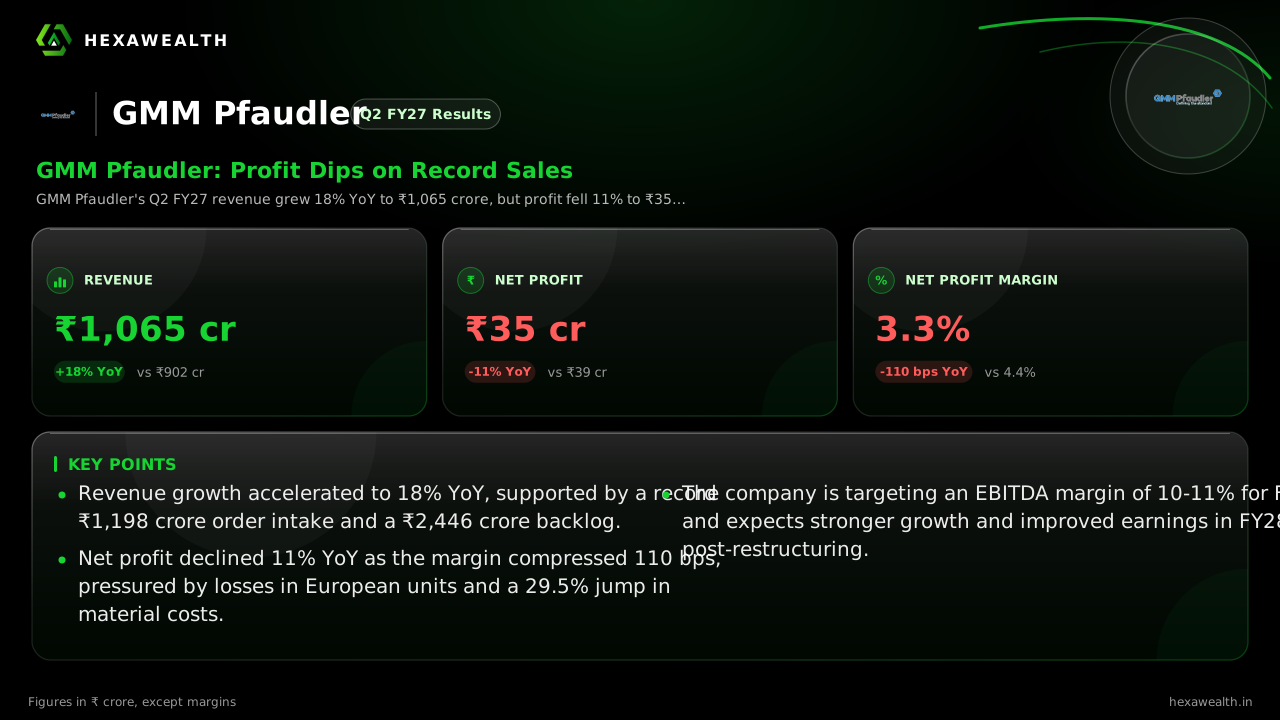
GMM Pfaudler's Q2 FY27 revenue grew 18% YoY to ₹1,065 crore, but profit fell 11% to ₹35 crore. A sharp margin contraction, driven by losses in European operations and rising input costs, offset the strong top-line performance.
For GMM Pfaudler, a global leader in critical process equipment, the September quarter presented a clear split between robust demand and persistent profitability challenges. Revenue surged to a new high, but the bottom line shrank as European operations and rising costs continued to drag.
The numbers show a business growing strongly but earning less on each rupee of sales. Revenue rose 18% year-on-year to ₹1,065 crore and 15% from the prior quarter. Profit, however, fell 11% YoY to ₹35 crore, though it jumped 58% sequentially from a low base. The net profit margin compressed by 110 basis points from a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,065.0YoY +18% | 924.8 | 902.3 |
| Profit (₹ Cr) | 35.0YoY -11% | 22.1 | 39.4 |
| Net Profit Margin (%) | 3.3YoY -25% | 2.4 | 4.4 |
The Growth Engine and Its Drag
The revenue momentum was driven by strong overseas demand, particularly in the CRT and HET divisions, according to reports from scanx.trade. This was supported by a record quarterly order intake of ₹1,198 crore, up 36% YoY, building a backlog of ₹2,446 crore that offers clear revenue visibility. However, this growth came at a cost. Total expenses surged 21.5% YoY, outpacing revenue.
A major drag is the loss-making European entities. Reports from scanx.trade and multibagg.ai note these units contributed an EBITDA loss of ₹43 crore in the first half. Excluding them, the adjusted EBITDA margin for Q2 would have been 15.9%, versus the reported 10.3%. The company is restructuring these operations, but the turnaround is a work in progress.
The Margin Squeeze and Its Causes
Beyond Europe, input cost inflation bit deeply. The cost of materials consumed jumped 29.5% YoY, according to scanx.trade, rising to 43.8% of revenue from 39.9% a year ago. Finance costs also rose 36% quarter-on-quarter, partly due to foreign currency losses on borrowings. This combination of operational and financial headwinds explains why profit fell even as sales climbed to a record.
The Road Ahead
Management has set an FY27 EBITDA margin target of 10-11%, which the Q2 print of 10.3% meets. The outlook, noted in reports from investywise.com, anticipates double-digit revenue growth and stronger performance in FY28 as restructuring benefits flow through. The market's read was mixed; Stewart & Mackertich issued an 'Accumulate' call with a ₹1,484 target, while MarketsMojo downgraded the stock to 'Hold' citing valuation and technical factors.
Key Points
- Revenue growth accelerated to 18% YoY, supported by a record ₹1,198 crore order intake and a ₹2,446 crore backlog.
- Net profit declined 11% YoY as the margin compressed 110 bps, pressured by losses in European units and a 29.5% jump in material costs.
- The company is targeting an EBITDA margin of 10-11% for FY27 and expects stronger growth and improved earnings in FY28 post-restructuring.
Hexa Perspective
The quarter underscores GMM Pfaudler's position in a strong demand cycle, evidenced by the swelling order book. Yet, the path to translating this into healthier profits runs directly through fixing its European operations and managing input costs. The guidance suggests management expects the margin pressure to persist through this fiscal year, with meaningful improvement deferred to FY28. Investors are thus left weighing solid revenue visibility against a profitability recovery that is promised but not yet delivered.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.