Comrade Appliances (COMRADE) Q2 FY27 Loss Narrows Despite a 39% Revenue Drop
The appliance maker's quarterly loss improved from the previous quarter, but a sharp decline in sales and rising interest costs signal deeper operational challenges.
Comrade Appliances reported a net loss of ₹6.68 crore for Q2 FY27, a slight improvement year-on-year. However, revenue fell sharply by 39%, highlighting severe demand pressure in its core air cooler and geyser markets.
For an OEM like Comrade Appliances, a sharp drop in sales is a direct signal of order flow from its retail and brand partners. The September quarter confirmed that pressure, with revenue falling to levels last seen over a year ago, even as a tighter cost grip offered a sliver of relief on the bottom line.
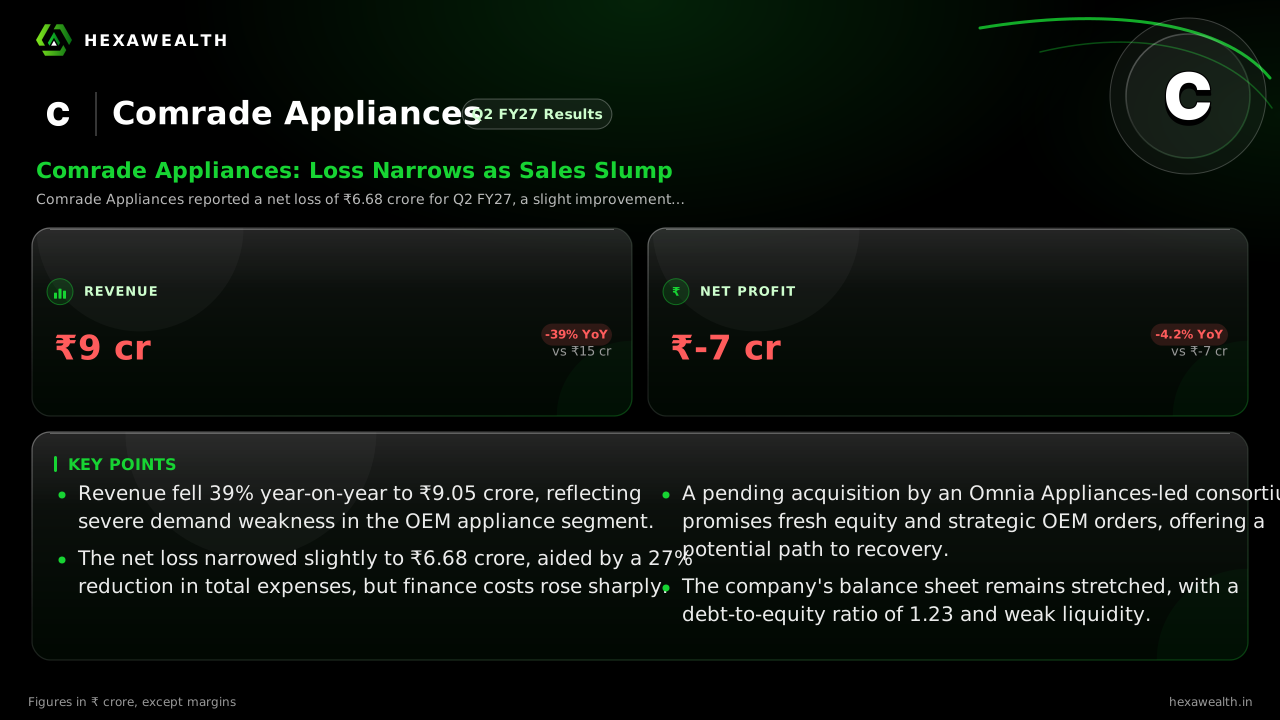
Revenue for Q2 FY27 stood at ₹9.05 crore, down 39% from the same period last year. The net loss was ₹6.68 crore, a marginal 4% improvement year-on-year but a significant 168% widening from the ₹2.49 crore loss in the prior quarter. The numbers reveal a business contracting faster than it can cut costs.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 9.05YoY -39% | 14.85 |
| Profit (₹ Cr) | -6.68YoY +4.2% | -6.97 |
The Cost-Cut That Wasn't Enough
Total expenses fell 27% year-on-year to ₹15.85 crore, as reported by First Bell. This reflects lower raw material and operating costs amid reduced production. However, finance costs rose 32% to ₹2.01 crore, pressuring the loss. A report from mCapital.in notes this includes an exceptional interest cost of ₹1.45 crore related to a vendor settlement.
The squeeze is structural. The company's debt-to-equity ratio stands at 1.23, and its current ratio of 0.86 indicates tight liquidity. While cost cuts provided a temporary buffer, they cannot offset a near-40% revenue decline for long.
A Turnaround Hinges on New Ownership
The operational story is now overshadowed by a pending change in control. A consortium led by fan-maker Omnia Appliances is set to acquire a 64% stake through a preferential issue and open offer, injecting ₹8.16 crore in fresh equity. Analysts cited by mCapital.in project this could bring OEM orders and help cut debt, potentially boosting revenue by ₹8-12 crore in the next year.
This capital is critical. It is expected to partly repay high-cost debt and fund expansion at the company's Palghar facility. For now, the core business of air coolers and geysers faces a tough market, with industry reports citing poor early-season demand and price hikes dampening consumer appetite.
Key Points
- Revenue fell 39% year-on-year to ₹9.05 crore, reflecting severe demand weakness in the OEM appliance segment.
- The net loss narrowed slightly to ₹6.68 crore, aided by a 27% reduction in total expenses, but finance costs rose sharply.
- A pending acquisition by an Omnia Appliances-led consortium promises fresh equity and strategic OEM orders, offering a potential path to recovery.
- The company's balance sheet remains stretched, with a debt-to-equity ratio of 1.23 and weak liquidity.
Hexa Perspective
This quarter underscores a company in transition, where operational metrics are secondary to a change in ownership. The revenue collapse points to a loss of order momentum with key clients, a gap the new promoters from Omnia Appliances must fill. The ₹8.16 crore equity infusion will ease immediate debt pressure, but the real test is whether it can unlock new manufacturing contracts to utilize existing capacity. Until then, the financials will likely remain under water, with any profit recovery contingent on the strategic shift materializing as planned.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.