CapitalNumbers Infotech (CNINFOTECH) Q4 FY26 Profit Drops 27% as Growth Investments Bite
The digital engineering firm posted a 27% sequential drop in Q4 profit as rising costs and slower enterprise decisions squeezed margins, despite stable revenue.
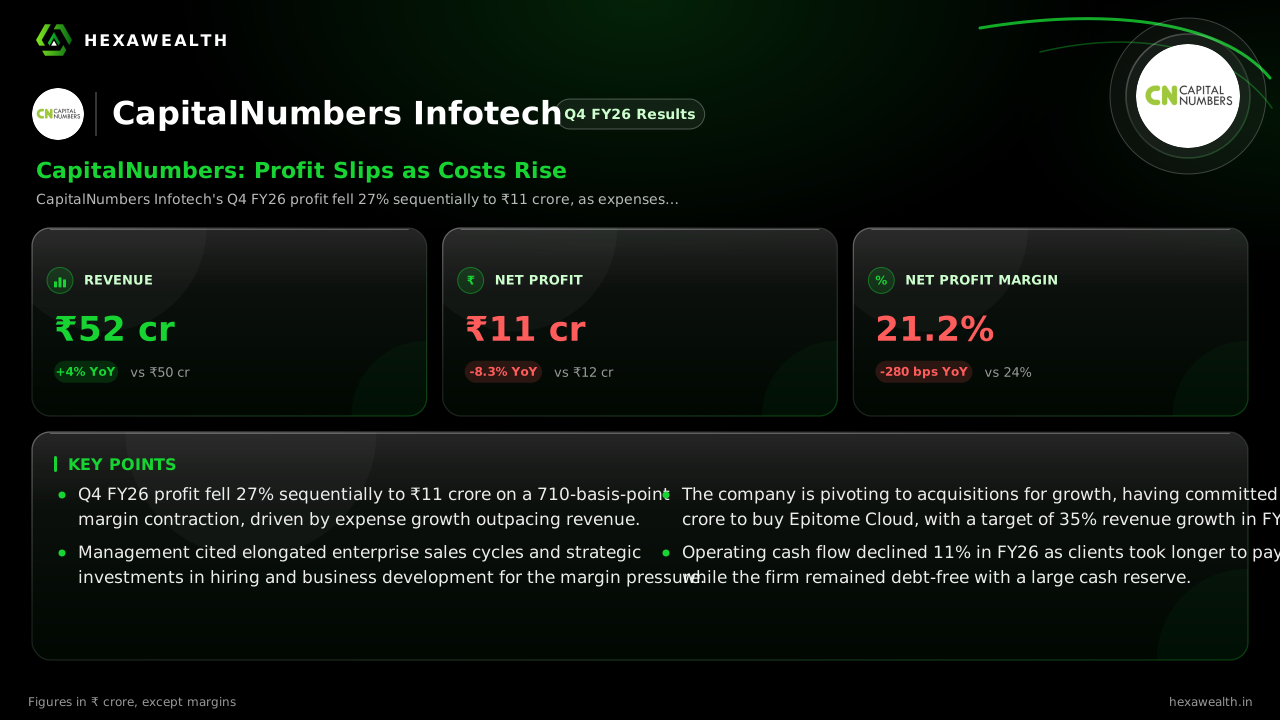
CapitalNumbers Infotech's Q4 FY26 profit fell 27% sequentially to ₹11 crore, as expenses grew faster than a modest revenue uptick. The company's operating margin declined, with management attributing pressure to strategic hiring and slower deal closures.
For CapitalNumbers Infotech, a steady business of renting out engineering teams met a quarter of rising costs and delayed client decisions. The result was a profit squeeze that overshadowed a modest revenue gain, setting the stage for a growth plan that now leans heavily on acquisitions.
The March quarter delivered revenue of ₹52 crore, up 4% from a year earlier. Profit, however, fell 8% year-on-year and 27% from the previous quarter to ₹11 crore. The net profit margin contracted sharply by 710 basis points sequentially to 21.2%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 52.0YoY +4% | 50.0 |
| Profit (₹ Cr) | 11.0YoY -8.3% | 12.0 |
| Net Profit Margin | 21.2%YoY -12% | 24.0% |
Why margins compressed
Total expenses rose 10.5% year-on-year, outpacing revenue growth. According to the company's investor presentation, operating margin fell as selling and hiring costs increased. Management noted on the earnings call that enterprise deal cycles elongated, pushing some revenue ramp-ups into the next fiscal year.
The company also held back in the Middle East, a region that contributed 11% of revenue. This caution, combined with the slower pace of large contract signings, limited top-line growth just as costs for business development and senior talent were rising.
The cash and acquisition pivot
Operating cash flow for the full year declined 11% to ₹17.1 crore, as debtor days stretched to 36. Meanwhile, cash from investing was a large outflow of ₹34.3 crore. This funded a strategic shift: the ₹40 crore acquisition of US-based Epitome Cloud.
The deal, aimed at bolstering Salesforce and US market capabilities, represents a pivot to inorganic growth. Management told Arthneeti it targets 35% revenue growth for FY27, with the acquisition contributing 25-30% of that increase.
The valuation gap
With a P/E of 6.9 against an industry average of 19.1, the stock trades at a steep discount. This reflects the market's skepticism about near-term organic growth, a view underscored by the profit decline. The company's guidance for a 200-basis-point margin recovery towards 33% is now a key monitorable.
Key Points
- Q4 FY26 profit fell 27% sequentially to ₹11 crore on a 710-basis-point margin contraction, driven by expense growth outpacing revenue.
- Management cited elongated enterprise sales cycles and strategic investments in hiring and business development for the margin pressure.
- The company is pivoting to acquisitions for growth, having committed ₹40 crore to buy Epitome Cloud, with a target of 35% revenue growth in FY27.
- Operating cash flow declined 11% in FY26 as clients took longer to pay, while the firm remained debt-free with a large cash reserve.
Hexa Perspective
The quarter reveals a core challenge: the time-and-material model provides stability but little organic growth momentum. Profit now depends on controlling costs while large enterprise deals take shape.
The promised margin recovery and the Epitome Cloud integration are the twin triggers. If the acquisition delivers the projected revenue and does not further dilute profitability, the current valuation gap could narrow. The risk is that the hunt for growth keeps margins subdued for longer than guided.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.