Coreintegra Consulting (COREIN) Q2 FY27 Revenue Tops ₹278 Crore, But Profit Margin Stays at 0.6%
The HR services provider posted revenue of ₹278.2 crore for Q2 FY27, but high employee expenses kept its net profit margin at a wafer-thin 0.6%.
Coreintegra Consulting reported Q2 FY27 revenue of ₹278.2 crore but a net profit of just ₹1.57 crore, reflecting the intense cost pressures in the staffing industry. The company's heavy reliance on a few large clients continues to be a key risk.
For staffing and HR services firms like Coreintegra Consulting, growth is often a story of scale without proportional profit. The company's September quarter results underscore that tension, as rising revenue was almost entirely consumed by the cost of delivering it.
Coreintegra reported revenue of ₹278.2 crore for Q2 FY27, leading to a net profit of ₹1.57 crore. The net profit margin was a slim 0.6%, a level characteristic of the labour-intensive staffing sector.
| Metric | CurrentQ2 FY27 |
|---|---|
| Revenue (₹ Cr) | 278.2 |
| Profit (₹ Cr) | 1.57 |
| Net Profit Margin (%) | 0.6 |
Why the bottom line stays thin
Employee benefit expenses, at ₹191.18 crore, accounted for nearly 69% of total revenue. This structural high-cost model leaves little room for error. An equity research report from Equity Research India notes that such thin margins provide “essentially no buffer to absorb adverse operating conditions.”
The business also carries significant client concentration risk. A single customer contributed over 53% of revenue in the last fiscal year, according to the same analysis. Losing even one major client could materially impact operations.
The path to better margins
Management's strategy hinges on its proprietary technology platforms, like the Ctrl F compliance software. The company plans to deploy a significant portion of its IPO proceeds to upgrade this IT infrastructure, as noted in its offer documents. The goal is to shift toward higher-margin, technology-led services over time.
However, these segments currently contribute less than 1% of total revenue. Scaling them meaningfully while managing the core staffing business's costs will be the central challenge for the next few quarters.
Key Points
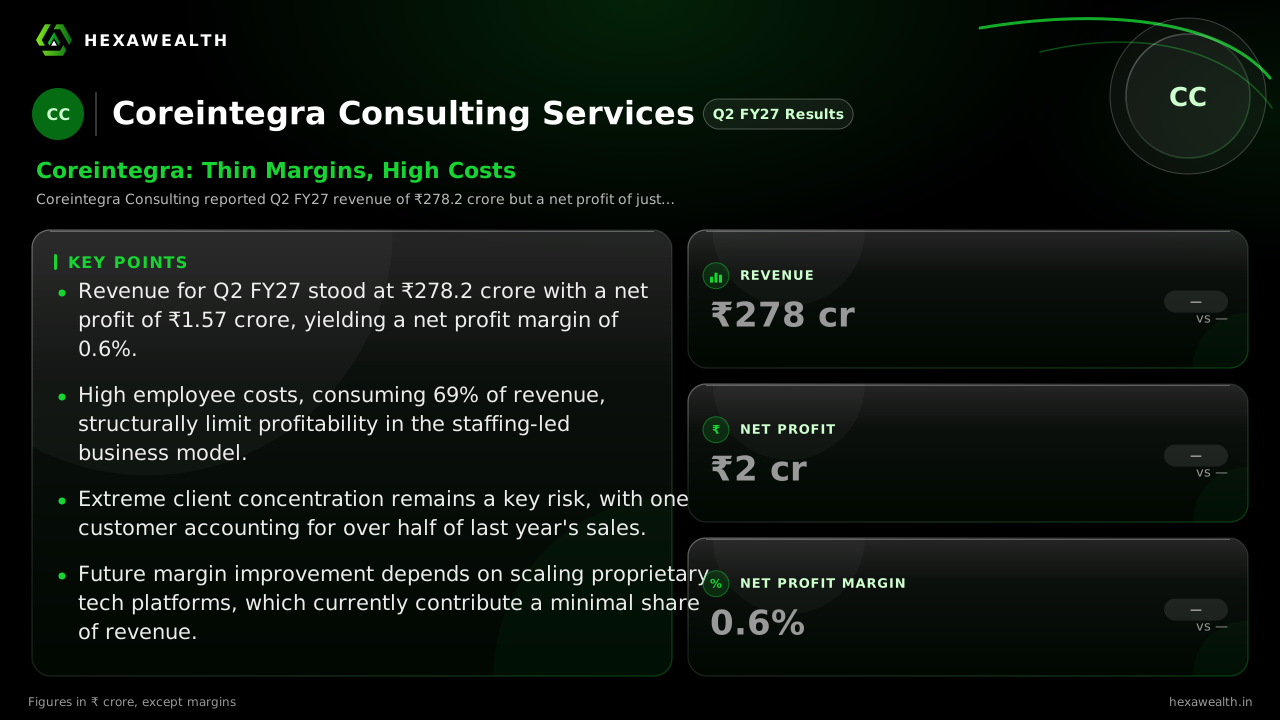
- Revenue for Q2 FY27 stood at ₹278.2 crore with a net profit of ₹1.57 crore, yielding a net profit margin of 0.6%.
- High employee costs, consuming 69% of revenue, structurally limit profitability in the staffing-led business model.
- Extreme client concentration remains a key risk, with one customer accounting for over half of last year's sales.
- Future margin improvement depends on scaling proprietary tech platforms, which currently contribute a minimal share of revenue.
Hexa Perspective
The quarter confirms Coreintegra operates in a tough neighborhood where revenue growth does not easily translate to earnings power. The company's return ratios are healthy—ROE and ROCE were 18.37% and 19.55% respectively—but they are supported by an asset-light model, not high margins.
Investors are essentially betting on the company's ability to use technology to change its margin profile. Until the Ctrl F platform and other tech services gain material traction, profits will likely remain hostage to the low-margin, people-intensive staffing business that drives most of its sales.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.