Moxsh Overseas Educon (MOXSH) Q2 FY27's Revenue Jumps 93% but Profit Slips into the Red
The overseas education consultancy saw a sharp sequential drop in revenue and a return to a quarterly loss, as rising depreciation and a seasonal lull weighed on margins.
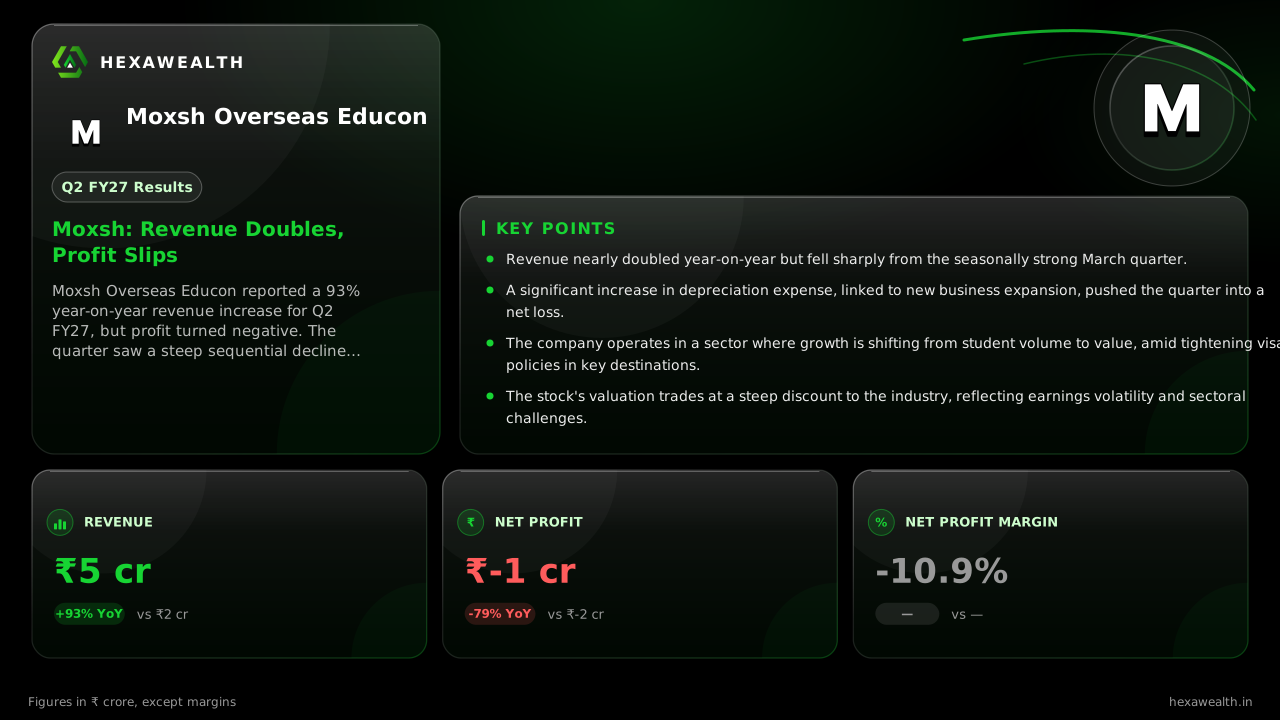
Moxsh Overseas Educon reported a 93% year-on-year revenue increase for Q2 FY27, but profit turned negative. The quarter saw a steep sequential decline from a strong Q4, with rising depreciation costs eroding the bottom line.
For an overseas education consultancy, the September quarter is often a lull between major intakes. Moxsh Overseas Educon’s Q2 FY27 results reflect that seasonality, with revenue halving sequentially even as it nearly doubled from a weak year-ago period. The real story, however, is a sharp swing from a 45% net profit margin last quarter to a loss this time.
Revenue stood at ₹4.66 crore, up 93.4% from Q2 FY26 but down 55.6% from the prior quarter. Profit turned to a loss of ₹0.51 crore, a 110.9% sequential drop. The net profit margin fell to -10.9%, a stark reversal from 44.7% in Q4 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 4.66YoY +93% | 2.41 |
| Profit (₹ Cr) | -0.51YoY +79% | -2.39 |
| Net Profit Margin (%) | -10.9 | - |
Why the profit vanished
A 38% quarter-on-quarter jump in depreciation was a key drag, rising to ₹1.12 crore. Research from StockScans suggests this stems from investments in a new healthcare migration business and physical ‘Studium’ centres in Germany. While employee and interest costs fell, this fixed-cost increase overwhelmed a seasonally softer top line.
The market is tightening
Broader headwinds add context. Credence Research reports the overseas education consulting market is growing through higher value per student, not volume, as destinations like Canada and the UK tighten visa rules. The Economic Times notes universities in these countries are facing pressure from weaker international enrolments. For Moxsh, this means the core business must navigate a more challenging recruitment landscape.
A valuation paradox
Despite the quarterly loss, the trailing-twelve-month picture shows a profit of ₹1.41 crore on revenue of ₹21.6 crore. The stock trades at a P/E of 43.4, a 52% discount to the industry average of 90.1, according to the payload. This gap suggests the market is heavily discounting future earnings, likely weighing the sector's regulatory risks against the company's own volatile performance.
Key Points
- Revenue nearly doubled year-on-year but fell sharply from the seasonally strong March quarter.
- A significant increase in depreciation expense, linked to new business expansion, pushed the quarter into a net loss.
- The company operates in a sector where growth is shifting from student volume to value, amid tightening visa policies in key destinations.
- The stock's valuation trades at a steep discount to the industry, reflecting earnings volatility and sectoral challenges.
Hexa Perspective
The quarter underscores the operational leverage challenge in this business. High fixed costs from new investments need a consistently strong revenue base to become profitable, but revenue is inherently lumpy and now faces external policy pressures. The 52% industry discount is not a free lunch; it prices in the risk that the current investment phase may not pay off if student flows weaken further. Investors are left weighing the long-term potential of the German healthcare pipeline against the immediate volatility of the core consultancy, with the next quarter's revenue rebound being a critical test.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.