Cian Healthcare (CHCL) Q4 FY26's Q4 Loss Doubles as Restart Costs Overshadow Revenue Rebound
The pharmaceutical firm's quarterly revenue jumped 42%, but a large negative other income item pushed its net loss to ₹18 crore, highlighting a challenging post-insolvency rebuild.
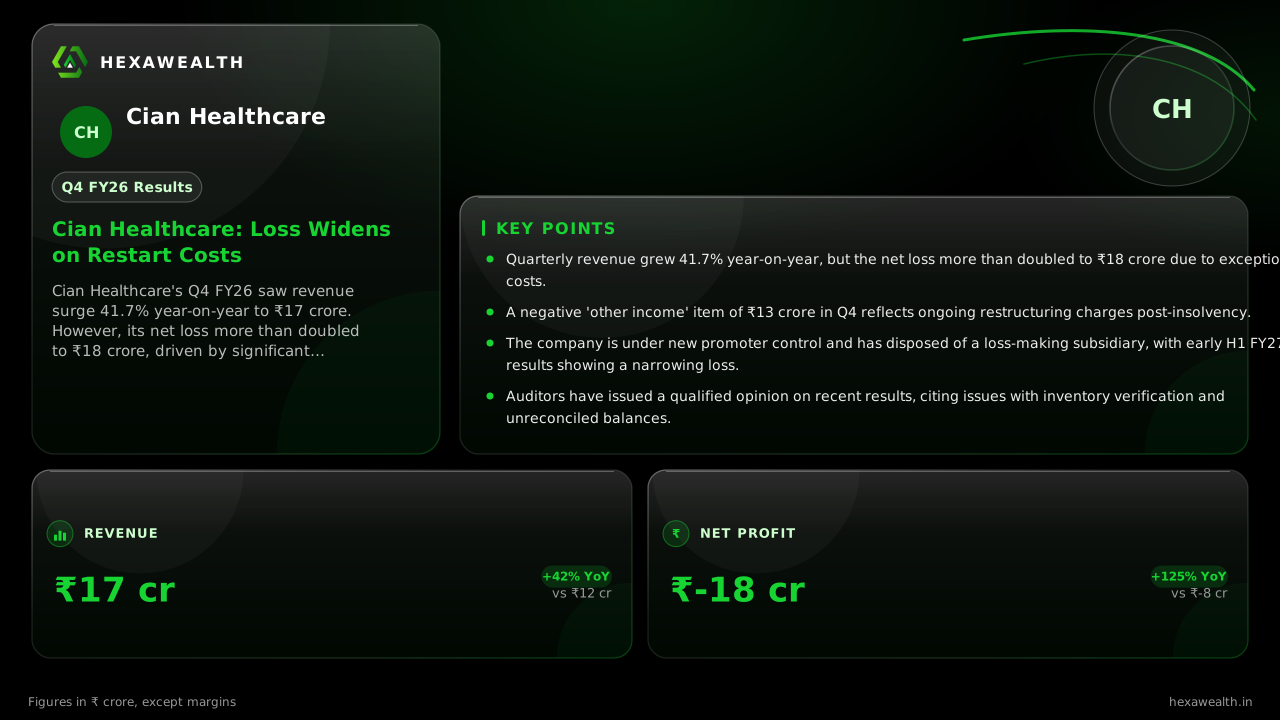
Cian Healthcare's Q4 FY26 saw revenue surge 41.7% year-on-year to ₹17 crore. However, its net loss more than doubled to ₹18 crore, driven by significant exceptional costs as the company restarts under new management.
For Cian Healthcare, the March quarter was a story of two halves. Revenue rebounded sharply as new management began rebuilding operations after exiting insolvency. Yet, the financials reveal the heavy cost of that restart, with losses deepening despite the top-line gain.
The numbers show a company in transition. Revenue for Q4 FY26 rose to ₹17 crore, a 41.7% increase from the same quarter last year. However, the net loss widened to ₹18 crore from ₹8 crore. Over the full year, revenue fell 9.1% to ₹28 crore, with an annual net loss of ₹23 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 17.0YoY +42% | 12.0 |
| Profit (₹ Cr) | -18.0YoY -125% | -8.0 |
Why the bottom line sank deeper
A key driver of the quarterly loss was a negative 'other income' of ₹13 crore. According to data from mcapital.in, this item, alongside a similar ₹12 crore charge in September 2024, points to exceptional costs tied to the corporate insolvency resolution process (CIRP). These are likely inventory revaluations and write-offs as the company restructures its balance sheet under new ownership.
The post-CIRP rebuild is underway
Cian Healthcare exited the insolvency process in FY26, with Ananta Medicare taking over as the new promoter in February 2026. The recent disposal of a loss-making subsidiary, Dr. Smith's Biotech, removes a financial overhang. A report from stockfin.ai notes management is currently focused on stabilizing operations and governance, with no immediate expansion plans announced.
Early signs from the new fiscal year suggest some operational improvement. For the half-year ended September 2026, mcapital.in reports consolidated revenue of ₹12.49 crore and a sharply lower net loss of ₹1.43 crore. This points to a significantly reduced annual loss for FY27, though revenue may remain flat.
Key Points
- Quarterly revenue grew 41.7% year-on-year, but the net loss more than doubled to ₹18 crore due to exceptional costs.
- A negative 'other income' item of ₹13 crore in Q4 reflects ongoing restructuring charges post-insolvency.
- The company is under new promoter control and has disposed of a loss-making subsidiary, with early H1 FY27 results showing a narrowing loss.
- Auditors have issued a qualified opinion on recent results, citing issues with inventory verification and unreconciled balances.
Hexa Perspective
The quarter underscores the dichotomy of a corporate turnaround. While the revenue bounce is a necessary first step, the magnitude of exceptional costs reveals how deeply the insolvency process impacted the balance sheet. The path to sustained profitability now hinges on the new management's ability to rebuild sales volume to historical levels—above ₹60 crore quarterly—while maintaining cost discipline. Investors are weighing a clearer operational slate against persistent governance red flags. The auditor's qualified opinion on basic controls remains a material risk until resolved. The next few quarters will test whether the operational green shoots from H1 FY27 can mature without further unexpected legacy costs.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.