Shreeji Shipping (SHREEJISPG) Q2 FY27 Profit Falls 14% Even as Revenue Jumps 39.5%
The September quarter saw a sharp margin squeeze as higher freight rates were offset by surging costs from the company's debt-funded fleet expansion.
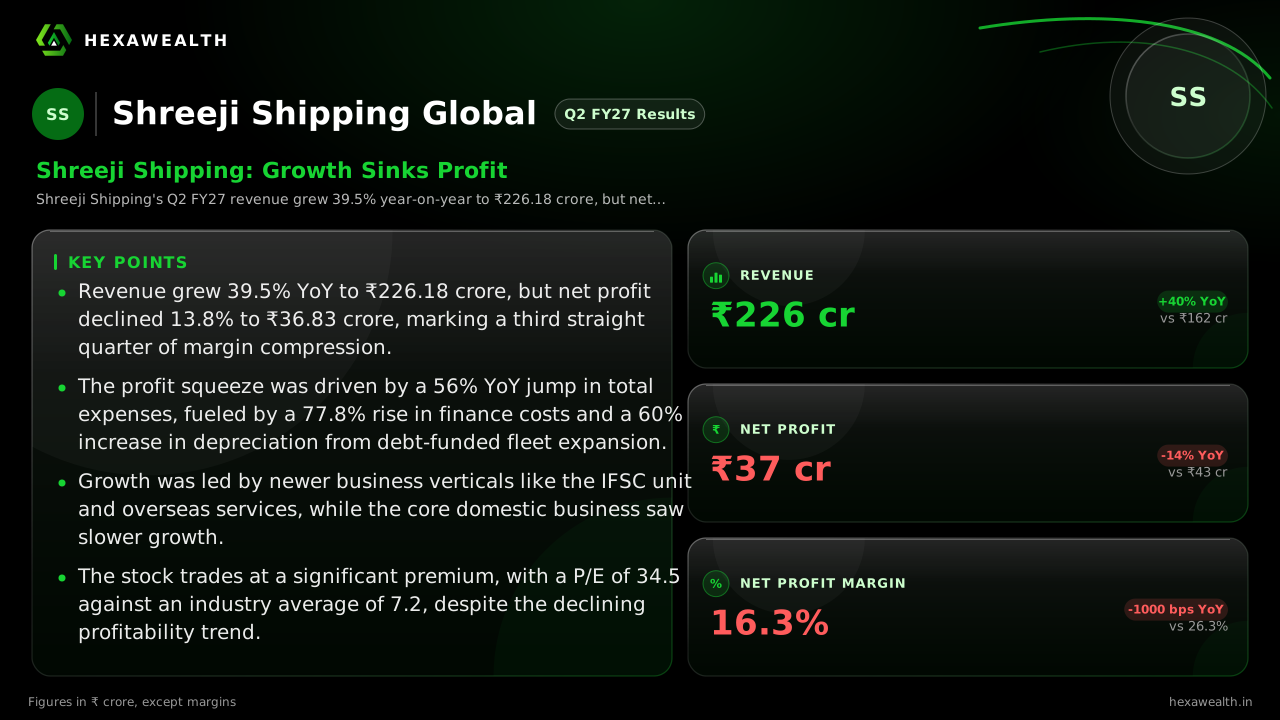
Shreeji Shipping's Q2 FY27 revenue grew 39.5% year-on-year to ₹226.18 crore, but net profit fell 13.8% to ₹36.83 crore. The decline was driven by a sharp 56% jump in total expenses, including higher interest and depreciation costs.
For Shreeji Shipping, a quarter of strong top-line growth was overshadowed by a profitability squeeze that has become a recurring theme. The company's revenue jumped 39.5% year-on-year, yet net profit fell 13.8% as costs from its aggressive fleet build-out bit deeper.
The numbers show a clear divergence. Revenue reached ₹226.18 crore, a healthy sequential gain of 8.3%. Net profit, however, slid to ₹36.83 crore, down 16.8% from the previous quarter. The net profit margin compressed by 1,000 basis points year-on-year to 16.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 226.18YoY +39% | 208.85 | 162.19 |
| Profit (₹ Cr) | 36.83YoY -14% | 44.29 | 42.70 |
| Net Profit Margin (%) | 16.3YoY -38% | 21.2 | 26.3 |
The Cost of Expansion
The primary driver of the profit decline was a 56% year-on-year surge in total expenses, according to the analysis. A report from StockWatch highlights that finance costs rose 77.8% and depreciation jumped 60%, consistent with a debt-funded fleet build-out. Non-current borrowings nearly doubled to ₹135.71 crore from March 2026.
This expansion is a strategic push beyond its core port services. StockWatch notes revenue growth leaned on newer channels like its IFSC unit and overseas services, while within-India services grew a more modest 33.1%. The company is transforming, but the new assets are yet to deliver operating leverage.
A Crowded Horizon
The cost pressure arrives amid a supportive freight environment. Reports cite a surge in tanker spot rates due to tensions in the Strait of Hormuz, benefiting the broader shipping sector. For Shreeji, however, these potential gains are being absorbed by its own capital intensity.
The path ahead hinges on utilization. With shareholders recently approving a ₹1,500 crore borrowing limit, the capex cycle is set to continue. The company must now demonstrate that its growing fleet can generate returns that outpace the rising interest and depreciation burden.
Key Points
- Revenue grew 39.5% YoY to ₹226.18 crore, but net profit declined 13.8% to ₹36.83 crore, marking a third straight quarter of margin compression.
- The profit squeeze was driven by a 56% YoY jump in total expenses, fueled by a 77.8% rise in finance costs and a 60% increase in depreciation from debt-funded fleet expansion.
- Growth was led by newer business verticals like the IFSC unit and overseas services, while the core domestic business saw slower growth.
- The stock trades at a significant premium, with a P/E of 34.5 against an industry average of 7.2, despite the declining profitability trend.
Hexa Perspective
The quarter underscores the tension between Shreeji Shipping's growth ambitions and its current financial reality. The company is successfully scaling its top line and diversifying its revenue base, which is a positive long-term signal.
Yet, the persistent margin erosion—with net profit margin now 1,000 basis points below last year—raises questions about the near-term payoff of its aggressive expansion. Investors are effectively betting that today's heavy capital expenditure will translate into sustainably higher earnings power tomorrow. For that bet to pay off, operational efficiency and asset utilization must improve markedly to offset the structural rise in fixed costs.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.