Creative Graphics Solutions (CGRAPHICS) Profit Falls 55% as Revenue Crashes in Q2 FY27
The packaging firm's quarterly sales plunged by over half year-on-year, but a sharp drop in expenses kept net profit margin steady.
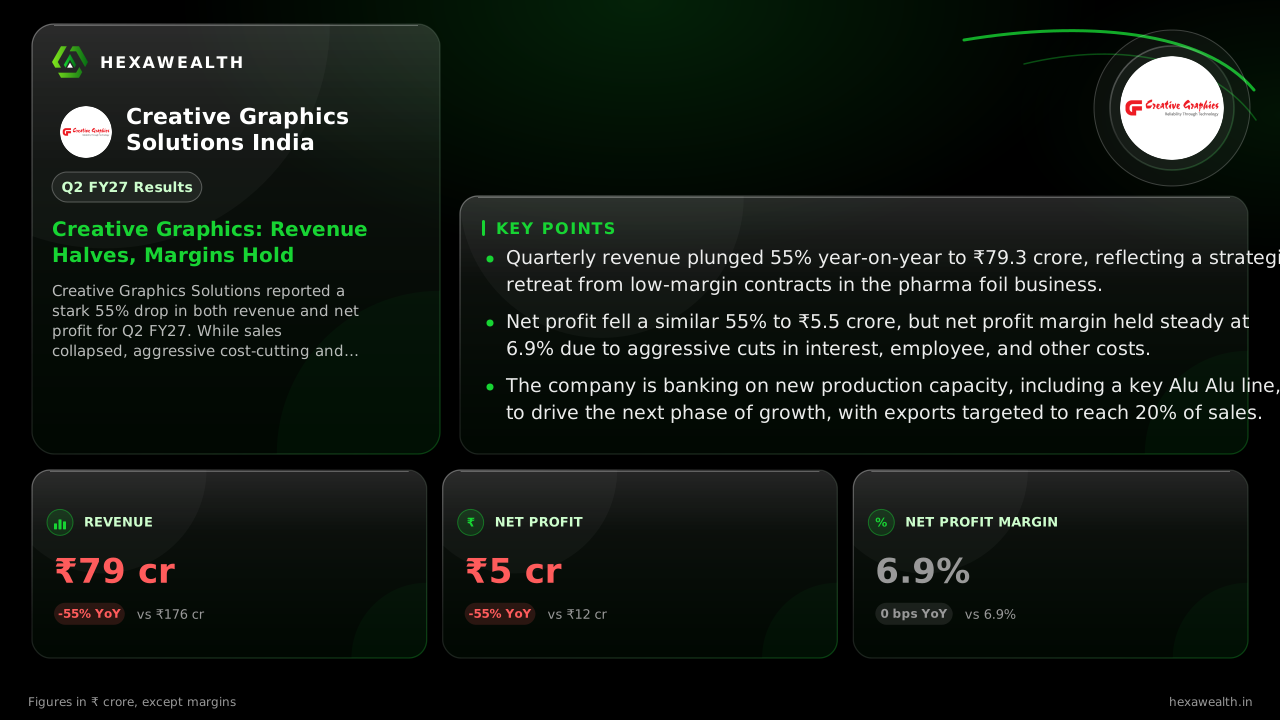
Creative Graphics Solutions reported a stark 55% drop in both revenue and net profit for Q2 FY27. While sales collapsed, aggressive cost-cutting and lower interest expenses helped the company maintain its net profit margin at 6.9%.
For Creative Graphics Solutions, a sharp pivot in its pharma packaging business has defined the last two quarters. The September quarter saw revenue more than halve from a year ago, but the company managed to protect its bottom line by cutting costs even faster.
The numbers tell a story of a sudden contraction. Revenue fell 55% year-on-year to ₹79.3 crore, and net profit followed, down 55% to ₹5.5 crore. Sequentially, the drop was even steeper from the March quarter, with revenue down 53%. Yet, the net profit margin held at 6.9%, unchanged from a year ago and up 300 basis points from the previous quarter.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentSep 2026 (Q2 FY27) | PreviousMar 2026 (Q4 FY26) |
|---|---|---|
| Revenue (₹ Cr) | 79.32 | 170.09 |
| Net Profit (₹ Cr) | 5.46 | 6.56 |
| Net Profit Margin (%) | 6.9 | 3.9 |
The Aluminium Squeeze Unwinds
The crash in revenue is directly tied to its foil business, where aluminium makes up half the raw material. According to a May 2026 investor call cited by Newboard, the company had absorbed a ₹5 crore gross margin hit in the second half of FY26 due to spiking metal prices and supply delays. This quarter likely reflects a strategic pullback from such unprofitable, fixed-price contracts, leading to lower sales volumes.
How Costs Fell Faster Than Sales
Profit did not fall as steeply as revenue because expenses were slashed in tandem. Total expenses dropped 55% year-on-year. Interest costs fell 63%, and employee costs were trimmed. Other income, which had provided a ₹2 crore boost in the March quarter, collapsed to just ₹0.05 crore. This disciplined cost control is why the net profit margin held firm.
Waiting for New Capacity to Ramp Up
The outlook now hinges on new production lines starting to contribute. Management, as noted in a Newboard report, expects the new 12,000-tonne Alu Alu line to start commercial production in the first half of FY27. The company also targets exports to make up 20% of revenue. Until these new capacities ramp up and stabilize raw material costs, revenue may remain under pressure, even as the company defends its margins through strict cost management.
Key Points
- Quarterly revenue plunged 55% year-on-year to ₹79.3 crore, reflecting a strategic retreat from low-margin contracts in the pharma foil business.
- Net profit fell a similar 55% to ₹5.5 crore, but net profit margin held steady at 6.9% due to aggressive cuts in interest, employee, and other costs.
- The company is banking on new production capacity, including a key Alu Alu line, to drive the next phase of growth, with exports targeted to reach 20% of sales.
Hexa Perspective
This quarter shows a company in transition, deliberately sacrificing top-line growth to reset profitability after a period of raw material pain. The steady margin is a positive signal of operational control. The investment case now rests entirely on the successful ramp-up of new foil capacity and the management's ability to convert it into sales without reigniting last year's margin pressures. Investors are effectively paying for future execution, with the stock's 22% one-year decline and a P/E of 20.7—a 54% discount to the industry—pricing in significant skepticism.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.