Panacea Biotec (PANACEABIO) Q2 FY27 Profit Jumps 441% as Costs Fall Sharply
Panacea Biotec's Q2 FY27 profit surged despite a slight revenue dip, driven by a sharp reduction in total expenses and a favorable tax reversal.
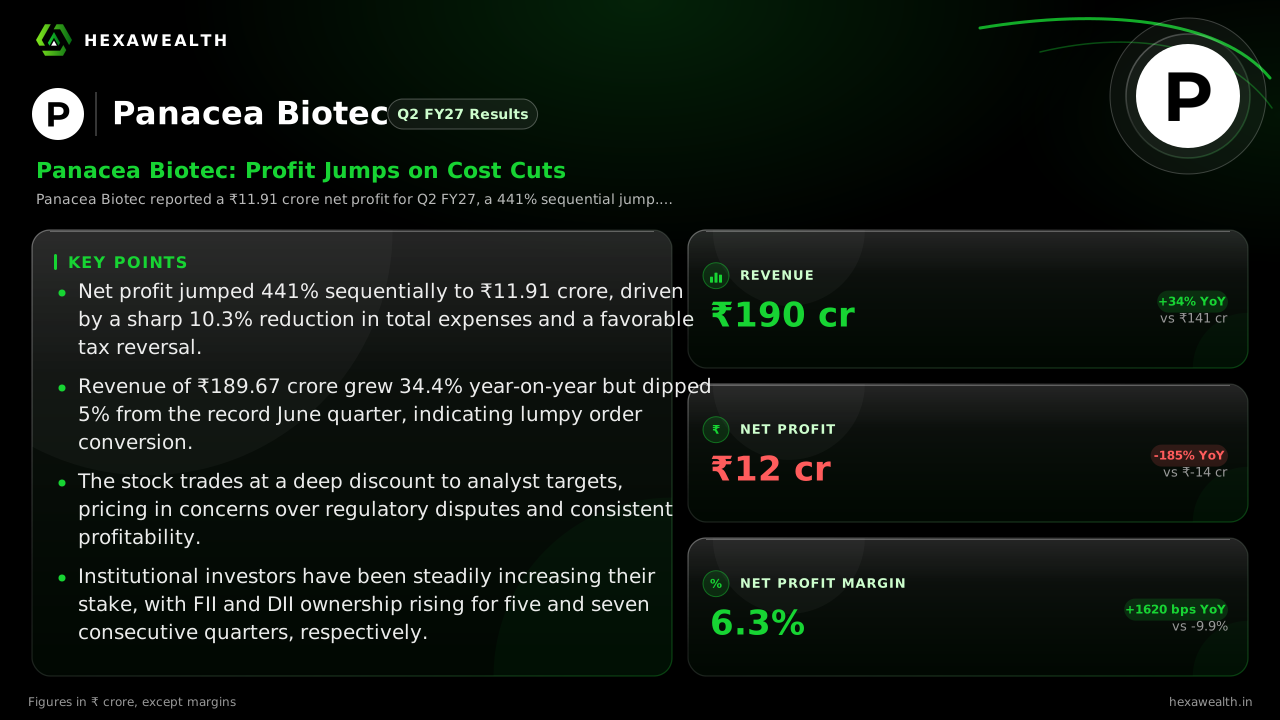
Panacea Biotec reported a ₹11.91 crore net profit for Q2 FY27, a 441% sequential jump. This came despite a 5% drop in revenue, as the company slashed total expenses by over 10% from the previous quarter.
Panacea Biotec’s September quarter was a story of profitability arriving ahead of schedule. The company delivered a sharp profit jump by finally getting a handle on costs, even as revenue from its vaccine order book took a slight breather.
The numbers show a clear pivot. Revenue was ₹189.67 crore, down 5% from the June quarter but up a strong 34% from a weak year-ago base. The real story is the bottom line: net profit soared to ₹11.91 crore, a 441% sequential jump. This pushed the net profit margin to 6.3%, a significant recovery.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 189.67 | 199.57 |
| Net Profit (₹ Cr) | 11.91 | 2.20 |
| Net Profit Margin (%) | 6.3 | 1.1 |
Where the Profit Jump Came From
The profit surge was powered by a 10.3% quarter-on-quarter drop in total expenses. According to the analysis, this was led by a 49% fall in interest costs and a 7.8% reduction in depreciation. A tax reversal of ₹5.08 crore, compared to a ₹1.37 crore expense last quarter, provided a further one-time boost.
This suggests a quarter of operational discipline, possibly aided by timing of shipments from its institutional order book. A preview from Stockwatch.live noted the market was watching for cost stabilization after expenses had compressed profits in prior periods.
The Backlog and the Skepticism
The company’s growth narrative is tied to converting a ₹600+ crore order backlog, including a recent $8.2 million UNICEF award. While this provides visibility, the market remains cautious. Stockwatch.live reports the stock trades nearly 40% below the analyst consensus target, reflecting skepticism on execution and regulatory risks.
Those risks are real. The company faces income tax demands and a GST show cause notice totaling over ₹18 crore. While these are being contested, they represent a contingent overhang on cash flows and management focus.
Key Points
- Net profit jumped 441% sequentially to ₹11.91 crore, driven by a sharp 10.3% reduction in total expenses and a favorable tax reversal.
- Revenue of ₹189.67 crore grew 34.4% year-on-year but dipped 5% from the record June quarter, indicating lumpy order conversion.
- The stock trades at a deep discount to analyst targets, pricing in concerns over regulatory disputes and consistent profitability.
- Institutional investors have been steadily increasing their stake, with FII and DII ownership rising for five and seven consecutive quarters, respectively.
Hexa Perspective
This quarter demonstrates Panacea Biotec’s ability to improve profitability when it reins in costs. The jump from a 1.1% to a 6.3% net margin is meaningful, but its durability is the open question.
The path forward hinges on two factors: smoothly converting the large order backlog into steady quarterly revenue, and keeping operational and regulatory costs contained. If the company can string together a few quarters of similar margin discipline alongside its topline growth, the current valuation gap may narrow. Until then, the quarter is a positive step in a longer turnaround story.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.