Vikram Solar (VIKRAMSOLR) Q2 FY27 Profit Crashes 95% as Expansion Costs Bite
Vikram Solar's Q2 FY27 profit collapsed to just ₹6 crore, a 95% drop, as heavy investment in new capacity and rising costs erased earnings.
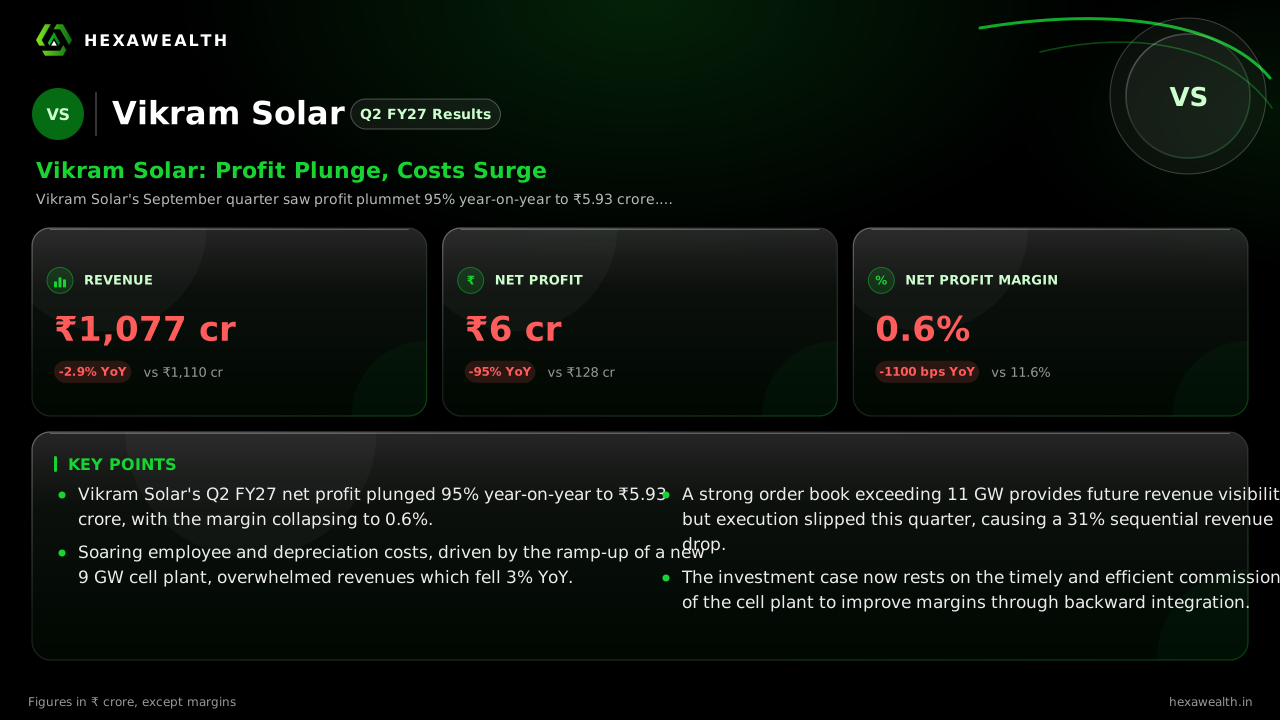
Vikram Solar's September quarter saw profit plummet 95% year-on-year to ₹5.93 crore. Revenue also slipped 3% as a surge in employee and depreciation costs from its massive capacity expansion squeezed margins to just 0.6%.
For Vikram Solar, the September quarter was a brutal test of whether its massive manufacturing expansion could deliver profits alongside sales. The results show the cost of that ambition, with earnings nearly wiped out.
Revenue for Q2 FY27 was ₹1,077 crore, down 3% from a year ago and 31% from the previous quarter. The real story is the profit collapse: net profit fell 95% year-on-year to just ₹5.93 crore. The net profit margin shrank to 0.6%, down from 11.6% in Q2 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 1,077.41 | 1,563.09 |
| Profit (₹ Cr) | 5.93 | 19.78 |
| Net Profit Margin (%) | 0.6 | 1.3 |
The cost of building the future
The margin collapse is a direct result of the company's aggressive investment phase. Employee costs surged 59% year-on-year, while depreciation jumped 89%, according to the analysis. Reports from Stockwatch and NexNews Network link this to the ramp-up of its new 9 GW TOPCon cell plant in Tamil Nadu, which is on schedule for first production in December 2026.
This heavy spending comes amid a tough market. Informist Media noted that higher production costs and intense competition pressured selling prices. A report from Mercom India suggests module manufacturing margins in India have compressed significantly, with tolling charges falling sharply.
A strong order book meets weak execution
Despite the weak quarter, demand visibility remains high. The company has announced a series of large orders, including a 290 MWp supply contract from NLC India in October. Flash Finance reports the company maintains a robust order book of over 11 GW.
However, these new wins came after the quarter ended. The sharp sequential drop in revenue suggests execution and delivery schedules slipped, preventing order book strength from translating into quarterly sales.
The path forward hinges on integration
Management has guided for FY27 EBITDA to be 1.7 times that of FY26, as noted by Stockwatch. The critical assumption is that the new cell plant, once operational, will improve margins through backward integration and reduce reliance on imported cells.
The company's balance sheet is set for a shift. Insights.dsij.in reports Prabhudas Lilladher expects substantial debt-funded capital expenditure of about ₹5,000 crore each in FY27 and FY28. Success now depends on the new facility ramping up efficiently to start repaying this heavy investment.
Key Points
- Vikram Solar's Q2 FY27 net profit plunged 95% year-on-year to ₹5.93 crore, with the margin collapsing to 0.6%.
- Soaring employee and depreciation costs, driven by the ramp-up of a new 9 GW cell plant, overwhelmed revenues which fell 3% YoY.
- A strong order book exceeding 11 GW provides future revenue visibility, but execution slipped this quarter, causing a 31% sequential revenue drop.
- The investment case now rests on the timely and efficient commissioning of the cell plant to improve margins through backward integration.
Hexa Perspective
Vikram Solar is caught in the classic growth-investment trap. The quarter confirms that top-line demand is not the issue, but converting it into earnings is. The 95% profit drop shows the severe near-term cost of building capacity ahead of revenue.
The next two quarters are decisive. If the December cell plant start-up goes smoothly and begins to offset procurement costs, the margin recovery story can begin. If ramp-up delays persist or market pricing worsens, the heavy debt-funded capex could weigh on returns for longer. Investors are paying for future integration, but patience is wearing thin.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.