Classic Leasing (CLFL) Q1 FY27 Profit Growth Slows as Costs Outpace Revenue
The NBFC's revenue more than doubled year-on-year, but profit growth slowed sharply quarter-on-quarter as expenses jumped 31%.
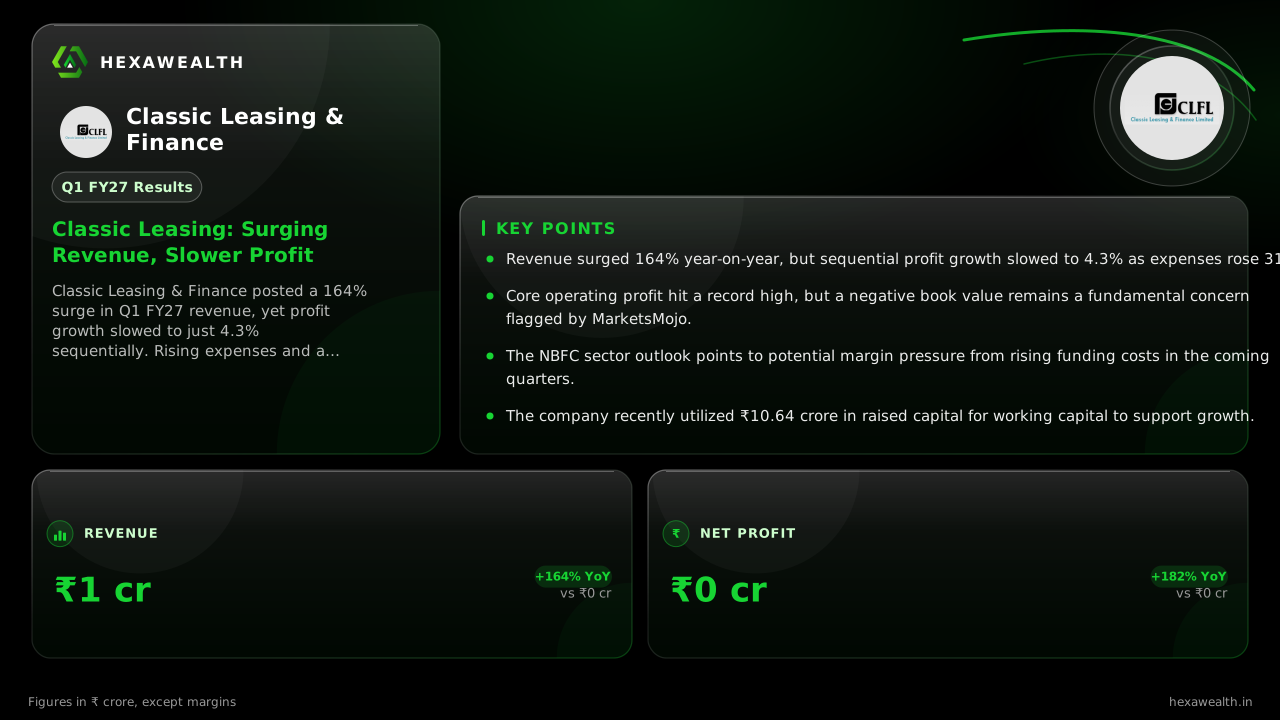
Classic Leasing & Finance posted a 164% surge in Q1 FY27 revenue, yet profit growth slowed to just 4.3% sequentially. Rising expenses and a looming sector-wide margin squeeze temper the strong headline performance.
For a small NBFC like Classic Leasing & Finance, a quarter of explosive growth is a signal of momentum, but the pace of profit tells the real story. The company's Q1 FY27 saw revenue more than double from a year ago, yet profit growth slowed sharply from the previous quarter as costs rose faster than income.
Revenue reached ₹0.58 crore, up 163.6% from Q1 FY26. Profit followed a similar trajectory, rising 182.4% year-on-year to ₹0.48 crore. Sequentially, however, the story was different. Revenue grew 13.7% from Q4 FY26, but profit inched up just 4.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ1 FY27 | PreviousQ4 FY26 | Same quarter LYQ1 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 0.58YoY +164% | 0.51 | 0.22 |
| Profit (₹ Cr) | 0.48YoY +182% | 0.46 | 0.17 |
Why profit growth hit the brakes
The slowdown came as total expenses jumped 31% quarter-on-quarter, outpacing the 13.7% revenue growth. This squeezed profitability, a trend the company attributed to operational scaling in its results filing. Employee costs fell, but other expenses rose significantly.
MarketsMojo reported the company delivered its highest-ever operating profit this quarter, indicating core performance is improving. However, the research firm also highlighted a fundamental weakness: a negative book value of ₹-3.52 crore, where liabilities exceed assets.
The margin pressure ahead
The broader NBFC sector faces a challenging interest rate environment. Analysis from Business Standard suggests net interest margins may come under pressure in the second half of FY27 as borrowing costs rise. For a company with a debt-to-equity ratio of 0.99, this external squeeze could limit future profit expansion.
Despite the cost pressure, the company has capital to deploy. It fully utilized a ₹10.64 crore preferential issue for working capital in May, according to an Alfafinder report. This provides fuel for the loan book growth driving the top line.
Key Points
- Revenue surged 164% year-on-year, but sequential profit growth slowed to 4.3% as expenses rose 31%.
- Core operating profit hit a record high, but a negative book value remains a fundamental concern flagged by MarketsMojo.
- The NBFC sector outlook points to potential margin pressure from rising funding costs in the coming quarters.
- The company recently utilized ₹10.64 crore in raised capital for working capital to support growth.
Hexa Perspective
The quarter shows Classic Leasing successfully scaling its operations, translating into dramatic year-on-year comparisons. The concern is that cost growth is already eating into that momentum on a sequential basis.
With the sector bracing for margin compression, the company's ability to manage its expense base and cost of funds will be critical. The recent capital raise provides a buffer, but investors are weighing strong operational gains against persistent balance sheet weaknesses and a premium valuation of 60% above the industry PE.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.