Brightcom Group (BCG) Q2 FY27's Profit Margin Shrinks as Costs Outrun Revenue
The digital ad firm posted 18% revenue growth but profit barely rose, as a broad-based cost surge ate into margins.
Brightcom Group's Q2 FY27 revenue grew 18% year-on-year, yet net profit only inched up 1.3% sequentially. A 36% jump in employee costs led a broad expense surge that compressed margins, raising questions about profitability sustainability.
For Brightcom Group, a digital advertising and technology firm, the September quarter was a story of top-line momentum meeting a stubborn cost wall. Revenue grew healthily, but profitability took a clear hit as expenses rose faster.
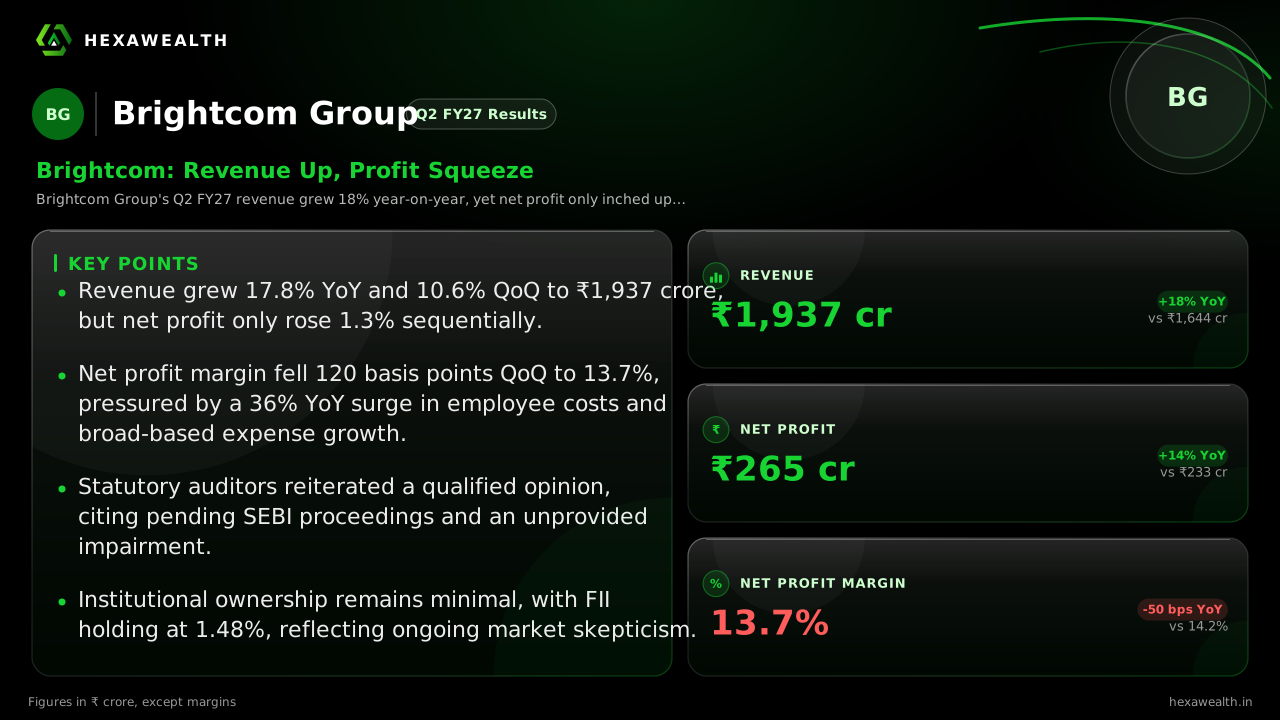
The numbers show a widening gap. Revenue for Q2 FY27 stood at ₹1,937 crore, up 17.8% from a year ago and 10.6% from the prior quarter. Net profit reached ₹265 crore, a 13.7% yearly gain but only a 1.3% sequential rise. This decoupling pulled the net profit margin down to 13.7%, from 14.9% last quarter and 14.2% a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 1,937.04 | 1,752.18 |
| Profit (₹ Cr) | 264.96 | 261.58 |
| Net Profit Margin (%) | 13.7 | 14.9 |
Why the margin shrank
The squeeze was broad-based. According to a report from Stockwatch, total expenses grew 19.9% year-on-year and 13.2% quarter-on-quarter, outpacing revenue growth on both counts. Employee costs surged 36.2% from a year ago, a significant driver of the pressure.
Growth came almost entirely from the core digital marketing segment, which contributed 94% of revenue, as per the same report. The standalone Indian parent entity reported near-break-even results, underscoring that profits are generated by overseas subsidiaries.
The governance overhang
Beyond operations, a persistent regulatory cloud remains. The company's statutory auditors again declined to give a conclusive opinion on the results. They cited a pending SEBI order on 'impairment of assets' and the company's non-provisioning of a ₹168.87 crore impairment on an investment, as noted in the Stockwatch analysis.
This governance overhang continues to weigh on institutional sentiment. Foreign institutional investor (FII) holding was just 1.48% at the end of September 2026, according to DalalOS data, having fallen sharply over several years.
Looking ahead
Management did not provide formal quarterly guidance. However, the board authorized a new Brightcom Defence demonstration facility in the US, signaling investment in new strategic divisions. The core ad-tech business operates in a still-growing global market, with WARC forecasting 8.4% growth in global ad spend for 2027.
The key question is whether the company can rein in cost growth to match its revenue trajectory. If expenses continue to outpace sales, the margin compression seen this quarter could become a trend.
Key Points
- Revenue grew 17.8% YoY and 10.6% QoQ to ₹1,937 crore, but net profit only rose 1.3% sequentially.
- Net profit margin fell 120 basis points QoQ to 13.7%, pressured by a 36% YoY surge in employee costs and broad-based expense growth.
- Statutory auditors reiterated a qualified opinion, citing pending SEBI proceedings and an unprovided impairment.
- Institutional ownership remains minimal, with FII holding at 1.48%, reflecting ongoing market skepticism.
Hexa Perspective
Brightcom's quarter underscores the tension between operational growth and legacy governance concerns. The business is generating substantial cash—trailing-twelve-month profit is over ₹1,000 crore—and is debt-free. Yet, the stock trades at a steep 91% discount to the industry PE, per the payload, a gap that speaks to persistent trust deficits more than financial metrics. The path to a re-rating requires two concurrent shifts: a demonstrated recovery in profit margins to their prior 14-15% range, and a resolution of the long-standing regulatory audits. Until then, the stock's deep value proposition remains locked behind a wall of skepticism that this quarter's numbers did little to dismantle.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.