Affordable Robotic & Automation (AFFORDABLE) Q2 FY27 Swings Back to Profit as Order Execution Accelerates
The robotics firm posted a ₹6.5 crore net profit in Q2 FY27, recovering from a loss, as revenue surged nearly fourfold sequentially on strong project execution.
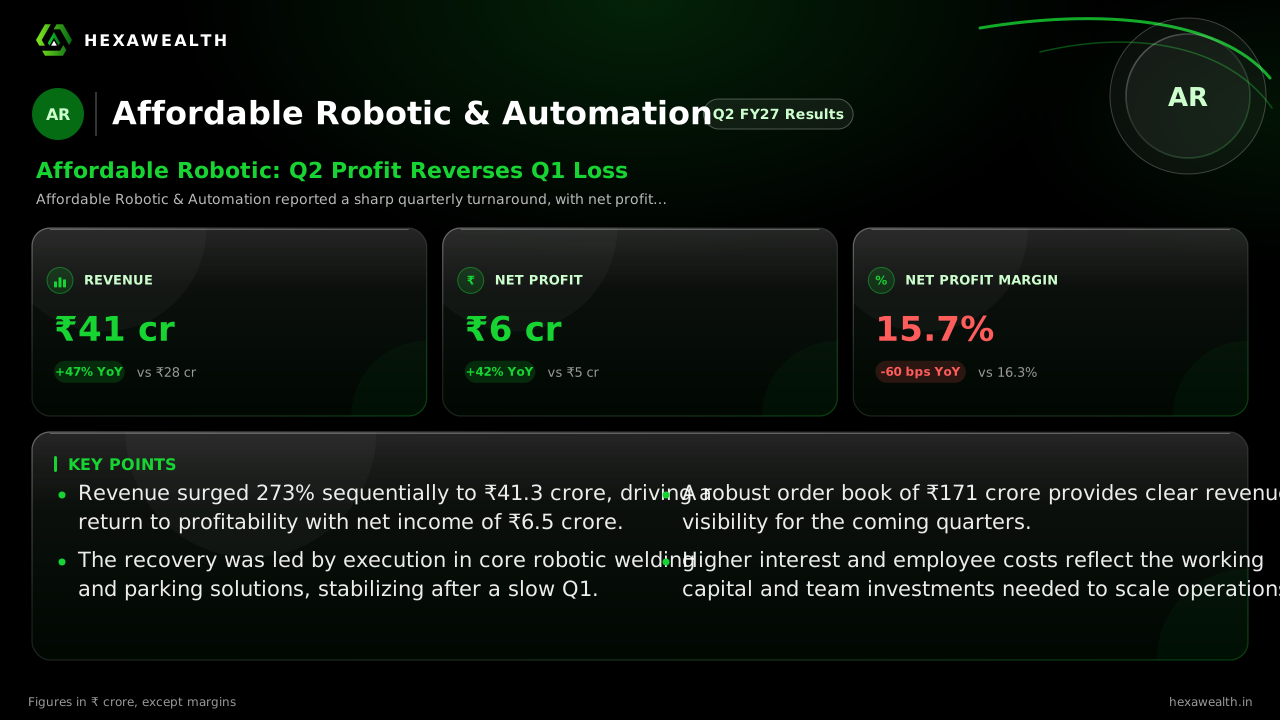
Affordable Robotic & Automation reported a sharp quarterly turnaround, with net profit reaching ₹6.5 crore in Q2 FY27. Revenue jumped 273% sequentially to ₹41.3 crore, driven by execution of its core automation and parking solution orders.
For a project-driven robotics company, a quiet quarter can mask the pipeline. Affordable Robotic & Automation's volatile start to FY27 gave way to a sharp execution rebound, proving its order book is more than promise.
The September quarter saw revenue surge to ₹41.3 crore, up 47% from a year ago and a massive 273% from the prior three months. Net profit landed at ₹6.5 crore, reversing a ₹4.8 crore loss in Q1. The swing back to a 15.7% net profit margin shows the operating leverage when projects move to site.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 41.34 | 11.09 |
| Profit (₹ Cr) | 6.47 | -4.80 |
| Net Profit Margin | 15.7% | -43.3% |
From a Loss to a Leveraged Win
The Q1 loss, as reported by Alfafinder, stemmed from delayed order execution and a timing shift of ₹13 crore in sales. Q2’s rebound was powered by stabilized demand in automated robotic welding and parking solutions. The revenue gain far outpaced a 149% rise in standalone costs, driving the margin recovery.
Financing the growth came at a cost. Consolidated interest expense nearly doubled year-on-year to ₹2.06 crore, reflecting higher working capital needs. Employee costs also rose 63% as the company scaled its Humro warehouse robotics team, according to Multibagg.ai.
The Backlog That Fuels the Runway
The real story is in the orders waiting. The company entered the second half with a confirmed order book of ₹171 crore, as per its AGM disclosure highlighted by Alfafinder. This includes a major ₹51.8 crore international contract for 103 robots and a new ₹19 crore domestic parking order.
Management, cited in a prior earnings call, had expected profitability to become visible from Q2 onward. With this execution rhythm set, the focus shifts to converting the remaining backlog. The key watchpoint is sustaining this quarterly run-rate against a lumpy project business.
Key Points
- Revenue surged 273% sequentially to ₹41.3 crore, driving a return to profitability with net income of ₹6.5 crore.
- The recovery was led by execution in core robotic welding and parking solutions, stabilizing after a slow Q1.
- A robust order book of ₹171 crore provides clear revenue visibility for the coming quarters.
- Higher interest and employee costs reflect the working capital and team investments needed to scale operations.
Hexa Perspective
The quarter confirms the operational model works when projects hit the execution phase. The 59-percentage-point quarter-on-quarter margin swing is dramatic, but it also highlights the inherent volatility.
The ₹171 crore order book, over four times the quarterly revenue, de-risks the near term. Yet, the 88% yearly jump in interest expense shows that funding this growth is already pressuring the bottom line. The next test is whether the company can maintain this pace of conversion without further margin sacrifice.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.