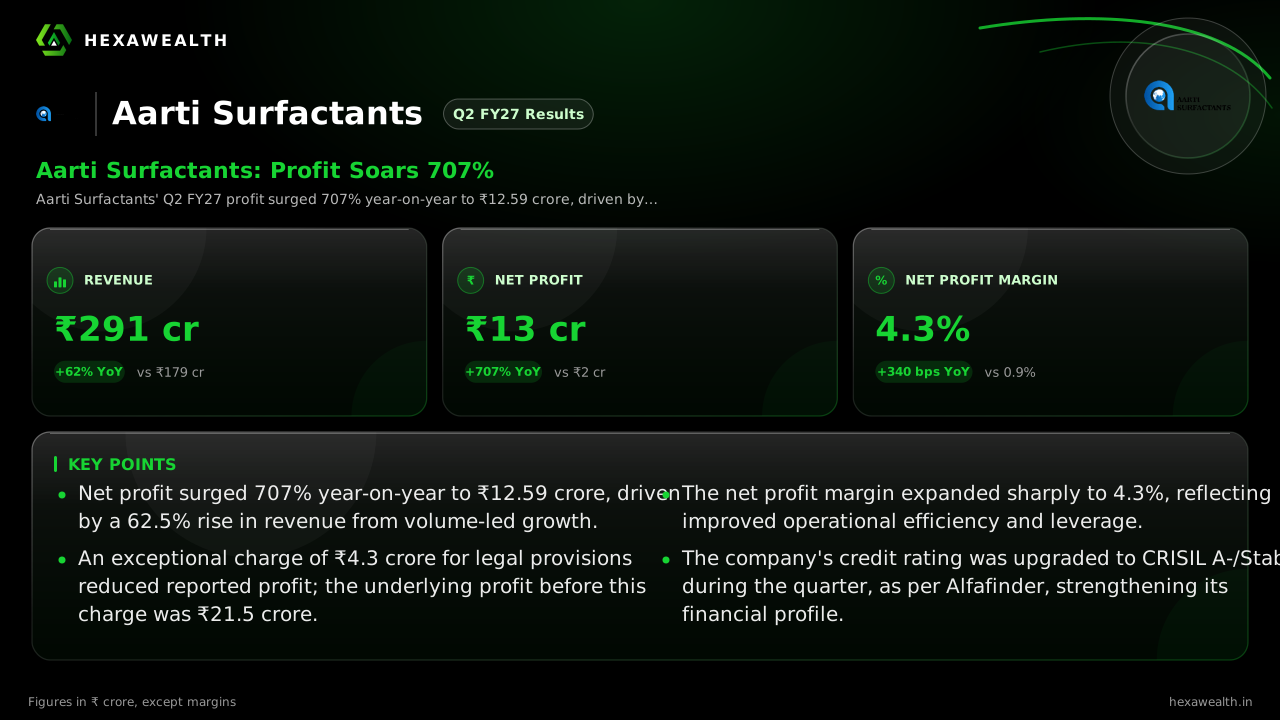
Aarti Surfactants (AARTISURF) Q2 FY27 Profit Soars 707% on Volume-Led Surge
The specialty chemicals maker posted a 62.5% revenue jump, with net profit leaping over sevenfold, though an exceptional charge trimmed the headline figure.
Aarti Surfactants' Q2 FY27 profit surged 707% year-on-year to ₹12.59 crore, driven by strong volume-led growth in its home and personal care ingredients segment. Operating margins expanded sharply, despite a one-off charge.
For Aarti Surfactants, the story this quarter is a sharp recovery from a low base, powered by volume. The home and personal care ingredients specialist saw revenue climb 62.5% year-on-year, a surge that Alfafinder reports was volume-led. This translated into a staggering 707% leap in net profit, showcasing significant operating leverage.
The numbers tell a clear story of sequential improvement. Revenue grew 6.7% from the June quarter, while profit jumped 39.9%. The net profit margin expanded to 4.3%, a 340 basis point improvement from a year ago and 100 basis points higher than last quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 291.24YoY +63% | 272.87 | 179.17 |
| Profit (₹ Cr) | 12.59YoY +707% | 9.00 | 1.56 |
| Net Profit Margin (%) | 4.3YoY +378% | 3.3 | 0.9 |
The One-Off That Trimmed the Win
Behind the headline profit lies a significant adjustment. The company recognized an exceptional charge of ₹4.3 crore, as noted by Alfafinder. This provision covered stamp duty for a demerger and customs penalties from a 2016 case.
Without this charge, profit before tax would have been ₹21.5 crore. This adjusted figure, cited by Alfafinder, shows an even stronger underlying operating performance, with profit before exceptional items and tax up 919% year-on-year.
A Cautious Backdrop for Growth
The strong operational print comes against a mixed industry canvas. A report from IIFL cited by CNBC-TV18 notes the chemicals sector recovery is selective, with specialty chemicals and import substitution being key drivers. This aligns with Aarti's volume-led domestic growth.
However, raw material inflation remains a watchpoint. Management commentary from a related Aarti Industries call, reported by Perivis, highlighted sharp increases in costs like sulfur. While Aarti Surfactants has managed margins this quarter, such input volatility is a persistent sector risk.
Key Points
- Net profit surged 707% year-on-year to ₹12.59 crore, driven by a 62.5% rise in revenue from volume-led growth.
- An exceptional charge of ₹4.3 crore for legal provisions reduced reported profit; the underlying profit before this charge was ₹21.5 crore.
- The net profit margin expanded sharply to 4.3%, reflecting improved operational efficiency and leverage.
- The company's credit rating was upgraded to CRISIL A-/Stable during the quarter, as per Alfafinder, strengthening its financial profile.
Hexa Perspective
The quarter marks a decisive turnaround from a weak period a year ago. The core narrative is one of volume recovery translating into powerful operating leverage, a trend that must hold for the momentum to be sustained.
The path ahead hinges on maintaining this volume growth against a backdrop of potential input cost pressure and selective sector demand. The company's ability to pass on costs and the health of domestic consumption in its end-markets will be the factors to watch in the coming quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.