Compucom Software (COMPUSOFT) Q2 FY27 Profit Stalls as Costs and Debt Bite
Compucom Software's Q2 FY27 revenue grew 3.5% year-on-year, but net profit was flat as a sharp margin squeeze and rising interest costs weighed on earnings.
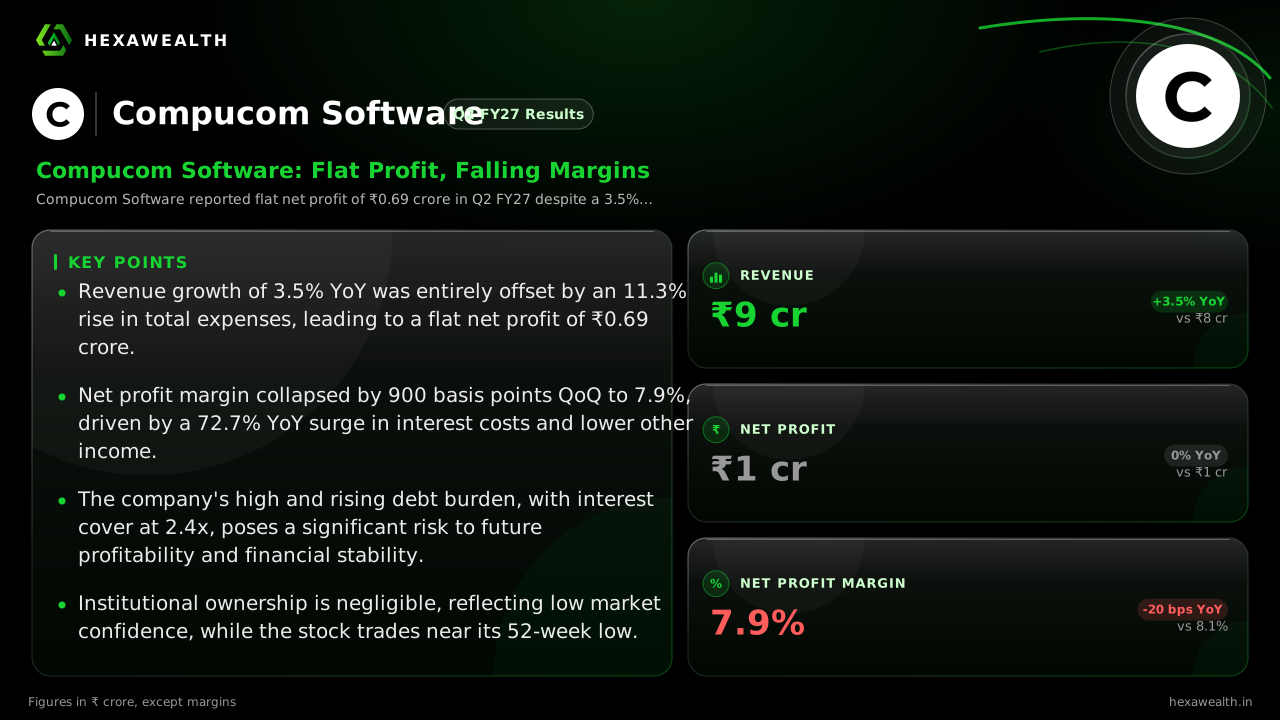
Compucom Software reported flat net profit of ₹0.69 crore in Q2 FY27 despite a 3.5% revenue rise. A 900 bps sequential margin contraction and a 72.7% jump in interest expense highlight significant cost pressures and a heavy debt burden.
For Compucom Software, a key player in Rajasthan's e-governance and ICT education projects, the September quarter was defined by a widening gap between top-line activity and bottom-line health. Revenue ticked up, but profitability collapsed under the weight of higher costs and a growing debt burden.
The numbers show a business struggling to convert sales into earnings. Revenue from operations rose 3.5% year-on-year to ₹8.77 crore and grew 8.7% sequentially. However, net profit was flat at ₹0.69 crore, masking a severe 49.6% quarter-on-quarter plunge.
The net profit margin tells the real story, contracting by a staggering 900 basis points from the previous quarter to just 7.9%. This sharp deterioration stems from two clear pressures. First, total expenses grew 11.3% year-on-year, outpacing revenue growth. Employee costs surged 27.8%, while depreciation rose 17.1%.
The Debt Drag on Profitability
The second, more critical pressure is finance costs, which soared 72.7% year-on-year to ₹0.96 crore. This reflects an elevated and rising debt burden. According to a MarketsMojo report, long-term debt stood at ₹21.65 crore as of March 2026, up significantly from ₹15.03 crore a year earlier.
This debt load creates a structural headwind. The company's interest cover ratio of 2.4x, as per the payload data, suggests operating profits are just sufficient to service interest, leaving little room for error. The report from MarketsMojo noted an EBIT-to-interest coverage of just 0.55x, indicating core operations are under severe strain.
Compounding the margin squeeze was a 30.3% sequential drop in other income to ₹1.24 crore. This decline removed a crucial prop for profitability. MarketsMoji highlighted that other income represented 238% of profit before tax this quarter, raising serious questions about the sustainability of earnings from core operations.
A Market Vote of No Confidence
The market's reaction to these results was muted but telling. The stock closed at ₹12.95 on November 13, near its 52-week low and down 27.4% over the past year. Institutional investors remain conspicuously absent, with mutual fund and FII holdings at zero, as noted in the research.
Looking ahead, the outlook hinges on managing its leveraged balance sheet. While Rajasthan's push for digital governance and education, detailed in reports from The BuckStopper and Circular Learnings, provides a steady demand backdrop, Compucom must demonstrate it can win projects profitably. Until it shows meaningful progress on debt reduction and cost control, earnings are likely to remain under pressure.
Key Points
- Revenue growth of 3.5% YoY was entirely offset by an 11.3% rise in total expenses, leading to a flat net profit of ₹0.69 crore.
- Net profit margin collapsed by 900 basis points QoQ to 7.9%, driven by a 72.7% YoY surge in interest costs and lower other income.
- The company's high and rising debt burden, with interest cover at 2.4x, poses a significant risk to future profitability and financial stability.
- Institutional ownership is negligible, reflecting low market confidence, while the stock trades near its 52-week low.
Hexa Perspective
The quarter reveals a business caught between modest government-led demand and a costly capital structure. The core issue is not revenue but capital efficiency: every rupee of new sales is being consumed by higher operating costs and interest payments.
For the strain to ease, Compucom needs to either generate significantly higher operating cash flows to pay down debt or refinance at lower rates. With a trailing-twelve-month net profit margin of 8.6% and a debt-to-equity of 0.34, the path to deleveraging through internal accruals looks challenging in the near term. Investors are right to question how long the company can rely on non-operational income to support its bottom line.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.