Apollo Pipes (APOLLOPIPE) Q2 FY27 Profit Dives 55% as Costs Swallow a 31% Revenue Surge
The piping firm's September quarter revenue jumped on higher volumes, but intense competition and raw material costs crushed its net profit to near zero.
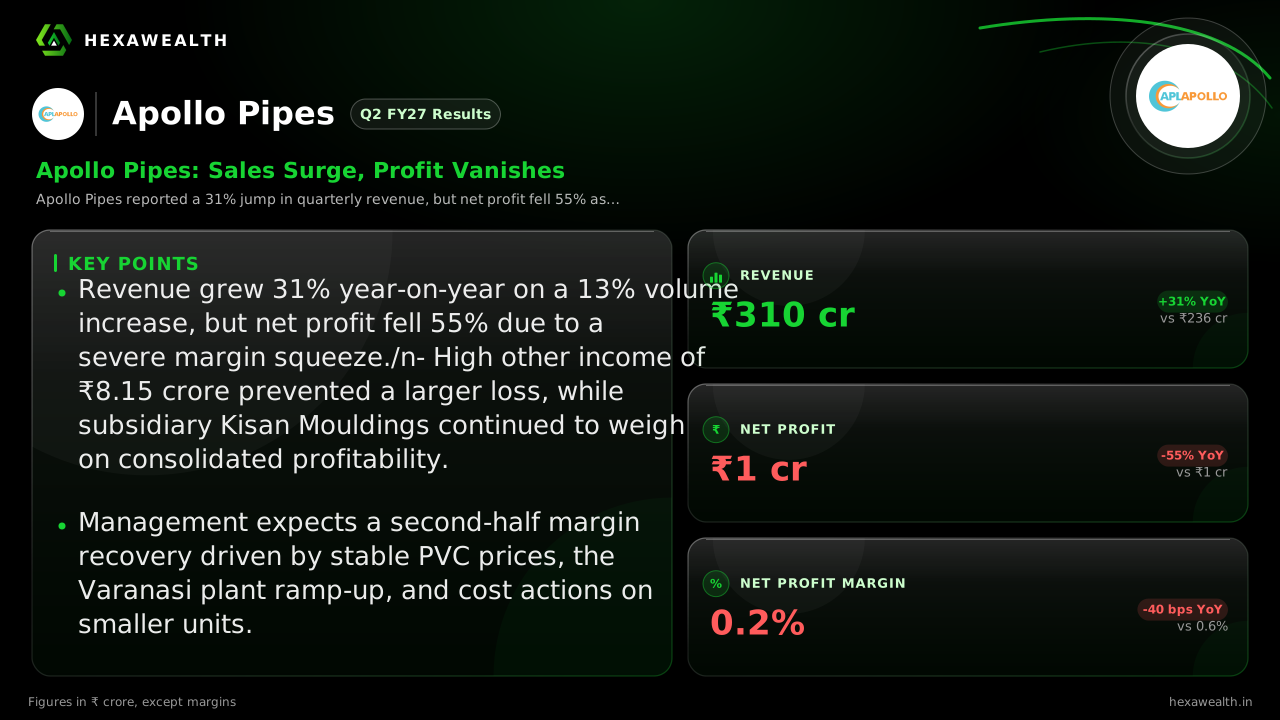
Apollo Pipes reported a 31% jump in quarterly revenue, but net profit fell 55% as expenses grew faster. Management targets a margin recovery in the second half, hinging on stabilizing PVC prices and new plant ramp-ups.
For Apollo Pipes, the September quarter was a story of two diverging lines. Demand for plastic pipes improved, pushing sales volumes up 13% year-on-year, according to the company's earnings call. Yet the bottom line tells a different tale, as intense competition and cost pressures prevented the company from turning that top-line momentum into profit.
The numbers lay it bare. Revenue grew 31.4% to ₹309.6 crore, but net profit collapsed 54.7% to just ₹0.63 crore. The net profit margin shrank to a wafer-thin 0.2%. Sequentially, the company swung from a ₹11.1 crore loss to a small profit, but that was largely due to a sharp jump in other income.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 309.64 | 295.44 |
| Profit (₹ Cr) | 0.63 | -11.12 |
| Net Profit Margin | 0.2% | -3.8% |
Why the growth never reached the bottom line
Total expenses surged 34% year-on-year, outpacing revenue growth. Employee costs and depreciation rose, but the core issue was raw material volatility. The AlphaStreet transcript notes management cited intense competition, which stopped them from passing on PVC resin cost increases to customers. This squeezed operating margins.
The profit figure itself was flattered by other income of ₹8.15 crore, which Pokharna Research notes accounted for 1199% of pre-tax profit. Without this one-off boost, the core business loss would have been deeper. The consolidated result was also dragged down by losses at the Kisan Mouldings subsidiary.
The path to a promised recovery
Management, on the AlphaStreet call, is banking on a better second half. They expect stabilizing PVC prices post-monsoon and benefits from the newly commissioned Varanasi plant to lift margins. The immediate target is to bring the standalone Apollo business to an EBITDA of ₹9,000-10,000 per tonne in H2 FY27, up from ₹7,000 in Q2.
The bigger challenge is fixing the Kisan brand, which posted a per-tonne EBITDA loss. The goal is to bring it to breakeven in the next six to nine months. The company also plans to shut smaller, inefficient units in Ahmedabad and Raipur to improve overall spreads.
A valuation waiting for earnings
Investors have shown patience, with the stock returning over 71% in the past year. This has pushed the valuation to a steep premium, with a P/E of 244 against an industry average of 34. The market is pricing in a sharp earnings recovery that these quarterly numbers have yet to deliver.
Key Points
- Revenue grew 31% year-on-year on a 13% volume increase, but net profit fell 55% due to a severe margin squeeze./n- High other income of ₹8.15 crore prevented a larger loss, while subsidiary Kisan Mouldings continued to weigh on consolidated profitability.
- Management expects a second-half margin recovery driven by stable PVC prices, the Varanasi plant ramp-up, and cost actions on smaller units.
Hexa Perspective
The quarter confirms Apollo Pipes is stuck in a competitive commodity cycle. Sales volumes are responding to demand, but pricing power is absent. The promised second-half margin improvement is plausible but not assured—it requires PVC prices to stay stable and the new plant to ramp up smoothly.
The high valuation premium suggests the market has already priced in a successful turnaround. For that bet to pay off, the company must quickly demonstrate it can convert its revenue growth into sustainable profit, a feat it has not managed in recent quarters. The next six months are critical.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.