AMPL Capital Q1 FY27's Q1 Profit Plunges Despite 82% Revenue Growth
The NBFC's revenue surged 81.6% year-on-year, but a sharp rise in interest costs and one-off consolidation impacts pushed it into a net loss.
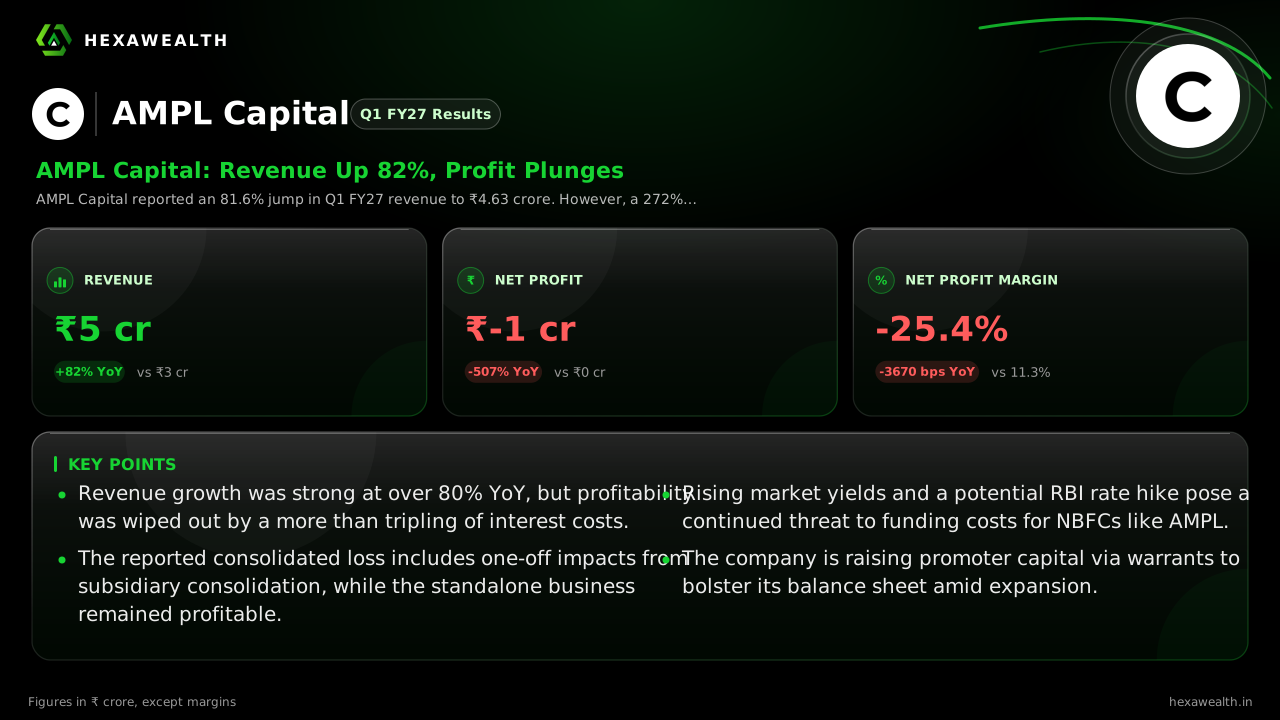
AMPL Capital reported an 81.6% jump in Q1 FY27 revenue to ₹4.63 crore. However, a 272% surge in interest expense and one-off consolidation costs led to a net loss of ₹1.18 crore, reversing last year's profit.
For AMPL Capital, a rebranded NBFC pivoting towards capital markets, the June quarter tested its transition. While revenue jumped sharply, profitability collapsed under the weight of a transformed cost structure.
The numbers tell a story of divergence. Revenue rose 81.6% year-on-year to ₹4.63 crore and grew 51.8% sequentially. Yet, the company swung to a net loss of ₹1.18 crore from a profit of ₹0.29 crore a year ago. The net profit margin fell to -25.4% from 11.3% in Q1 FY26.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ1 FY27 | PreviousQ4 FY26 | Same quarter LYQ1 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 4.63YoY +82% | 3.05 | 2.55 |
| Profit (₹ Cr) | -1.18YoY -507% | 0.01 | 0.29 |
| Net Profit Margin (%) | -25.4YoY -325% | 0.2 | 11.3 |
Why the bottom line turned red
A 272% year-on-year surge in interest expense to ₹1.83 crore was the primary driver of the loss. This reflects a higher borrowing base as the company funds growth. According to a report by JM Financial, NBFCs are facing rising funding costs as market yields increase and expectations of a policy rate hike build.
Compounding this, the consolidated result was hit by one-off impacts from a sold step-down subsidiary, as noted by Multibagg.ai. This explains why standalone operations remained profitable with a PAT of ₹0.82 crore, while the consolidated entity reported a loss.
The funding cost challenge
With bank borrowings forming a larger share of NBFC liabilities, any rate increase now feeds faster into overall costs. The company's recent ₹22.8 crore preferential warrant issue to promoters aims to strengthen the balance sheet. However, the interest burden from an expanding loan book is a near-term pressure that won't recede quickly.
Foreign institutional investors seem cautious, reducing their stake from 16.51% in February to 8.05% by September 2026, per Upstox data. MarketsMojo maintains a 'Hold' rating, citing attractive valuation but average quality.
Key Points
- Revenue growth was strong at over 80% YoY, but profitability was wiped out by a more than tripling of interest costs.
- The reported consolidated loss includes one-off impacts from subsidiary consolidation, while the standalone business remained profitable.
- Rising market yields and a potential RBI rate hike pose a continued threat to funding costs for NBFCs like AMPL.
- The company is raising promoter capital via warrants to bolster its balance sheet amid expansion.
Hexa Perspective
The quarter highlights the acute margin squeeze in AMPL's pivot. Revenue growth is evident, but it is being funded by expensive debt, eroding the core lending margin. The one-off consolidation cloud will pass, but the structural rise in funding costs may persist.
Investors are weighing a cheap valuation—the stock trades at a 48% discount to the industry PE—against a profitability model under pressure. The success of its fee-based asset management and advisory arms in offsetting this pressure will decide the next few quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.