Ambalal Sarabhai (AMBALALSA) Q2 FY27 Profit Crashes 83% Despite 33% Revenue Jump
The pharmaceutical firm's September quarter saw a sharp disconnect as surging costs erased profits, raising questions about earnings quality and operational efficiency.
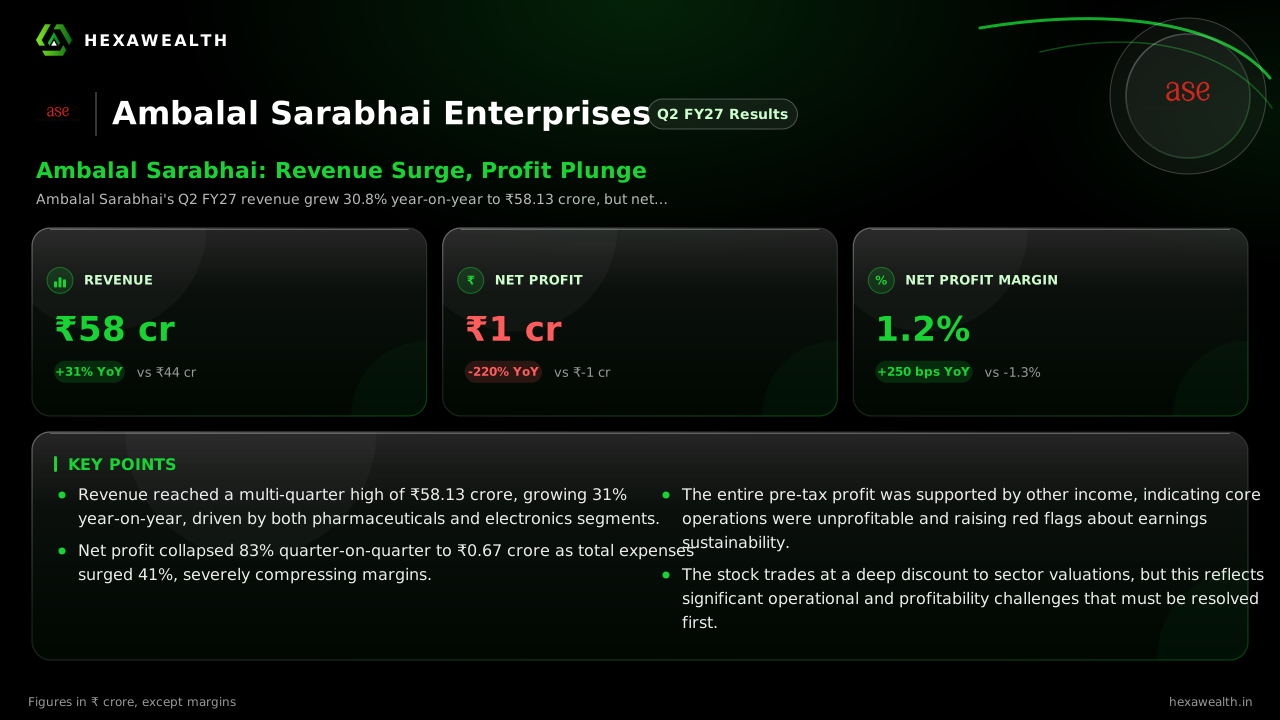
Ambalal Sarabhai's Q2 FY27 revenue grew 30.8% year-on-year to ₹58.13 crore, but net profit plunged 83% sequentially to ₹0.67 crore. A severe margin squeeze, with other income covering the entire pre-tax profit, highlights deep operational challenges.
For Ambalal Sarabhai Enterprises, the September quarter presented a stark contradiction. The diversified pharma and electronics group posted its highest quarterly revenue in recent periods, yet delivered one of its weakest profit performances. The 83% sequential profit collapse reveals a business where top-line momentum is failing to reach the bottom line.
The numbers tell a story of growth without reward. Revenue climbed 30.8% year-on-year and 33.4% quarter-on-quarter to ₹58.13 crore. However, net profit crashed to just ₹0.67 crore, an 83% drop from the previous quarter. The net profit margin collapsed by 790 basis points to a thin 1.2%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 58.13 | 43.56 |
| Profit (₹ Cr) | 0.67 | 3.98 |
| Net Profit Margin (%) | 1.2 | 9.1 |
The Costs That Erased the Gains
Where did the profit go? Total expenses surged 40.8% from the June quarter, far outpacing revenue growth. Employee costs rose to ₹8.71 crore, according to a MarketsMojo report, suggesting wage pressures or higher headcount. The operating margin, excluding other income, contracted sharply to just 4.1% from 10.4% in Q1.
This cost surge hit both core segments. The pharmaceuticals division reported revenue of ₹34.89 crore, while electronics brought in ₹23.28 crore, as per Whalesbook. Yet, profitability in both segments was under pressure, with a Flash Finance analysis noting the core business generated virtually no profit before other income.
An Earnings Quality Warning
The most concerning signal is the source of the meagre profit that remained. Other income of ₹1.39 crore accounted for 105% of the pre-tax profit of ₹1.31 crore. This means the company's core operations would have posted a loss without this non-operating cushion. MarketsMojo flagged this as a serious deterioration in earnings quality.
With no specific management guidance cited in the research, the onus is on execution. The stock traded at ₹35.25 on the results day, down 2.1%, reflecting investor concern over this operational disconnect. The company trades at a P/E of 10.4, a steep 73% discount to the industry average, but the valuation gap speaks to the perceived risk.
Key Points
- Revenue reached a multi-quarter high of ₹58.13 crore, growing 31% year-on-year, driven by both pharmaceuticals and electronics segments.
- Net profit collapsed 83% quarter-on-quarter to ₹0.67 crore as total expenses surged 41%, severely compressing margins.
- The entire pre-tax profit was supported by other income, indicating core operations were unprofitable and raising red flags about earnings sustainability.
- The stock trades at a deep discount to sector valuations, but this reflects significant operational and profitability challenges that must be resolved first.
Hexa Perspective
The quarter frames a clear challenge: Ambalal Sarabhai can generate demand but cannot currently convert it into quality earnings. The severe margin compression suggests either a one-time cost spike or a deeper inefficiency that revenue growth alone cannot fix.
The path forward hinges on restoring operational discipline. Investors are effectively paying for a turnaround that has yet to materialize. The low debt and attractive valuation provide a margin of safety, but they are not catalysts. The next few quarters must show whether management can stem the profit leakage and prove the revenue story is more than just top-line noise.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.