Alan Scott Enterprises (ALANSCOTT) Q2 FY27 Losses Widen as Costs Outpace Revenue
Despite a 5.4% rise in revenue, a sharp jump in employee costs and depreciation pushed the net loss to ₹2.15 crore in the September quarter.
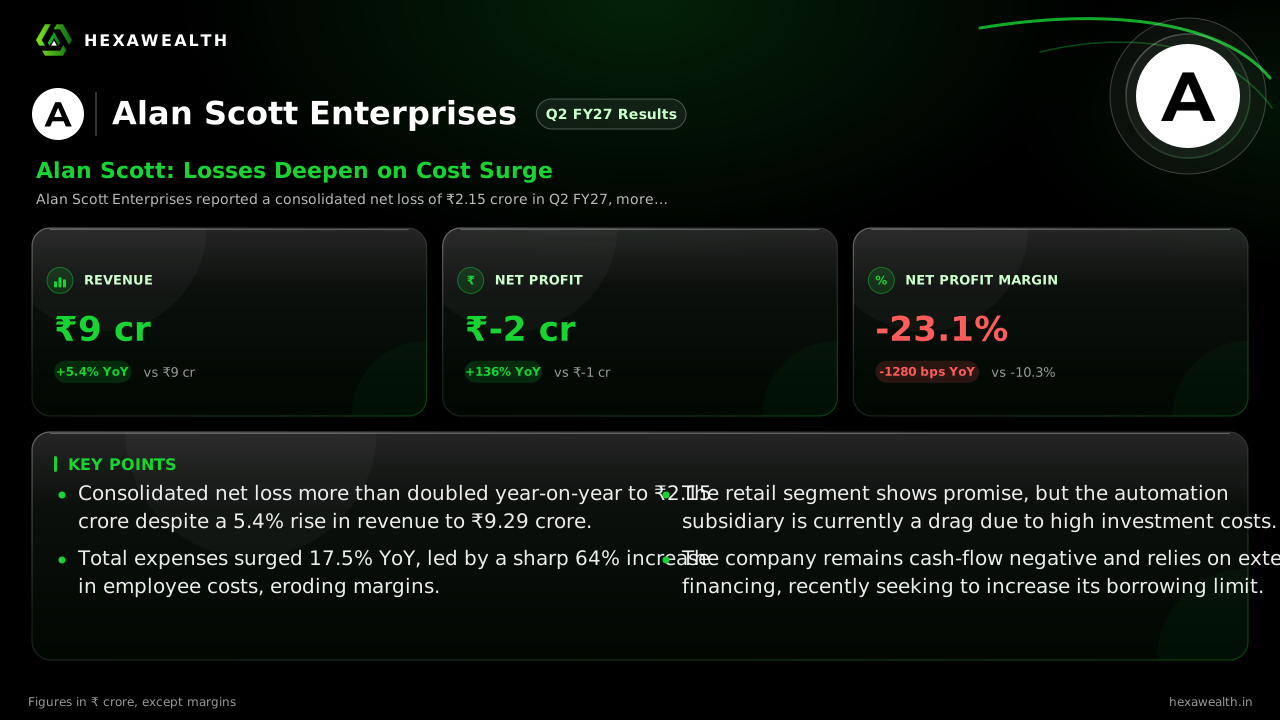
Alan Scott Enterprises reported a consolidated net loss of ₹2.15 crore in Q2 FY27, more than doubling from last quarter. Revenue grew modestly to ₹9.29 crore, but was overwhelmed by a 17.5% surge in total expenses year-on-year.
For Alan Scott Enterprises, a holding company with ambitions in retail and automation, the September quarter was a story of growing sales but vanishing profits. Revenue inched up, but a surge in operational costs pushed losses to their widest point in over a year, highlighting the challenge of scaling disparate businesses profitably.
The numbers show a clear divergence. Revenue for Q2 FY27 reached ₹9.29 crore, a 5.4% increase from the same period last year. However, the net loss deepened to ₹2.15 crore, more than doubling both year-on-year and sequentially. The net profit margin collapsed to -23.1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 9.29YoY +5.4% | 9.12 | 8.81 |
| Profit (₹ Cr) | -2.15YoY -136% | -0.85 | -0.91 |
| Net Profit Margin (%) | -23.1YoY -124% | -9.3 | -10.3 |
The Cost Surge That Sank the Bottom Line
The primary driver of the wider loss was a 17.5% year-on-year jump in total expenses, far outpacing revenue growth. A MarketsMojo report attributed this to a 64% surge in employee costs, which hit ₹2.35 crore. Depreciation also rose 25% quarter-on-quarter, likely linked to investments in its automation subsidiary.
Compounding the pressure, other income fell to zero from ₹0.05 crore in the prior quarter, removing a minor buffer. The result was an operating loss, a stark reversal from a profit in the year-ago quarter.
A Retail Bright Spot Amid Automation Struggles
Segmentally, the story is mixed. Research from an investor presentation cited by Arthneeti.com indicates the retail business, operating Miniso franchises, is a relative bright spot. It reportedly drove growth and aims to scale from 15 to 20 stores.
In contrast, the automation and robotics division, while holding an order book, is in a heavier investment phase. This explains the rising depreciation and its current drag on consolidated profits.
Cash Burn and a Speculative Valuation
The financial strain is evident beyond the profit statement. A MarketsMojo analysis of the FY26 cash flow showed the core business burned cash, relying on financing activities to fund operations. Despite this, the stock trades at a significant premium, with a price-to-book value of 17x noted as exceptionally high for a loss-making firm.
Management has not provided forward profitability guidance, focusing instead on capital-raising and subsidiary scaling. The company recently sought approval to double its borrowing limit to ₹50 crore, signaling a continued need for funding its expansion plans.
Key Points
- Consolidated net loss more than doubled year-on-year to ₹2.15 crore despite a 5.4% rise in revenue to ₹9.29 crore.
- Total expenses surged 17.5% YoY, led by a sharp 64% increase in employee costs, eroding margins.
- The retail segment shows promise, but the automation subsidiary is currently a drag due to high investment costs.
- The company remains cash-flow negative and relies on external financing, recently seeking to increase its borrowing limit.
Hexa Perspective
The quarter underscores the execution risk in Alan Scott's holding-company model. Revenue growth is positive but anemic, while costs are rising sharply as it builds out new verticals. The path to profitability hinges on the retail business scaling profitably enough to offset losses in automation, which may take several more quarters. Investors are faced with a speculative bet on future subsidiary valuations, as current fundamentals—persistent losses, cash burn, and a rich valuation—do not support the stock price. The lack of management guidance on cost control or a timeline to breakeven adds to the uncertainty.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.