Advance Technoforge (ADVANCETL) Q2 FY27 Profit Jumps 70% as Revenue Soars, But Margin Pressure Emerges
The forging company posted a 66% surge in revenue and a 70% jump in net profit year-on-year for Q2 FY27, though margins softened sequentially on higher costs.
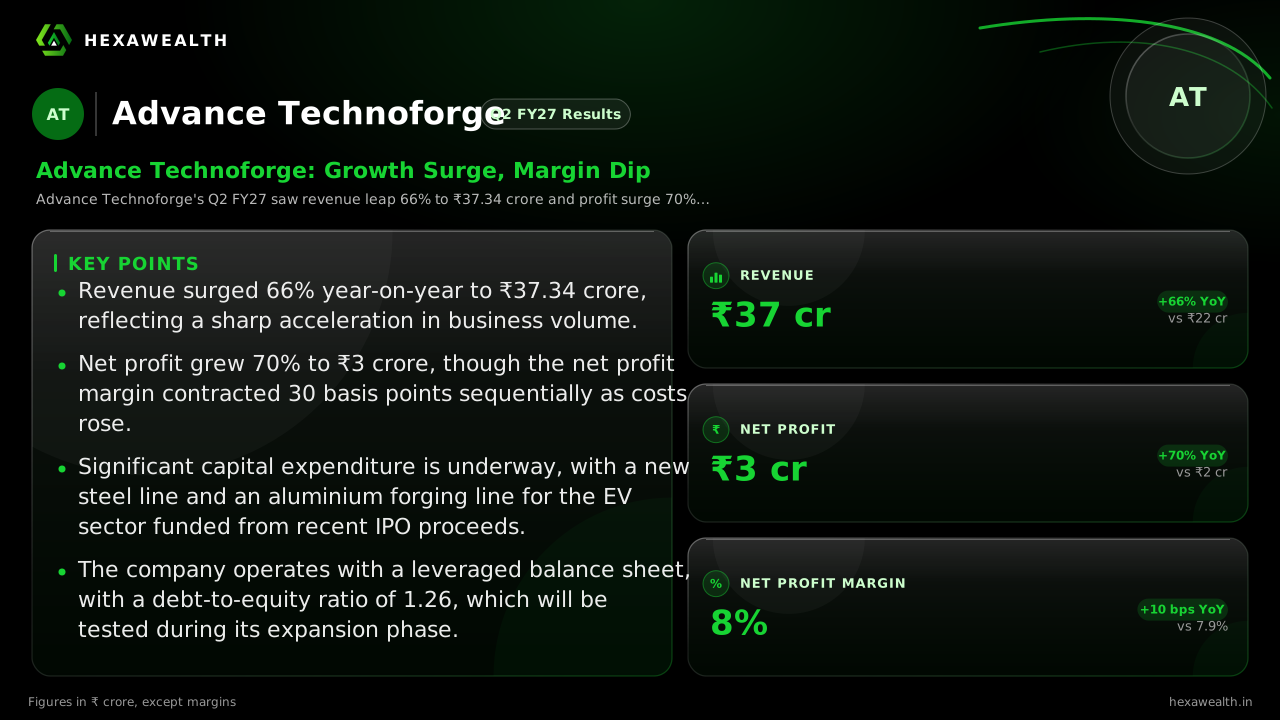
Advance Technoforge's Q2 FY27 saw revenue leap 66% to ₹37.34 crore and profit surge 70% to ₹3 crore. While growth is robust, a sequential margin dip points to rising costs as the company expands capacity.
For a capital-intensive forger running at half its installed capacity, the story is always about filling the plant. Advance Technoforge’s second quarter delivered exactly that, with revenue surging 66% year-on-year to ₹37.34 crore. Net profit followed closely, jumping 70% to ₹3 crore, as the company began to convert its idle presses into sales.
The numbers show a business accelerating from a low base. Compared to the March quarter, revenue grew 35% and profit 31%. A look at the recent trajectory puts the scale of the current uptick in context.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Period | Sep 2026 | Sep 2025 |
| Revenue (₹ Cr) | 37.34YoY +66% | 22.45 |
| Profit (₹ Cr) | 3.00YoY +69% | 1.77 |
| Net Profit Margin | 8.0%YoY +1.3% | 7.9% |
The cost of filling the presses
Growth came with a clear trade-off. While the annual profit margin improved slightly, it dipped 30 basis points from the previous quarter to 8%. According to a Multibagg.ai analysis, total expenses rose in lockstep with revenue, up 68% year-on-year. The cost of materials consumed, the largest expense, rose 62%.
A 155% year-on-year surge in depreciation, noted in the filings, signals new assets coming online. This aligns with the company's plan, cited in its July prospectus, to start a fourth steel hammer line by end-FY27. The capacity expansion is working, but it carries a near-term cost.
Where the growth is headed
Management has not provided formal guidance, but the strategic path is clear from its IPO documents. The company is using issue proceeds to fund a new 600-tonne aluminium forging line for electric vehicle parts. This diversifies its product base beyond traditional steel forgings.
The broader sector tailwinds are supportive. Research from Kyro Ventures highlights strong demand drivers from defence, railways, and a potential forging capacity shortage in India. Europe's struggling forging industry is also shifting orders to qualified Indian suppliers.
The balance sheet stretch
Financing this growth has meant leaning on debt. The company's debt-to-equity ratio stands at 1.26, as per StockFin data. While borrowings have been stable recently, interest expense remains a meaningful line item. The planned capacity additions will test its ability to manage working capital and funding costs.
Key Points
- Revenue surged 66% year-on-year to ₹37.34 crore, reflecting a sharp acceleration in business volume.
- Net profit grew 70% to ₹3 crore, though the net profit margin contracted 30 basis points sequentially as costs rose.
- Significant capital expenditure is underway, with a new steel line and an aluminium forging line for the EV sector funded from recent IPO proceeds.
- The company operates with a leveraged balance sheet, with a debt-to-equity ratio of 1.26, which will be tested during its expansion phase.
Hexa Perspective
The quarter confirms Advance Technoforge is successfully unlocking its underutilised capacity, turning fixed assets into revenue. The 66% sales jump is the central fact. Yet, the margin compression shows this growth isn't free—costs are rising nearly as fast.
The next few quarters will show if this is a temporary squeeze as new lines ramp up, or a structural shift as the business mix changes. With a high debt load and ambitious capex, the company needs the current sector demand strength to hold. Investors are betting the capacity it's adding today will be needed tomorrow.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.