Data Patterns (DATAPATTNS) Q2 FY27 Profit Dives 56% as Project Delays Bite
The defence electronics firm's Q2 revenue fell 57% year-on-year to ₹133 crore, with profit down 56%, missing analyst estimates amid project execution delays.
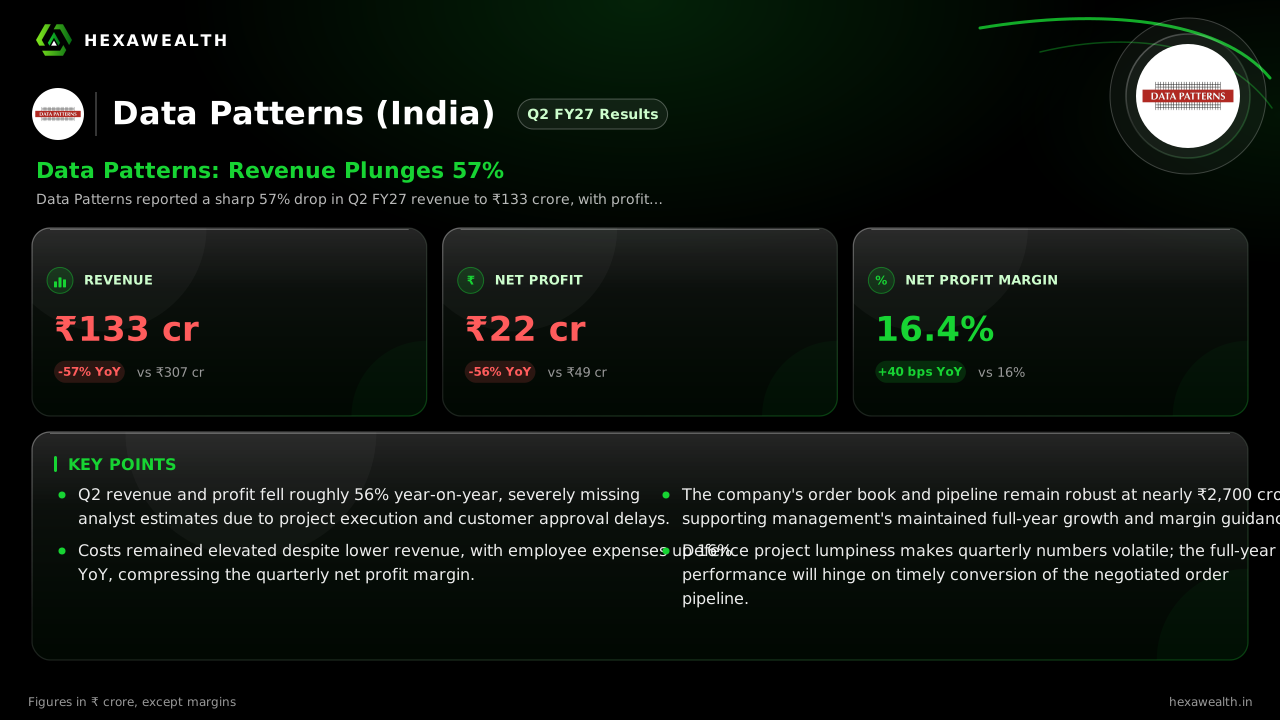
Data Patterns reported a sharp 57% drop in Q2 FY27 revenue to ₹133 crore, with profit halving to ₹22 crore. The steep decline reflects the lumpy nature of defence project execution and delays in customer approvals.
For a defence electronics firm, quarterly revenue is less a measure of demand than a snapshot of project milestones. Data Patterns entered its second quarter with a strong order book but a history of customer approval delays. The result was a sharp contraction, as revenue recognition lagged far behind expectations.
The numbers show a steep year-on-year fall. Consolidated revenue dropped 56.7% to ₹133.25 crore, while profit after tax fell 55.6% to ₹21.82 crore. Sequentially, revenue rose 14.8% from a weak June quarter, but profit was nearly flat, squeezing the net margin by 260 basis points to 16.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 133.25YoY -57% | 116.03 | 307.46 |
| Profit (₹ Cr) | 21.82YoY -56% | 22.06 | 49.19 |
| Net Margin (%) | 16.4YoY +2.5% | 19.0 | 16.0 |
The print was a stark miss against analyst forecasts. Motilal Oswal had estimated revenue of ₹369 crore and adjusted net profit of ₹84.5 crore, as reported by multibagg.ai. The actual figures were less than half those projections, highlighting the volatility inherent in project-based execution.
Why the quarter fell short
Management attributed the weakness to a strong comparable base and ongoing execution delays. Chairman Srinivasagopalan Rangarajan noted Q2 FY26 had seen robust execution, making for a tough comparison. More critically, customer inspection and approval delays that affected Q1 spilled over, deferring revenue recognition into future periods.
Costs did not fall in line with the revenue drop. Employee benefits expense rose 16.4% year-on-year to ₹44.10 crore, as the company continued to invest in technical talent. Depreciation also increased 25%, reflecting ongoing capital expenditure for new facilities and testing equipment.
The backlog that underpins the outlook
The near-term pain is set against a formidable order pipeline. The company reported an order book of ₹1,742 crore, with negotiated orders worth another ₹956 crore, bringing the total executable pipeline to nearly ₹2,700 crore. Fresh orders of ₹929 crore were received in Q2.
This provides multi-year revenue visibility. Management has retained its full-year guidance for 25% revenue growth and an EBITDA margin of 35-40%, as noted by multibagg.ai. The expectation is for a much stronger second half as delayed projects clear approvals and execution accelerates.
Key Points
- Q2 revenue and profit fell roughly 56% year-on-year, severely missing analyst estimates due to project execution and customer approval delays.
- Costs remained elevated despite lower revenue, with employee expenses up 16% YoY, compressing the quarterly net profit margin.
- The company's order book and pipeline remain robust at nearly ₹2,700 crore, supporting management's maintained full-year growth and margin guidance.
- Defence project lumpiness makes quarterly numbers volatile; the full-year performance will hinge on timely conversion of the negotiated order pipeline.
Hexa Perspective
The quarter underscores the execution risk priced into defence stocks. While the ₹2,700 crore pipeline offers clear long-term visibility, the market is now weighing the reliability of conversion timelines. The maintained guidance signals management confidence, but it requires a significant step-up in H2 revenue.
Investors are left balancing a strong strategic position against quarterly volatility. The stock's rich valuation—trading at a significant premium to the industry—demands consistent execution. The next few quarters will test whether the current delays are merely timing issues or point to deeper systemic challenges in project delivery.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.