Amrapali Capital (ACFSL) Q4 FY26's Revenue Jumps 17,500% but Profit Margin Vanishes
The financial services firm posted a staggering revenue increase in Q4 FY26, yet its net profit margin fell to zero, highlighting a massive cost surge.
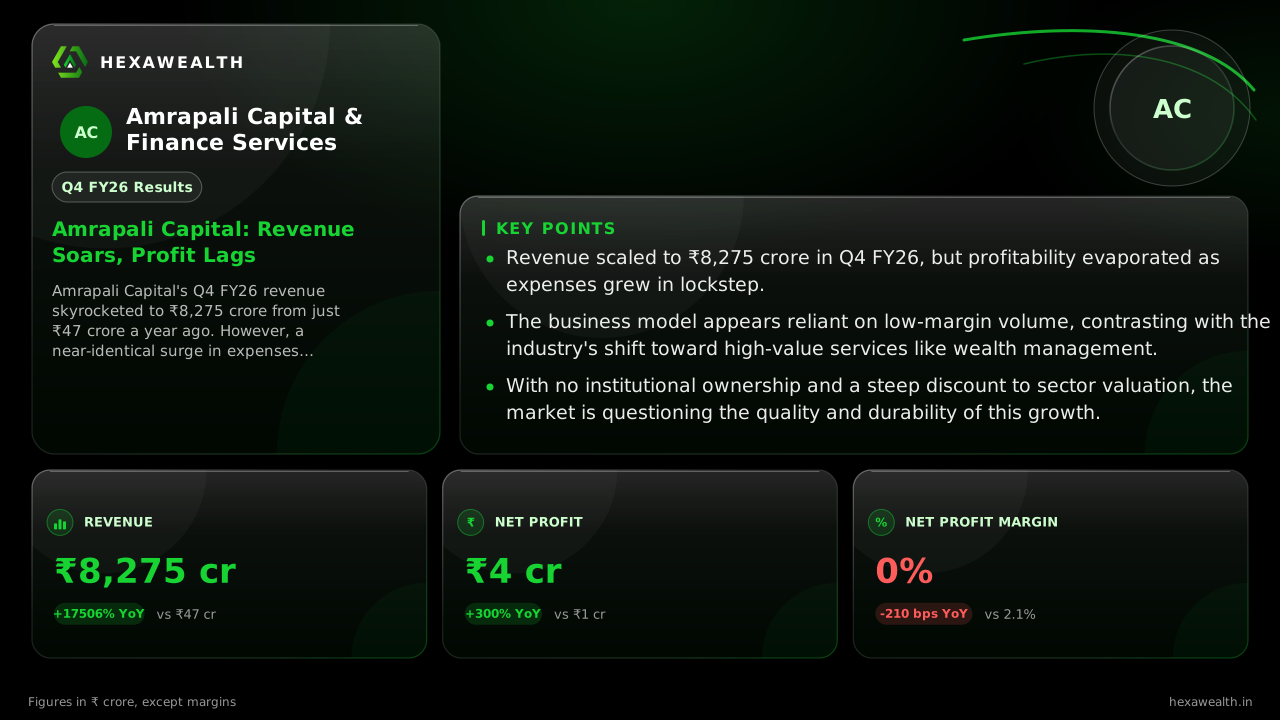
Amrapali Capital's Q4 FY26 revenue skyrocketed to ₹8,275 crore from just ₹47 crore a year ago. However, a near-identical surge in expenses erased profitability, leaving the net profit margin at 0%.
For Amrapali Capital, a small financial services player, Q4 FY26 was a quarter of extreme scale. The reported numbers show a business transformed overnight, but the underlying economics tell a more complex story of growth without immediate reward.
Revenue for the March 2026 quarter exploded to ₹8,275 crore, a staggering 17,506% leap from the ₹47 crore reported a year earlier. Profit grew 300% to ₹4 crore, but the net profit margin collapsed to 0% from 2.1% in Q4 FY25. The full year mirrored this, with revenue at ₹8,273 crore and profit at ₹5 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 8,275.0YoY +17506% | 47.0 |
| Profit (₹ Cr) | 4.0YoY +300% | 1.0 |
| Net Profit Margin (%) | 0.0YoY -100% | 2.1 |
Why the profit vanished
A 17,883% year-on-year surge in total expenses to ₹8,276 crore completely matched the revenue jump. According to data from Stockscans.in, operating profit for the quarter was essentially zero. This suggests the revenue surge was not from high-margin broking but likely from a large, low-margin transaction or balance sheet reclassification.
Management, cited by StockFin.ai, emphasized a strategic focus on digital transformation and retail investor growth. Yet, the clean audit report and lack of a dividend signal all earnings are being retained for this expansion.
The industry's shifting sands
This comes as the broking industry faces a fundamental shift. Analysis from DSIJ Insights notes zero-brokerage wars have compressed pure transaction margins, forcing firms toward wealth management and lending for stable income. Amrapali's valuation, at a P/E of 14.1, trades at a 68% discount to the industry average of 43.7, reflecting skepticism about the sustainability of its new scale.
Key Points
- Revenue scaled to ₹8,275 crore in Q4 FY26, but profitability evaporated as expenses grew in lockstep.
- The business model appears reliant on low-margin volume, contrasting with the industry's shift toward high-value services like wealth management.
- With no institutional ownership and a steep discount to sector valuation, the market is questioning the quality and durability of this growth.
Hexa Perspective
The quarter presents a paradox of scale without substance. The astronomical revenue growth is mechanically impressive but operationally hollow, with margins wiped out. For this to translate into sustainable value, the capital being retained must fund a genuine pivot into higher-margin services like margin financing or distribution. Until then, the headline numbers are a balance sheet event, not an earnings story. The coming quarters will reveal if this was a one-time rebalancing or the start of a fundamentally different, but still unprofitable, business.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.