ADF Foods (ADFFOODS) Q2 FY27 Profit Dips 4% Despite Record ₹200 Crore Revenue
The ethnic food exporter posted its highest-ever quarterly sales but saw margins contract sharply as costs rose faster than prices.
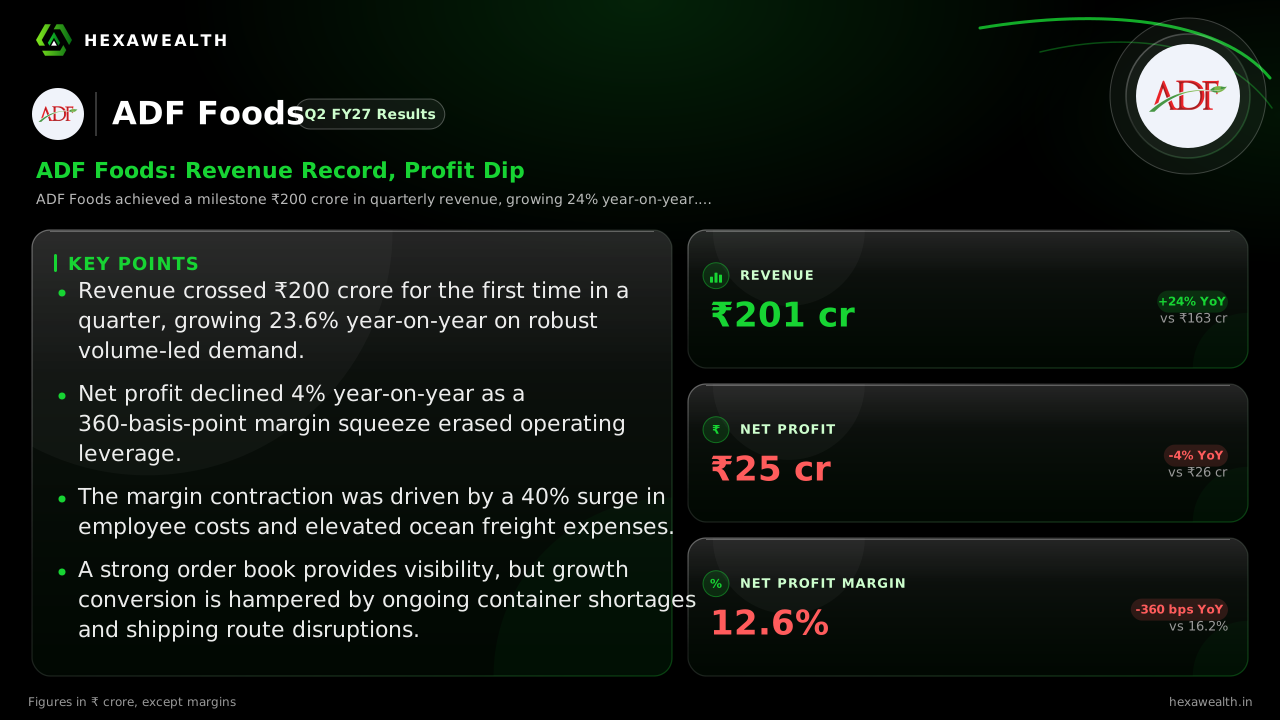
ADF Foods achieved a milestone ₹200 crore in quarterly revenue, growing 24% year-on-year. However, net profit fell 4% as elevated freight and employee costs squeezed margins, highlighting a profitability challenge.
For ADF Foods, the story of Q2 FY27 is one of demand meeting its limits. The ethnic food exporter crossed the ₹200 crore quarterly revenue mark for the first time, a milestone driven by deep international appetite. Yet, the profit line tells a different tale, contracting from a year ago as the cost of delivering that growth bit hard.
The numbers show the split. Revenue surged 23.6% year-on-year to ₹200.91 crore, also marking a strong 20.1% sequential rebound. Profit, however, slipped 4% to ₹25.34 crore. The net profit margin compressed by 360 basis points to 12.6%, revealing the pressure underneath the headline sales win.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 200.91 | 167.29 |
| Profit (₹ Cr) | 25.34 | 17.29 |
| Net Profit Margin (%) | 12.6 | 10.3 |
The costs that ate the growth
Two expense lines explain most of the margin squeeze. Employee costs jumped nearly 40% year-on-year, far outpacing revenue growth, as the company built teams for expansion. Simultaneously, elevated ocean freight and persistent container shortages, noted in the AlphaStreet transcript, added significant logistics pressure.
Management stated these costs were partly mitigated through operating efficiencies. However, the 29% drop in other income, reported by Blacklitt, provided no buffer this quarter. The result was a profit before tax that was essentially flat year-on-year, eroding all the operating leverage from record sales.
A strong order book meets shipping snarls
The underlying demand story remains robust. The company's order book is strong, led by its flagship Ashoka brand and deeper penetration in the US through the Truly Indian label. Management, on the earnings call, said 60-65% of the half-year growth came from volumes.
Yet, this strength is constrained. The same call highlighted that container availability and disruptions on key routes, especially to the Middle East, limited the company's ability to fully capitalize on its order pipeline. Demand is there, but getting products to market remains a costly, logistical hurdle.
Funding growth from a position of strength
Capacity expansion continues, funded internally. The company has invested over ₹145 crore in the last two-and-a-half years, with another ₹40-45 crore planned for this fiscal year for its Surat, Nadiad, and Nashik facilities. This is supported by a healthy net surplus of ₹97.4 crore at the half-year mark.
The market's reaction was telling. According to MarketsMojo, the stock fell 8.8% on the results day as investors weighed the margin deterioration against the top-line beat. The firm carries a 'Hold' rating from the outlet, reflecting the tension between attractive growth and pressured profitability.
Key Points
- Revenue crossed ₹200 crore for the first time in a quarter, growing 23.6% year-on-year on robust volume-led demand.
- Net profit declined 4% year-on-year as a 360-basis-point margin squeeze erased operating leverage.
- The margin contraction was driven by a 40% surge in employee costs and elevated ocean freight expenses.
- A strong order book provides visibility, but growth conversion is hampered by ongoing container shortages and shipping route disruptions.
Hexa Perspective
ADF Foods is caught in a classic scaling challenge: revenues are climbing the wall, but costs are climbing faster. The next few quarters hinge on whether operating leverage from the new Surat plant and potential easing of freight pressures can outrun the structural rise in employee expenses.
The company's debt-free balance sheet and internal funding capacity give it room to navigate. However, until the profit line moves in step with the top line, the stock may continue to reflect the uncertainty of that transition, trading at a discount to its industry despite its growth record.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.