Ambica Agarbathies (AMBICAAGAR) Q2 FY27 Profit Squeezes Despite a 63% Revenue Surge
The incense maker's September quarter sales jumped sharply, but higher costs and a persistent hotel division loss kept net profit flat year-on-year.
Ambica Agarbathies reported a 16% yearly revenue increase to ₹40.23 crore in Q2 FY27, yet net profit grew a slower 15%. A sharp 63% sequential sales jump was entirely offset by margin pressure, leaving profitability strained.
For a company like Ambica Agarbathies, a sharp revenue jump should flow straight to the bottom line. The September quarter delivered that top-line surge, but the profit story was more complicated.
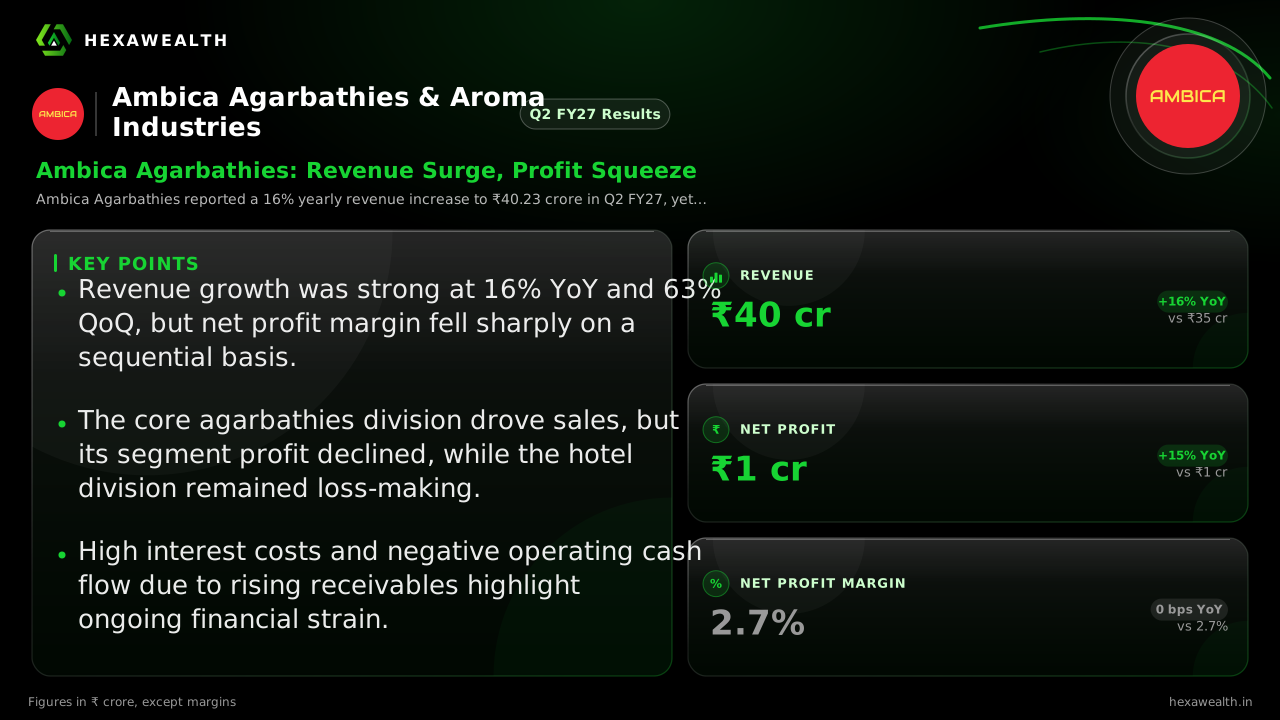
Revenue grew 16% year-on-year to ₹40.23 crore, while net profit rose 15% to ₹1.07 crore. The real story is sequential: sales soared 63% from the June quarter, but profit actually dipped 3%. The net profit margin compressed by 180 basis points to 2.7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 40.23 | 24.65 |
| Profit (₹ Cr) | 1.07 | 1.10 |
| Net Profit Margin (%) | 2.7 | 4.5 |
Why the growth didn't translate
The revenue surge was led by the core agarbathies division, which brought in ₹33.28 crore, up from ₹18.53 crore in the prior quarter, according to a report by Multibagg.ai. Yet, its segment profit before tax fell to ₹1.31 crore from a higher base a year ago. Meanwhile, the hotel division remained a drag, posting a loss of ₹0.11 crore, as noted by ScanX.trade.
Costs rose in lockstep with sales. Total expenses jumped 64% quarter-on-quarter. Employee costs were up 17.5% year-on-year, and depreciation surged 65% due to asset additions. This kept profitability in check despite the sales volume.
A persistent financial headwind
A high interest burden continues to cap earnings potential. Finance costs of ₹2.83 crore consumed a large portion of the operating profit. The debt-to-equity ratio stands at 1.69, with interest coverage a thin 1.22 times.
Worryingly, operating cash flow turned negative, with a ₹3.58 crore outflow for the first half, reports Multibagg.ai. This was driven by a ₹9.81 crore increase in trade receivables, indicating sales are not translating into cash.
Key Points
- Revenue growth was strong at 16% YoY and 63% QoQ, but net profit margin fell sharply on a sequential basis.
- The core agarbathies division drove sales, but its segment profit declined, while the hotel division remained loss-making.
- High interest costs and negative operating cash flow due to rising receivables highlight ongoing financial strain.
Hexa Perspective
This quarter shows Ambica Agarbathies can generate sales momentum, likely aided by seasonal demand. However, the business model is struggling to convert that into durable profit growth. The margin squeeze from rising costs and the cash flow strain from extended credit are structural concerns. The path to sustainable improvement hinges on better working capital management and reducing the reliance on debt. Until the hotel division turns consistently profitable and interest costs are brought down, earnings will likely remain volatile and capped, despite periodic revenue spikes.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.