APM Industries (APMIN) Q2 FY27 Profit Plunges 59% Despite a 33% Revenue Surge
The yarn maker's quarterly sales hit a five-quarter high, but a sharp margin squeeze and a swing in tax charges saw net profit halve from the previous quarter.
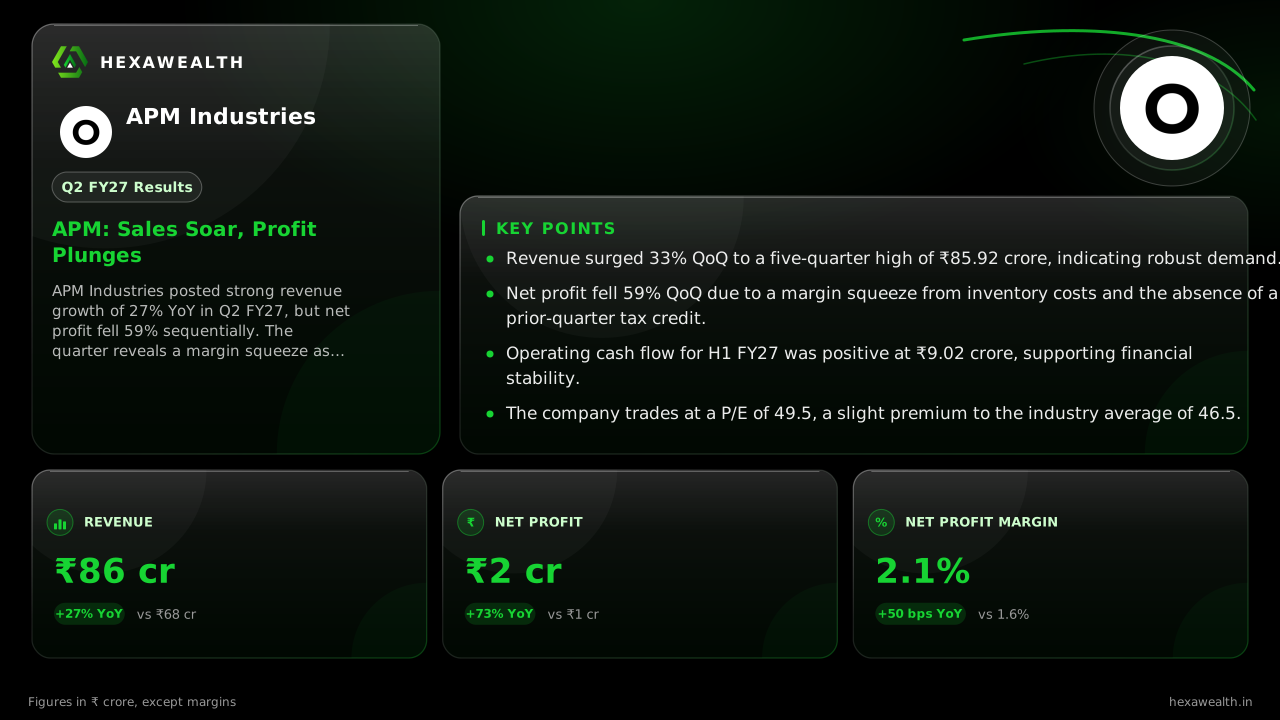
APM Industries posted strong revenue growth of 27% YoY in Q2 FY27, but net profit fell 59% sequentially. The quarter reveals a margin squeeze as costs rose in tandem with sales, while a one-off tax credit in the prior quarter flattered the comparison.
For a yarn manufacturer like APM Industries, a quarter of strong sales is typically a clear win. The September quarter delivered exactly that, with revenue reaching a five-quarter high. Yet the bottom line tells a more complicated story of costs keeping pace and a prior-quarter boost fading away.
Revenue grew 27% from a year ago and 33% from the June quarter to ₹85.92 crore. Profit before tax followed that trend, rising 31.7% sequentially. But net profit fell sharply to ₹1.83 crore, down 58.8% from the previous quarter. The net profit margin compressed to 2.1% from 6.9%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 85.92 | 64.41 |
| Net Profit (₹ Cr) | 1.83 | 4.44 |
| Net Profit Margin (%) | 2.1 | 6.9 |
Why the profit fell behind sales
A key driver was a large inventory build-up. ScanX Trade noted a change in inventories added ₹10.76 crore to expenses this quarter, compared to a reduction last year. This suggests the company produced or valued more stock than it sold, pressuring margins even as revenue climbed.
Total expenses rose 32.3% quarter-on-quarter, matching the revenue growth rate and preventing operating leverage. This kept the operating profit margin thin. The real hit to net profit, however, came from taxes.
The tax credit that disappeared
In the June quarter, APM Industries booked a significant deferred tax credit of ₹3.12 crore, as reported by Tradebrains. This one-off accounting benefit inflated the Q1 net profit to ₹4.44 crore. With that credit absent in Q2, profit normalized at a much lower level, explaining most of the steep sequential decline.
The company's cash flow remained healthy, with ScanX Trade reporting operating cash flow of ₹9.02 crore for the half-year. This provides a buffer against the volatile quarterly profitability seen over the past year.
Key Points
- Revenue surged 33% QoQ to a five-quarter high of ₹85.92 crore, indicating robust demand.
- Net profit fell 59% QoQ due to a margin squeeze from inventory costs and the absence of a prior-quarter tax credit.
- Operating cash flow for H1 FY27 was positive at ₹9.02 crore, supporting financial stability.
- The company trades at a P/E of 49.5, a slight premium to the industry average of 46.5.
Hexa Perspective
The quarter underscores APM Industries' core challenge: translating sales growth into consistent earnings. The revenue jump is encouraging, but profitability remains hostage to input cost movements and inventory management.
With no major capacity expansion plans noted in recent analysis, growth is reliant on operational efficiency in a tough cost environment. The stock's premium valuation seems to hinge on a belief in margin recovery, which this quarter's cost trajectory does not yet support.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.