Yatharth Hospital (YATHARTH) Q2 FY27's Profit Growth Lags Behind a 54% Revenue Surge
Yatharth Hospital's Q2 revenue soared 54% year-on-year, but profit growth slowed to 16% as expansion costs weighed on margins.
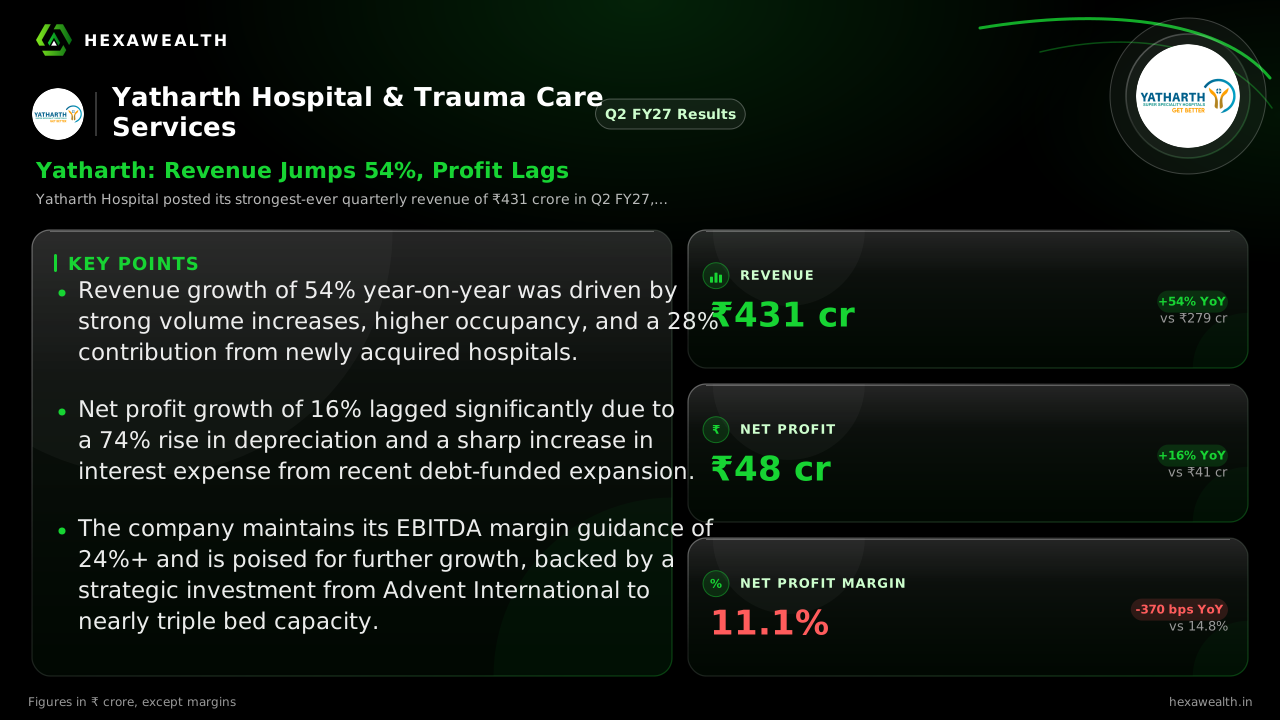
Yatharth Hospital posted its strongest-ever quarterly revenue of ₹431 crore in Q2 FY27, up 54%. Profit growth, however, slowed to 16% as depreciation and interest costs from a rapid bed expansion squeezed the bottom line.
For Yatharth Hospital, growth is measured in beds. Since its 2023 listing, the North India-focused chain has more than doubled its capacity, and the September quarter showed that push hitting its stride. Revenue hit a record ₹431 crore, soaring 54% from a year earlier. Yet the profit story is quieter, rising just 16% as the costs of building that scale finally reached the income statement.
The numbers tell of a business in two gears. While revenue climbed 10% from the June quarter, profit grew a more modest 6%. The net profit margin compressed to 11.1%, down 370 basis points year-on-year. A look across the last five quarters shows revenue on a steep climb, while profit growth has been steadier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 431.0YoY +54% | 392.7 | 279.4 |
| Profit (₹ Cr) | 48.0YoY +16% | 45.4 | 41.3 |
| Net Profit Margin | 11.1%YoY -25% | 11.6% | 14.8% |
Why the profit engine sputtered
The gap stems from what happens below the operating line. According to reports from CNBC TV18 and Multibagg.ai, depreciation surged 74% year-on-year to ₹33 crore, and interest expense ballooned from a negligible base to ₹8 crore. These are the non-cash and financing charges of a company that has aggressively added hospitals. Management noted in its earnings call that newer facilities now contribute 28% of group revenue, up from 11% a year ago.
Operationally, the quarter was strong. Investing.com reported revenue beat analyst forecasts by 1.5%. Occupancy rose to 72%, and the average revenue per occupied bed increased 11% to ₹36,000. This was driven by higher patient volumes and a richer mix of cash and private insurance payers.
The costs that will not fall soon
These expansion-related costs are structural, not temporary. The company is in the middle of a capital cycle, with a ₹3,150 crore investment from Advent International awaiting approval to fund a target of 7,000-8,000 beds. While newer units like Faridabad Sector-20 and Agra have turned EBITDA-positive, the New Delhi hospital is still ramping up. Depreciation and interest will remain elevated as more beds come online.
Management, according to the Alphastreet transcript, reaffirmed its EBITDA margin guidance of 24% or more for the coming years. They estimate a new regulatory cap on cancer drug margins will have only a 0.3% impact, which they plan to offset through operational efficiencies.
Key Points
- Revenue growth of 54% year-on-year was driven by strong volume increases, higher occupancy, and a 28% contribution from newly acquired hospitals.
- Net profit growth of 16% lagged significantly due to a 74% rise in depreciation and a sharp increase in interest expense from recent debt-funded expansion.
- The company maintains its EBITDA margin guidance of 24%+ and is poised for further growth, backed by a strategic investment from Advent International to nearly triple bed capacity.
Hexa Perspective
The quarter confirms Yatharth is successfully executing its land-and-expand strategy in North India. The revenue beat and operating metrics show underlying demand is robust. The margin compression, however, is the direct cost of that ambition.
Investors are effectively paying for future capacity today. The stock's positive reaction to the results suggests the market is prioritizing top-line momentum and the long-term bed story over near-term margin pressure. The key watchpoint is whether the company can ramp new units to profitability fast enough to keep consolidated margins near its 24% guide as even more beds are added. The Advent capital provides a long runway, but the quarterly profit walk will remain a feature, not a bug, for the next few years.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.