Vishal Fabrics (VISHAL) Q2 FY27 Profit Rises 12% Despite a 15.5% Drop in Revenue
The denim maker delivered a quarterly profit of ₹12 crore by prioritizing cost cuts over sales volume in a soft demand environment.
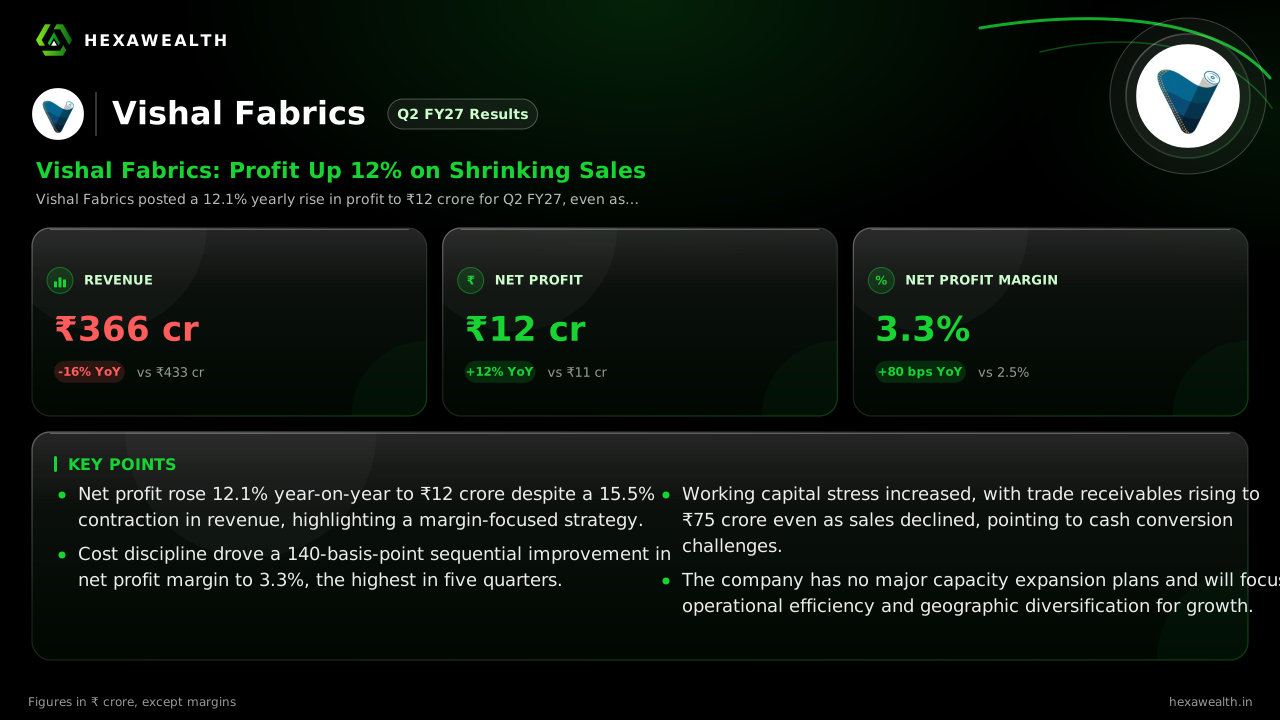
Vishal Fabrics posted a 12.1% yearly rise in profit to ₹12 crore for Q2 FY27, even as revenue fell 15.5% to ₹366 crore. The gain was driven by a sharp focus on cost discipline and tighter raw material management.
For a textile manufacturer, a quarter where profit grows while sales shrink is a clear signal of a strategic pivot. Vishal Fabrics chose margin protection over chasing volume, delivering a 12.1% yearly profit rise on a 15.5% smaller revenue base.
The numbers tell a story of disciplined retrenchment. Revenue fell to ₹366 crore from ₹433 crore a year ago, marking the second consecutive quarter of decline. Yet, net profit climbed to ₹12 crore, pushing the net profit margin to 3.3%, its highest in the last five quarters.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 366.0 | 379.1 |
| Profit (₹ Cr) | 12.0 | 7.2 |
| Net Profit Margin (%) | 3.3 | 1.9 |
The cost-cut engine
Management, quoted by Smestreet.in, said the profit rise was triggered by a “sustained focus on efficiency and cost discipline.” The company prioritized “quality of earnings over volume” in a softer demand environment. This translated into a 28.7% yearly drop in depreciation and a 4.9% fall in interest costs, according to the payload.
The strategy lifted the standalone EBITDA margin to 7.9%, a 110-basis-point improvement from a year ago as noted by Multibagg.ai. However, this margin-first approach has a visible trade-off: trade receivables swelled to ₹75 crore at the end of September, up from ₹65 crore in March, indicating potential collection pressures.
A cautious path forward
With no major capacity expansion plans, according to an India Ratings report, growth depends on stabilizing sales. The new CEO, appointed alongside the results, will focus on operational efficiency and new geographies like Latin America and Europe. The rating agency expects leverage to rise due to higher working capital needs and cotton prices.
The market welcomed the margin surprise, with the stock gaining over 4% on results day, as reported by The Daily Jagran. The valuation, at a P/E of 10.5, trades at a steep 65% discount to the industry, reflecting persistent concerns over top-line growth.
Key Points
- Net profit rose 12.1% year-on-year to ₹12 crore despite a 15.5% contraction in revenue, highlighting a margin-focused strategy.
- Cost discipline drove a 140-basis-point sequential improvement in net profit margin to 3.3%, the highest in five quarters.
- Working capital stress increased, with trade receivables rising to ₹75 crore even as sales declined, pointing to cash conversion challenges.
- The company has no major capacity expansion plans and will focus on operational efficiency and geographic diversification for growth.
Hexa Perspective
The quarter demonstrates Vishal Fabrics' ability to defend profitability when demand weakens, a crucial skill in a cyclical industry. The improved margin is a positive operational read, but its sustainability is the open question.
Profit growth now hinges entirely on maintaining these cost controls, as a further slide in revenue would eventually pressure absolute earnings. The rising receivables and negative operating cash flow, noted in research, mean reported profits are not yet converting into cash—a key monitorable for balance sheet health.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.